


EN
Progyny (PGNY) Could Be 15% Below Fair Value After Revenue Guidance Cut
Progyny (PGNY) is back in focus after management cut full year revenue guidance, pointing to what they describe as seasonal softness in fertility benefit utilization, as Q3 2026 results approach on November 3.
Recent trading tells a mixed story for Progyny. The 1 month share price return of 16.57% and 7 day gain of 4.55% suggest momentum has picked up again after a 90 day share price decline of 6.58%. At the same time, the 1 year total shareholder return of 59.58% contrasts with a 5 year total shareholder loss of 55.88%.
Compare Progyny's reset expectations with other potential opportunities by scanning our hand picked list of 34 high quality undervalued stocks across the market.
Bulls see Progyny as a reset story after a guidance cut, while bears see a business facing softer demand. Which side do today’s valuation signals lean toward as the numbers are marked down?
Most Popular Narrative: 14.5% Undervalued
Progyny's most followed valuation view points to a fair value of $34.42 versus the latest close at $29.41. This implies investors are still pricing the reset cautiously, even as that narrative leans more supportive on cash generation and platform reach.
The main thing that has to go right is that Progyny converts its ongoing platform and product investments, including newer women's and family health offerings and health plan partnerships, into sustained adoption that supports its roughly 17% adjusted EBITDA margin profile while addressing concerns about growth and scale.
See why 27 investors see Progyny as 15% undervalued.
Result: Fair Value of $34.42 (UNDERVALUED)
Still, the story can crack if employers pull back on richer fertility and women’s health benefits, or if Progyny’s newer services struggle to gain traction.
Find out about the key risks to this Progyny narrative.
Another View: Progyny On Earnings Multiples
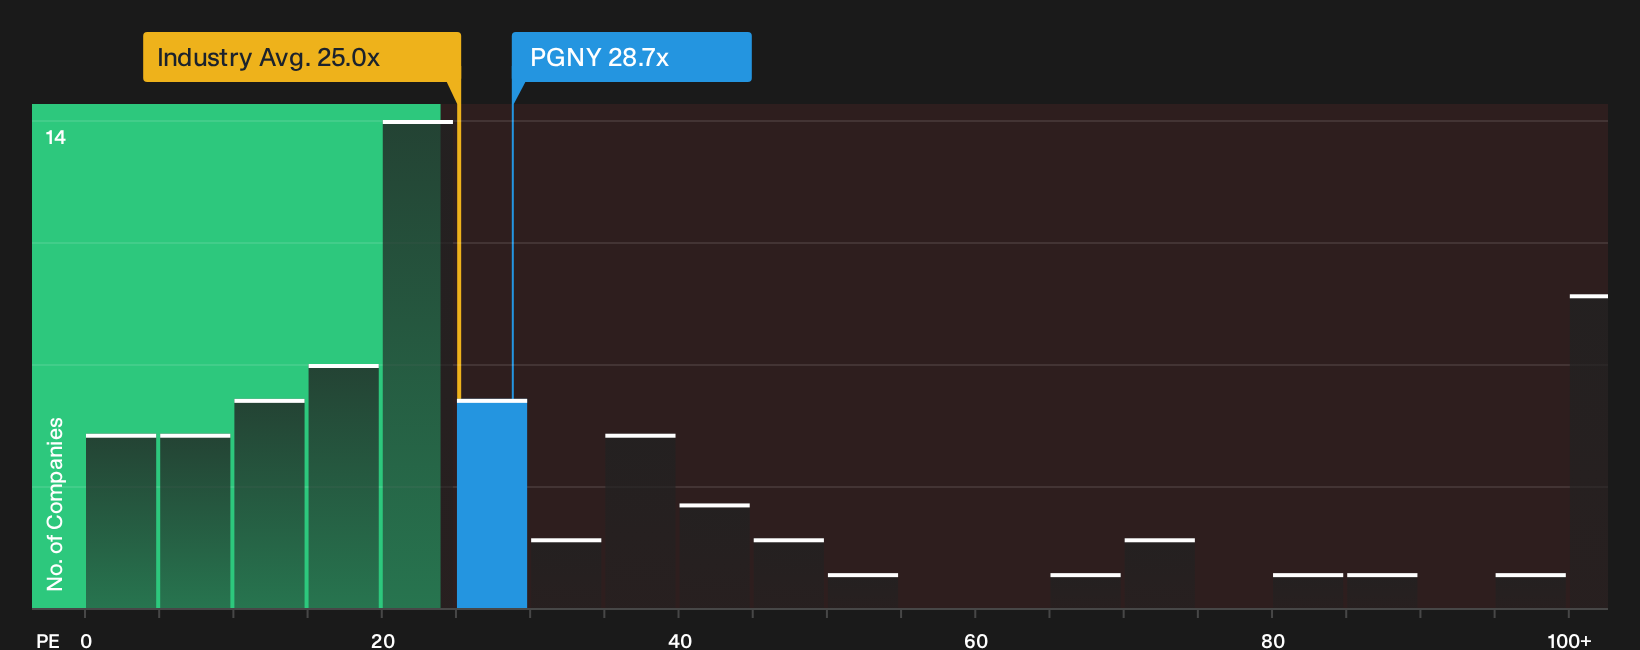
Progyny might look undervalued against the $34.42 fair value from the most popular narrative, but its current P/E of 28.7x tells a tighter story. That multiple is higher than the US Healthcare industry on 25x and above a fair ratio of 27.6x that the market could move toward.
If sentiment cools and the share price drifts closer to that fair ratio or the wider sector, investors would feel that shift through a lower implied valuation rather than changing business results. The question is whether Progyny’s earnings profile justifies staying on a premium multiple, or if that gap becomes valuation risk as expectations reset. See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If sentiment around Progyny still feels split after this reset, consider moving quickly, reviewing the numbers yourself, and weighing the 3 key rewards.
Looking for more Progyny style investment ideas?
If Progyny has you rethinking your watchlist, do not stop here. Broader context sharpens judgment and fresh ideas often show up where you least expect them.
- Spot potential upside early by scanning a 8 elite penny stocks with strong financials that filters for smaller companies with stronger financial underpinnings than the typical microcap story.
- Zero in on quality at a price by reviewing a 19 high quality undiscovered gems that highlights businesses with solid fundamentals the wider market may be overlooking.
- Dial down portfolio stress by using a 29 resilient stocks with low risk scores focused on resilient companies with lower risk scores when markets feel unpredictable.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com