


EN
Do Earnings Change The Bull Case For TFI International Stock (TSX:TFII)?
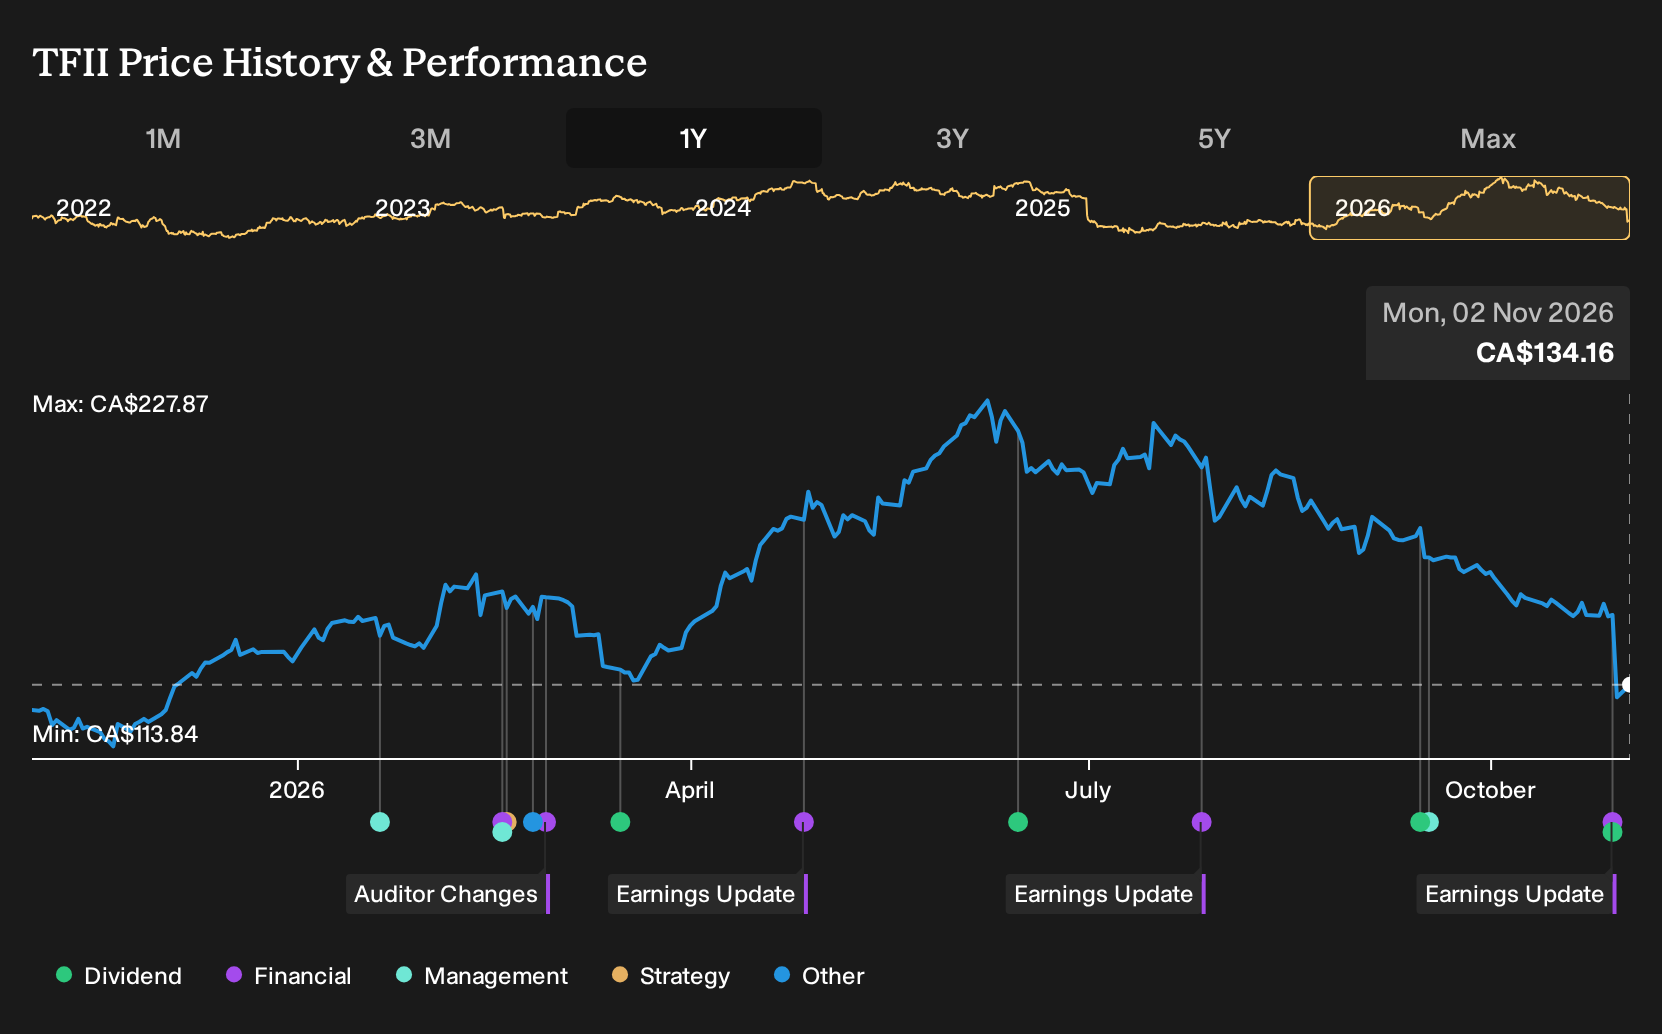
- TFI International reported third quarter 2026 revenue of US$2.23b and net income of US$105.71m, with earnings per share from continuing operations modestly higher than a year earlier and a quarterly dividend of US$0.47 per share approved for payment in January 2027.
- Results reflected strong Truckload and Logistics contributions, while a pressured US less than truckload unit and a lack of share repurchases highlighted where execution and capital deployment remain constrained.
- The potential impact on TFI International's investment narrative will likely depend on how strong Truckload and Logistics performance interacts with ongoing pressure in the US LTL segment.
Scan how TFI International’s latest earnings compare with a curated group of freight, logistics and transportation peers, using the list of solid balance sheet and fundamentals (6 results) as a starting universe.
TFI International Investment Narrative Recap
To own TFI International, you need to believe the stronger Truckload and Logistics engines can keep offsetting a weaker U.S. LTL operation. The latest quarter fits that picture. Earnings per share from continuing operations were higher, and segment data points to healthier truckload and brokerage economics while the U.S. LTL unit remains the main fix-it project.
The near term catalyst is clear. Investors are watching whether management can lift U.S. LTL pricing, density and service enough to stop it weighing on group margins. That pressure, together with higher purchased transportation and fuel costs, still looks like the biggest operational risk in the story right now.
The dividend decision on October 29, 2026 is the most relevant move alongside these results. TFI International’s board approved a quarterly payout of US$0.47 per share, with an expected aggregate payment of US$38.4 million in January 2027. That indicates the balance sheet and cash generation currently support ongoing returns to shareholders.
For you as an investor, the key link is between that cash commitment and the capital needs of the U.S. LTL turnaround. Management has room to keep funding dividends while working on pricing, freight mix and network changes. However, any prolonged LTL underperformance or higher borrowing costs could tighten that flexibility and temper how much capital can be pushed back to investors over time.
TFI International's current analyst narrative points to $10.0b in revenue and $930.9m in earnings by 2029. That profile assumes 6.0% yearly revenue growth and an earnings increase of about $574m from the $356.8m reported today.
Uncover how TFI International's fair value indicates a 68% potential upside to its current price before the market closes the discount.
Exploring Other Perspectives
Some of the lowest ranked analysts frame a very different risk for TFI International. They focus on the chance that new delivery models and technology pressure traditional freight revenue, and before this earnings release they were only projecting about US$9.7b of revenue and US$862.9m of earnings by 2029. That is a markedly more cautious story than consensus. These views were formed before the latest results and dividend affirmation, so treat this quarter as fresh information that could either soften or reinforce that more pessimistic narrative as you compare several viewpoints for yourself.
Explore 4 other TFI International fair value estimates, including one that suggests it could be worth just CA$192.19!
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your TFI International research is our analysis highlighting 6 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for TFI International. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate TFI International's overall financial health at a glance.
Looking For More Investment Ideas Beyond TFI International?
If you want to cross check TFI International against other opportunities, a quick pass through a few targeted screeners can surface stocks with very different risk and return profiles that still meet your basic quality filters.
- Focus on quality at a discount by scanning a curated pool of companies that combine stronger fundamentals with attractive pricing through the 5 high quality undervalued stocks.
- If capital preservation comes first for you, filter for businesses with more resilient financial profiles and steadier risk scores using the 9 resilient stocks with low risk scores.
- For investors who like spotting potential early, cast a wider net over under-followed contenders with healthier fundamentals via the 8 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com