


EN
Is Essex Property Trust (ESS) A Bargain As It Raises 2026 Earnings Guidance?
Essex Property Trust (ESS) just lifted its full year 2026 earnings guidance after reporting third quarter results that combined higher revenue with lower net income. That mix gives investors a fresh data point to reassess expectations.
Essex Property Trust shares closed at US$265.56 on 1 November, with the 1-day share price return of 0.52% offering only a small lift after a 90-day share price decline of 7.54%. At the same time, the 1-year total shareholder return of 8.56% points to momentum that has been built gradually over time. The raised 2026 earnings guidance and the US$19.25 million tenant settlement now sit alongside that mixed price pattern, giving investors fresh context to judge whether the recent share price softness is about short term concern over earnings volatility or a reassessment of long term risk and income potential.
Capitalize on Essex Property Trust's mixed earnings signal by scanning a curated group of resilient real estate and income-focused companies in our 29 resilient stocks with low risk scores.So with Essex Property Trust lifting guidance while net income and the share price both tell a more cautious story, is the current valuation offering more potential upside for new buyers or greater downside risk?
Most Popular Narrative: 11% Undervalued
With Essex Property Trust closing at $265.56 against a widely followed fair value estimate of $298.03, the current gap hinges on how West Coast supply, AI driven demand, and capital allocation play out over time.
Limited new multifamily supply in Essex Property Trust's core West Coast markets, including about 0.3% of stock in Northern California and deliveries in Seattle now below 1% of stock, continues to restrict competition for quality units and can support rent growth and occupancy, which feeds directly into revenue and same property NOI.
See why 11 investors see Essex Property Trust as 11% undervalued.
Result: Fair Value of $298.03 (UNDERVALUED)
Still, the whole Essex Property Trust narrative can wobble quickly if Southern California delinquencies persist or local regulatory and tax changes hit demand in its concentrated markets.
Find out about the key risks to this Essex Property Trust narrative.
Another Angle On Essex Property Trust’s Valuation
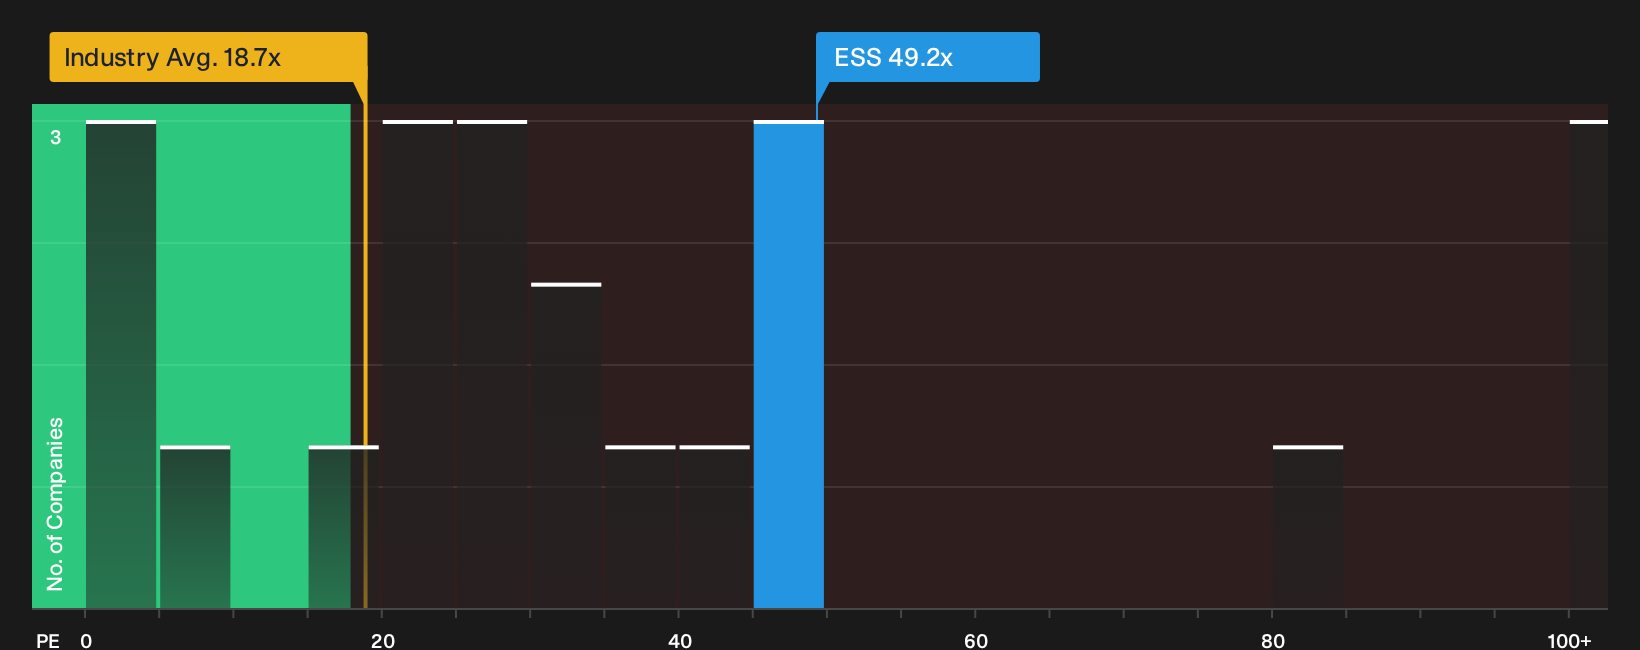
The first narrative leans on a fair value of $298.03 and calls Essex Property Trust undervalued. A simple P/E check paints a different picture. The current P/E of 49.2x sits well above the 35.2x fair ratio, the 34.2x peer average, and the 18.7x global Residential REIT mark. That premium loads more valuation risk onto any earnings wobble. So is the discount story really about cash flows, or just a rich multiple waiting to reset?
Before leaning too hard on any single ratio, it helps to see what the numbers imply about future pricing power and re rating risk. This is laid out in more detail in the See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Mixed signals on Essex Property Trust can easily pull you in either direction. Move quickly from headline impressions to hard evidence and weigh both the concern around potential risks and the optimism around possible rewards by reviewing the 3 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Essex Property Trust?
If Essex Property Trust has sharpened your focus on valuation and risk, you can broaden your opportunity set by scanning high conviction ideas that match your own return and resilience goals.
- Target quality at a discount by reviewing companies screened as 34 high quality undervalued stocks that combine strong fundamentals with pricing that may not yet reflect their underlying strength.
- Strengthen your potential income stream by focusing on resilient payers using our curated set of 4 dividend fortresses that prioritise consistent distributions.
- Prioritise staying power by concentrating on balance sheets that look built to endure with the list of solid balance sheet and fundamentals (24 results).
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com