


EN
Intel's collapse sounded a wake-up call! As AI fears heat up, AMD (AMD.US) needs a strong guide to avoid repeating the same mistakes
The Zhitong Finance App notes that AMD (AMD.US) is one of the best performing chip stocks this year, but as market questions about AI spending heat up, the company's earnings report released after the market on Tuesday needs to show strong performance and a positive outlook to maintain this trend.
Neville Javary, portfolio manager at Allspring Global Investments, who owns the stock, said: “To keep it rising, it takes more than just exceeding expectations once, but also significantly exceeding expectations accompanied by a very strong outlook. A mediocre financial report won't work.”
Although Wall Street expects AMD to release strong earnings, the timing of the earnings release comes at a time when investors are rushing to sell off the disappointing news. Due to weak prospects, Intel (INTC.US) recorded its worst single-day performance since data was available in 1982 last Friday. Prior to that, big AI buyers such as Alphabet (GOOGL.US), Meta Platforms (META.US), and Amazon (AMZN.US) were also being penalized on their stock prices because their huge investments were eroding cash flow.
Like AMD, Intel has been a significant runner this year, as AI spending is driving demand for its central processor (CPU) chips. Prior to the release of the earnings report, Intel had increased by 150% in 2026. By Monday's close, however, that increase had shrunk to 63%.
AMD's stock price fell due to Intel's drag. It fell 10% last Friday, with a cumulative drop of more than 17% in October. However, the stock is still up about 118% this year, far exceeding the 46% increase in the Philadelphia Semiconductor Index (SOX).
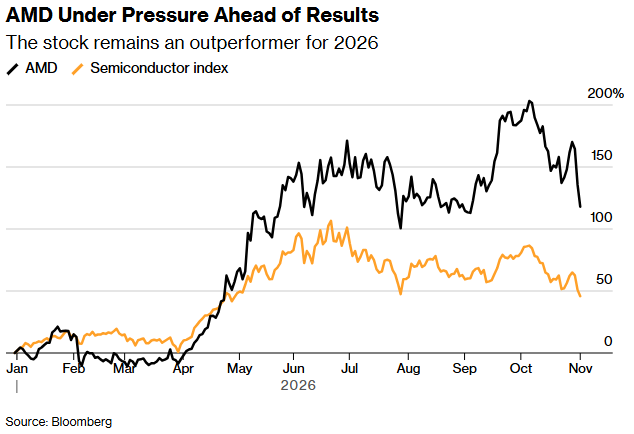
AMD faces pressure ahead of earnings release
This round of gains made AMD stock seem expensive compared to other chipmakers. Its transaction price is equivalent to 32 times the expected profit for the next 12 months. It is the fourth highest valuation multiple among SOX constituent stocks, lower than the 56 times high on June 30. However, AMD has always been a high-priced stock, with an average valuation multiplier of about 34 times since 2017.
Wall Street analysts expect AMD's third-quarter profit to jump 92% and revenue to grow 41%, and these two figures are expected to rise further in 2027. CEO Su Zifeng said last month that the company expects chip demand to be “very high” in the next few years, exceeding supply.
CPUs play a key role in AI infrastructure because they are critical to the operation of agents (agents), and thanks to the success of Meta's Muse, agents have taken the market by storm. According to the data, these chips contributed nearly a quarter of AMD's revenue in 2025.
According to supply chain data, Meta is AMD's second-largest customer, accounting for 5.5% of the chipmaker's revenue. The popularity of Muse has prompted some analysts to raise their target price for AMD, and Rosenblatt Securities analyst Kevin Cassidy listed it as number one in the earnings season and went multi-target.
Allspring's Javary said, “Investors need to see evidence that growth is accelerating, and Muse is definitely a credible catalyst.”
This may explain why Wall Street's consensus forecast for AMD's 2027 net profit increased 23% over the past three months, revenue expectations increased 14%, and the 2028 increase was even greater. The stock is expected to rise 40% over the next 12 months, according to the analysts' average price target price tracking.
The biggest risk before AMD's earnings report is probably the worsening investor sentiment surrounding AI transactions and investors' sensitivity to any disappointing news. In the past two weeks, the negative reaction to AI capital expenditure in the financial reports of AI hyperscale cloud vendors is increasing market concerns about shrinking spending, and this will seriously affect chip makers like AMD that rely on this kind of generous investment to continue.
Wealth Consulting Group Chief Investment Officer Jim Warden has withdrawn from AMD positions due to an uncertain background and the stock's overvaluation, but he continues to hold other chipmakers such as Nvidia (NVDA.US), Broadcom (AVGO.US), and TSM.US.
He said, “We are probably in a period where AMD is moving from good growth to super rapid growth. Things like Muse act as an accelerator, but I'm just not sure about the valuation. There are just too many uncertainties.”
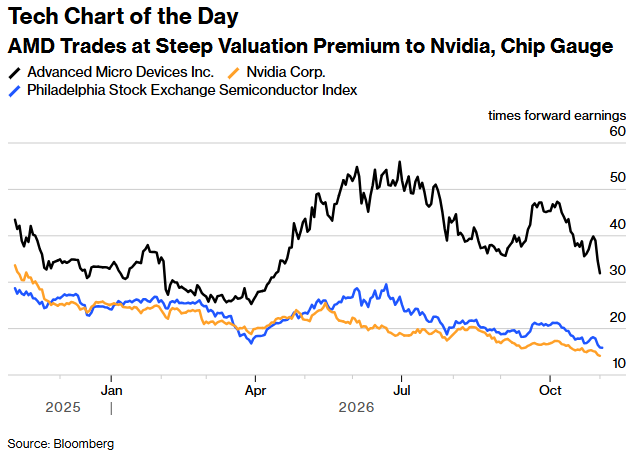
AMD's valuation is too high a premium compared to Nvidia