


EN
Watsco (WSO) Moved Higher, What Is Drawing Investor Attention Now?
How Watsco’s Latest Earnings Are Shaping Investor Focus
Watsco (WSO) just put fresh numbers on the table. Third quarter and nine month 2026 results showed higher sales but softer net income and earnings per share, a mix that tends to sharpen market attention.
The headline figures are clear. Third quarter sales came in at US$2,220.36 million compared with US$2,067.01 million a year earlier, while net income slipped to US$155.37 million from US$161.58 million and diluted EPS eased to US$3.77 from US$3.98.
Recent trading suggests investors are reassessing Watsco after these results and the new US$750 million credit facility. The share price is up 6.47% over the past month, but the year-to-date share price return is down 8.82%, with a 1-year total shareholder return decline of 9.18% framing that short-term momentum as a rebound rather than a clear trend shift.
Scan how Watsco’s mixed earnings pattern compares with other industrials by reviewing the hand picked list of solid balance sheet and fundamentals (24 results) in this sector.
Watsco’s share price has bounced after mixed earnings, yet longer term returns have been softer. Is most of the recovery already in the rearview mirror, or does the current valuation still leave meaningful upside on the table?
Most Popular Narrative: 9% Undervalued
Watsco’s most followed narrative pegs fair value at $349.70 versus the last close at $316.71. The gap to that estimate remains in focus for anyone weighing the recent earnings wobble against the longer term story.
The main thing that has to go right is that Watsco converts its heavy ongoing technology spend and growing e-commerce and OnCall Air usage into sustained gross margin progress toward its stated 30% target while managing OEM pricing and regulatory shifts.
See why 14 investors see Watsco as 9% undervalued.
Result: Fair Value of $349.70 (UNDERVALUED)
Still, the narrative around Watsco hinges on tighter execution, since further gross margin pressure from OEM pricing or A2L related costs could quickly undercut the undervaluation case.
Find out about the key risks to this Watsco narrative.
Another View On Watsco’s Valuation
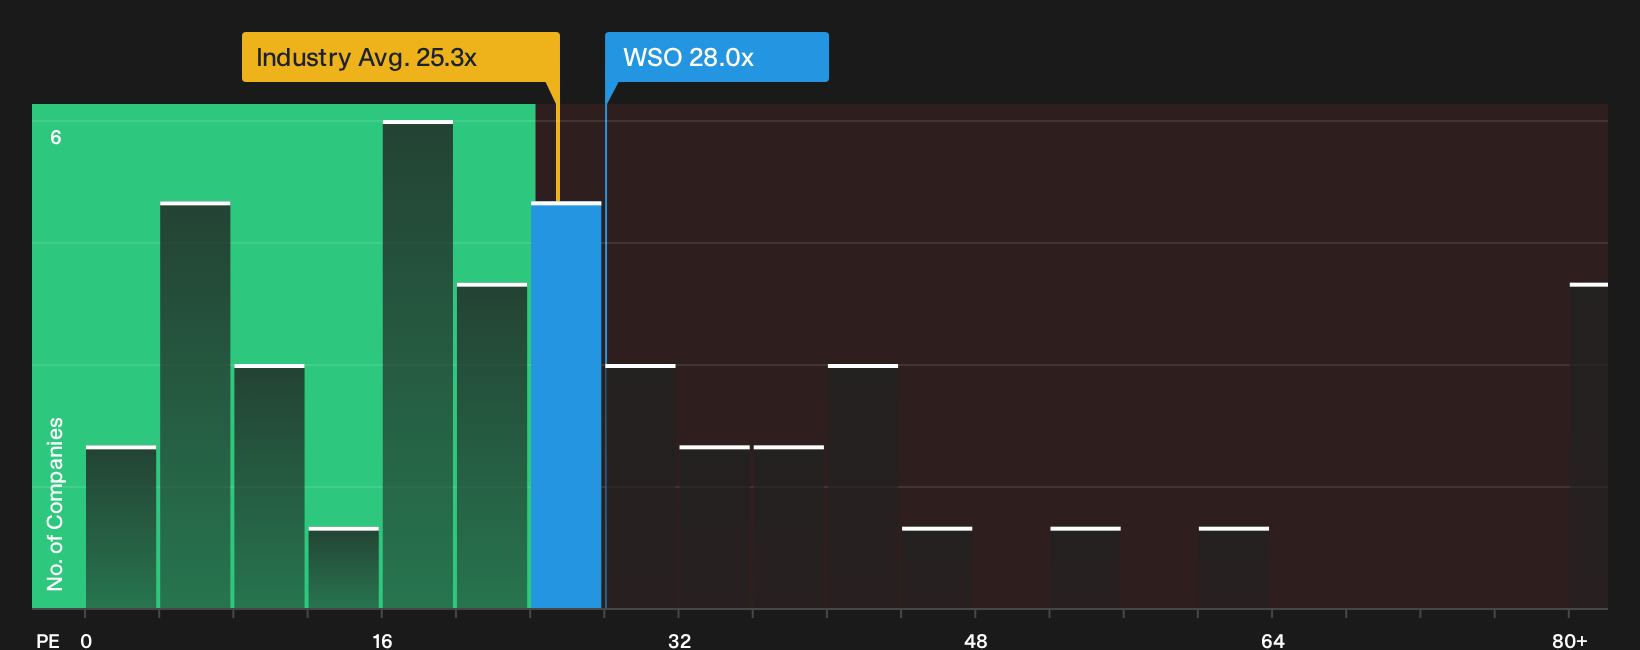
The fair value story for Watsco looks very different when the focus shifts to its P/E ratio. The stock trades on 28x earnings compared with 23.6x for peers and a fair ratio of 22.8x. That premium points to valuation risk if sentiment or earnings stumble again.
For a closer look at how this P/E gap squares with the rest of the numbers, including peers and the fair ratio the market could move toward over time, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
With mixed signals around Watsco’s valuation and fundamentals, sentiment is clearly split, so move quickly, review the data, and weigh the 2 key rewards and 1 important warning sign.
Looking For More Investment Ideas Beyond Watsco?
If Watsco has sharpened your focus on valuation and quality, do not stop here. Broaden your watchlist today so you are not chasing the next move after it happens.
- Target resilient balance sheets and steady fundamentals by scanning a curated list of solid balance sheet and fundamentals (24 results) that filters for financial strength first.
- Hunt for potential mispricings by reviewing a focused 34 high quality undervalued stocks built to spotlight quality businesses that may trade below their assessed worth.
- Prioritize income potential and stability by sizing up a hand picked 4 dividend fortresses tailored to investors who want yield with defensive characteristics.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com