


EN
Is KB Home (KBH) A Bargain After Lower Inflation Hopes Lift Builder Stocks?
A potential reopening of the Strait of Hormuz has shifted attention back to interest costs and fuel prices. KB Home (KBH) is moving with other builders as investors reassess housing demand under lower inflation expectations.
KB Home’s latest jump, including a 5.67% 1 day share price return and 9.30% 7 day share price return, comes after a tougher stretch where the 90 day share price return declined 12.73% and the 1 year total shareholder return fell 15.56%. This pattern may suggest short term momentum building following a weaker year.
Scan how KB Home stacks up against other builders by reviewing a curated group of list of solid balance sheet and fundamentals (24 results) that may also benefit if lower inflation keeps supporting housing demand.
KB Home has rebounded quickly on hopes for easing inflation after a weaker year for holders. After this sharp move, does the balance of risk and reward still lean toward buyers as valuation comes under the microscope next?
Most Popular Narrative: 2% Undervalued
KB Home’s most followed valuation narrative points to a fair value of $51.57, a touch above the last close at $50.66. This puts recent price strength in the context of only a modest implied discount using a 10.1% discount rate.
The current valuation implies the share price does not fully reflect this narrative that KB Home is undervalued and that its Build-to-Order model and capital returns program carry meaningful upside potential.
KB Home is focusing on maintaining attractive pricing by offering compelling value relative to local market conditions, and is now leaning more on higher margin Built to Order product that carries a margin premium compared with inventory homes as that mix trends toward roughly three quarters of deliveries. This mix shift can support housing gross margin and earnings.
See why 15 investors see KB Home as 2% undervalued.
Result: Fair Value of $51.57 (UNDERVALUED)
Still, the narrative around KB Home can crack if weaker buyer demand repeats past periods of 20% revenue and 19% delivery declines, or if rising resale inventory forces deeper price cuts.
Find out about the key risks to this KB Home narrative.
Another View: KB Home Through The DCF Lens
The popular KB Home story leans on a fair value of $51.57, slightly above the $50.66 share price. Our DCF model points in the opposite direction. On that cash flow view, future value lines up closer to $33.82, which frames recent gains as a potential valuation headwind. Which lens do you trust more when growth and margins are both in flux?
Look into how the SWS DCF model arrives at its fair value.
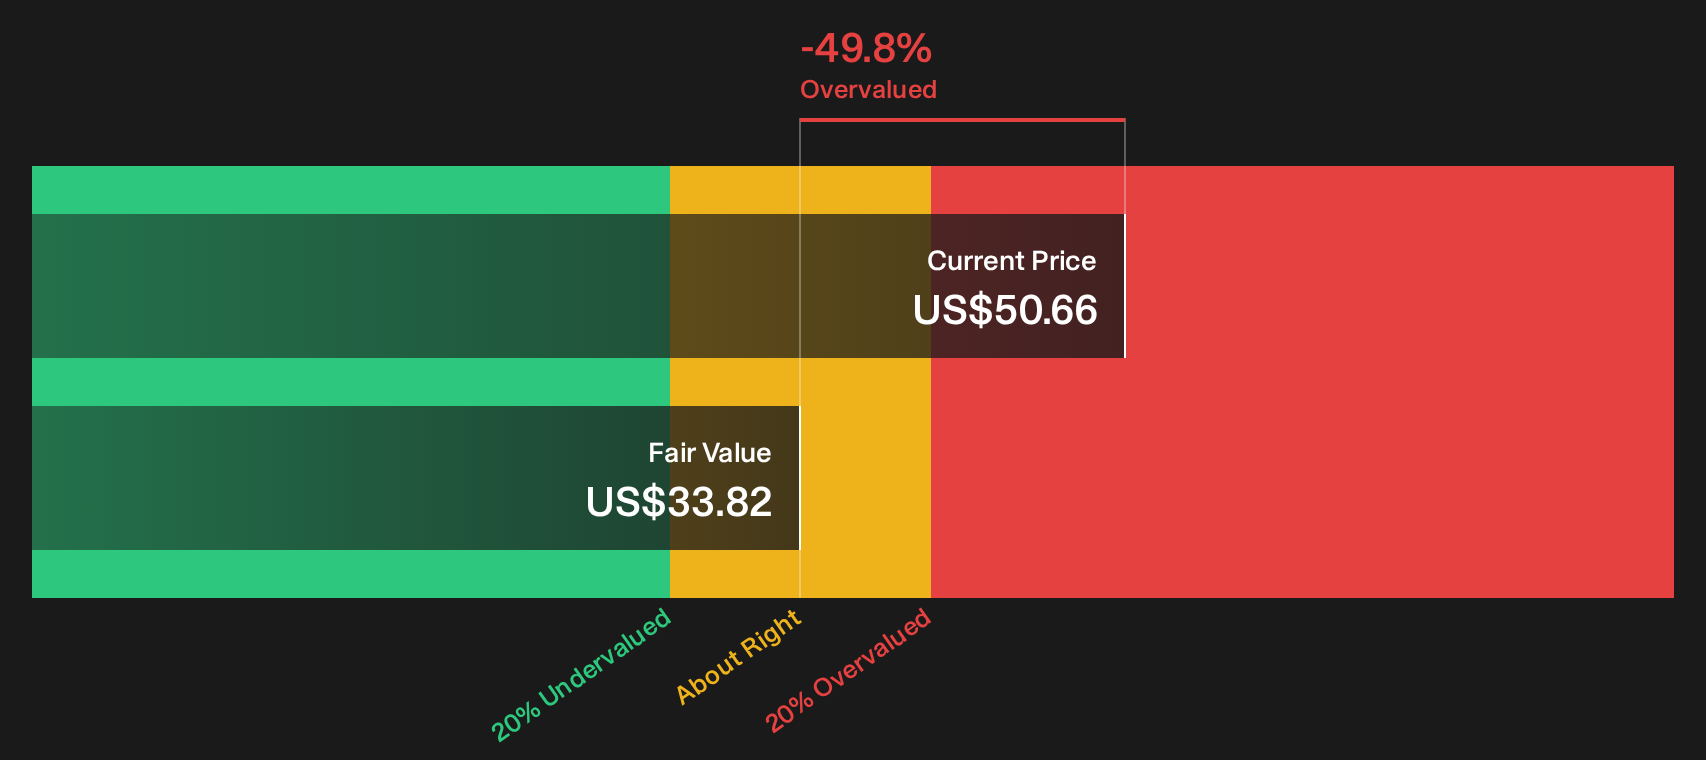
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out KB Home for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 34 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Sentiment around KB Home is clearly mixed, with both caution and optimism in play. Move quickly, review the underlying data, and decide where you land on its story of potential. A useful place to start is by weighing the 3 key rewards and 4 important warning signs.
Looking For More Investment Ideas Beyond KB Home?
If KB Home has you thinking harder about valuation and risk, do not stop here. Broaden your watchlist with focused screeners that surface clear, data backed ideas.
- Spot potential mispricings early and review a carefully filtered pool of 34 high quality undervalued stocks before the crowd catches on.
- Strengthen your portfolio’s foundation and focus on balance sheet resilience by scanning a curated list of solid balance sheet and fundamentals (24 results).
- Hunt for overlooked quality and use a focused list of 19 high quality undiscovered gems that might not yet be on most investors’ radar.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com