


EN
Banco de Sabadell (BME:SAB) Following Q3 Results Looks Close To Fair Value
Q3 earnings put Banco de Sabadell in focus
Banco de Sabadell (BME:SAB) moved into the spotlight after reporting third quarter 2026 results, with net interest income of €920 million and quarterly net income of €405 million.
Recent trading has been steadier than the earnings headlines suggest. Banco de Sabadell’s share price return is up 2.94% over the past 90 days and 1.68% year to date, while the 1 year total shareholder return of 23.29% and very large 5 year total shareholder return point to momentum that has been building over a much longer stretch. The Q3 update offers a fresh reference point for how the market prices that progress at the current €3.504 level.
Compare Banco de Sabadell’s steady Q3 profile with other hand picked banks that combine balance sheet strength and earnings power using our list of solid balance sheet and fundamentals (196 results)
For Banco de Sabadell, a steady share price and measured Q3 figures leave a familiar dilemma. Is €3.504 a fair entry now, or does patience make more sense once valuation is on the table?
Most Popular Narrative: 4% Undervalued
On the most followed view of Banco de Sabadell, a fair value of €3.66 sits slightly above the latest €3.504 close. This puts attention on what is driving that small gap rather than the headline number itself.
Sustained increase in customer funds, particularly through off-balance sheet investment and savings products (up 6.7% year-on-year), demonstrates growing customer engagement and enables greater cross-selling of fee-based products, supporting long-term growth in recurring fee income and revenue diversification.
See why 30 investors see Banco de Sabadell as 4% undervalued.
Result: Fair Value of €3.66 (UNDERVALUED)
Still, heavy reliance on Spain and ongoing pressure on customer margins could weaken the Banco de Sabadell fee and efficiency story if those trends persist.
Find out about the key risks to this Banco de Sabadell narrative.
Another View: Banco de Sabadell Through The P/E Lens
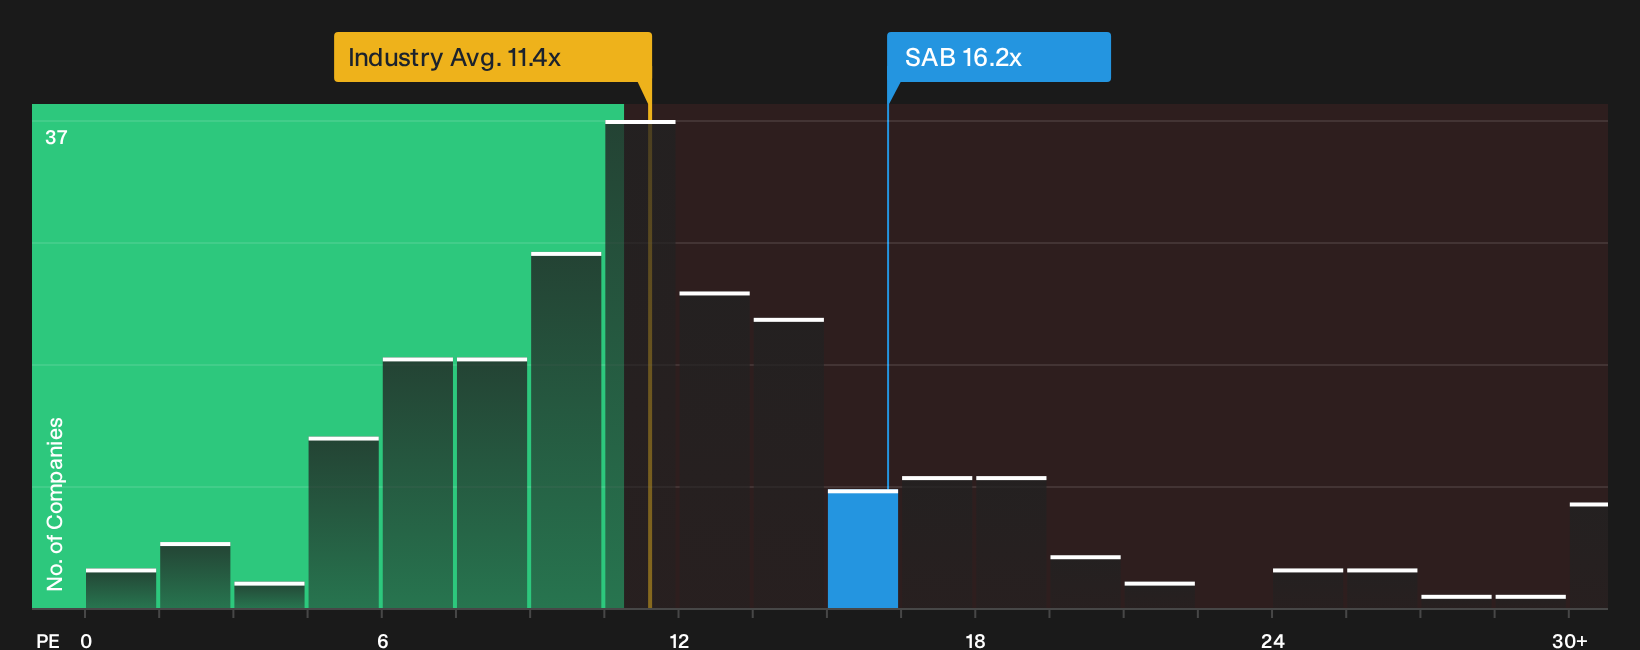
There is a catch to the “4% undervalued” story for Banco de Sabadell. On current numbers the shares trade on a P/E of 16.2x, while both the fair ratio and peer averages sit at 11.7x, and the broader European banks group is at 11.4x. That gap points to valuation risk if sentiment cools or earnings disappoint, so which signal do you trust more right now, the cash flow model or the market’s current multiple?
To unpack what this richer P/E and the fair ratio could mean for your own checklist, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages on Banco de Sabadell’s value story and risk profile can be useful if you turn them into your own framework quickly. To pressure test both the upside and the concerns using hard numbers, start by weighing the 2 key rewards and 3 important warning signs.
Looking for more Banco de Sabadell style ideas?
If you stop with Banco de Sabadell, you only see one angle. Casting a wider net with focused screeners can reveal opportunities you would otherwise miss.
- Target resilient balance sheets by scanning a list of solid balance sheet and fundamentals (196 results) that filters for companies pairing financial strength with solid fundamentals.
- Hunt for mispriced quality through a curated 192 high quality undervalued stocks that highlights businesses combining robust cash generation with attractive valuations.
- Build steadier income potential by reviewing a concise 221 dividend fortresses centered on higher yielding stocks with an emphasis on sustainability.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com