


EN
Should Earnings Beat Require Action From Old Second Bancorp (OSBC) Investors?
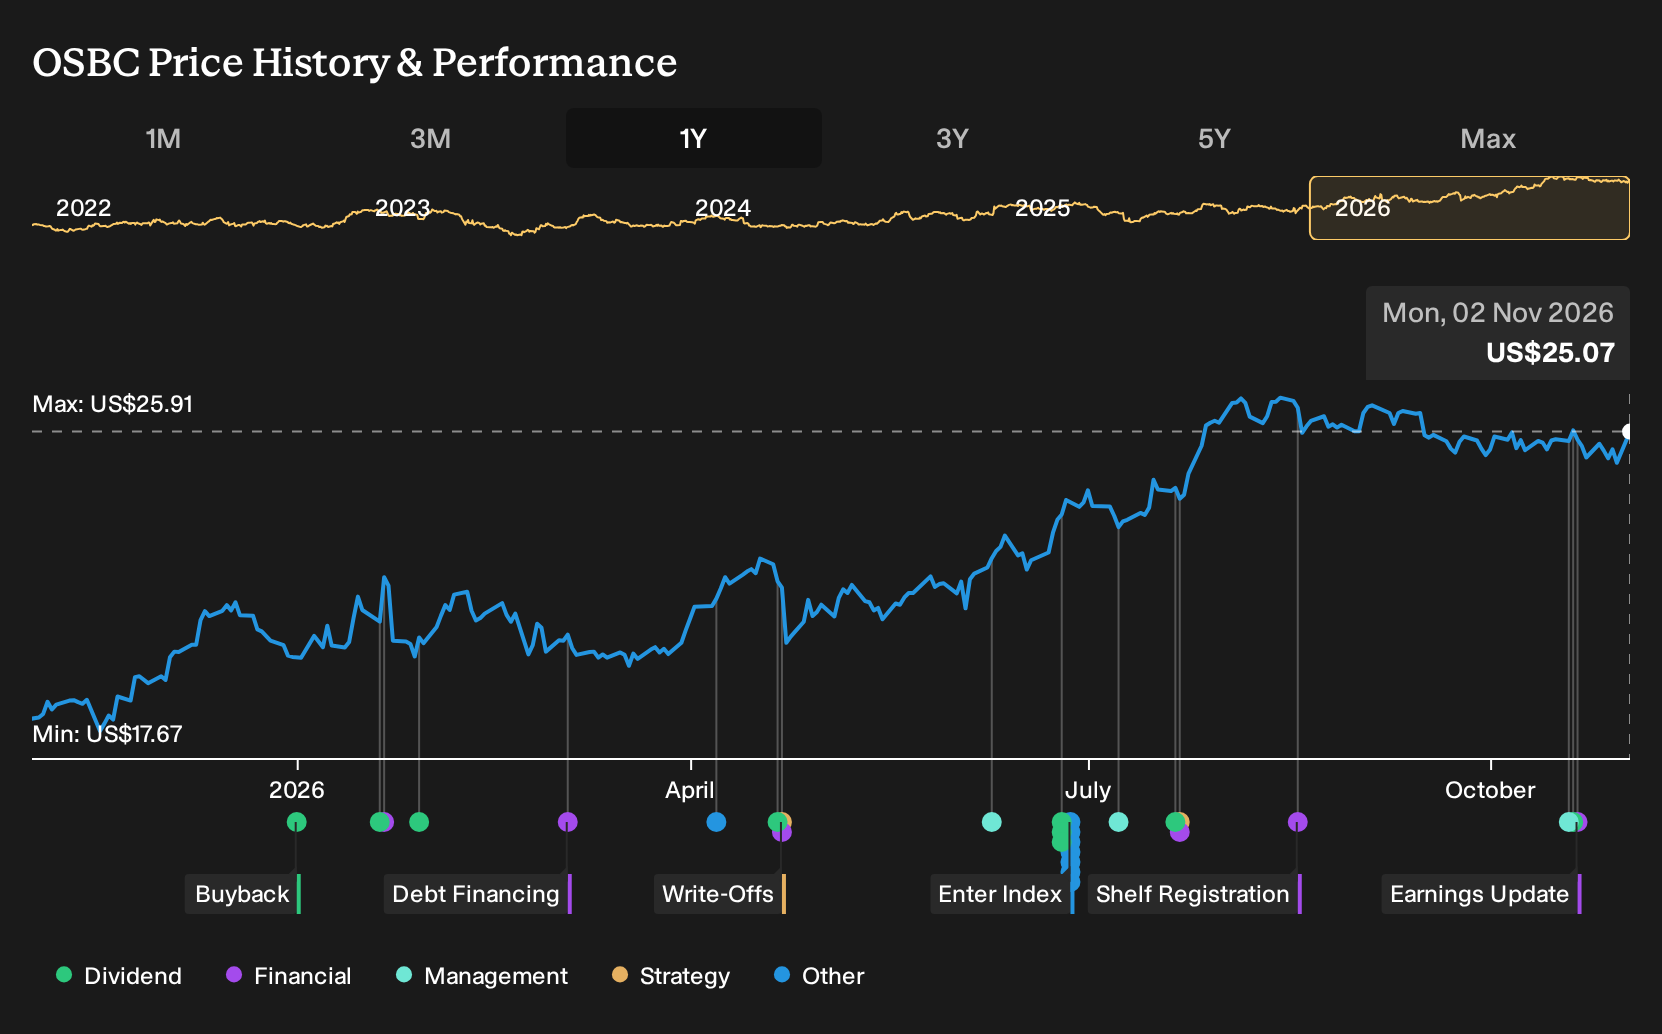
- Old Second Bancorp reported third quarter 2026 results with net interest income of US$84.05 million and net income of US$28.94 million, alongside a completed 3.01% share repurchase tranche and a US$0.08 per share cash dividend declared in October 2026.
- The jump in basic earnings per share from continuing operations to US$0.57, compared with US$0.19 a year earlier, shows how Old Second Bancorp is currently translating its balance sheet mix and capital returns into higher per share profitability.
- We will now look at how Old Second Bancorp's sharp increase in quarterly earnings could influence the existing investment narrative.
Scan for other regional banks that combine earnings momentum with capital returns by reviewing the 34 high quality undervalued stocks alongside Old Second Bancorp's latest quarter.
Old Second Bancorp Investment Narrative Recap
To own Old Second Bancorp, you need to be comfortable with a bank that leans on a high net interest margin and higher yielding specialty lending while still working through elevated credit costs. The sharp move in quarterly net income and earnings per share shows that, at least for now, the business is converting that model into stronger profitability.
The key short term swing factor remains credit quality. Net charge offs around 70 bps, tied to specific C&I, office commercial real estate and powersports loans, still sit in the background as the main risk. The latest earnings beat does not remove that. It just gives more cushion if those loss levels stay sticky.
The share repurchase completed between July and September 2026, covering 1,533,104 shares or 3.01% of the register for US$39.5 million, is the announcement that matters most here. It sits directly on top of the strong third quarter profit print and tightens the link between operating performance and per share outcomes for Old Second Bancorp.
That capital return can amplify any future earnings swings, both positive and negative. If net interest income and specialty lending contribution hold up against competition in Illinois and from digital banks, the smaller share count adds support to per share metrics. If credit issues or softer loan demand bite, the same effect works in reverse and makes execution risk more visible.
What The Analyst Forecasts Assume For Old Second Bancorp
Analysts sketch a future for Old Second Bancorp that leans on modest revenue expansion and a bigger share of each dollar dropping to the bottom line. The projections point to revenue growth of 1.5% a year over the next three years, paired with profit margins rising from 27.1% today to 38.8% in the same period. That mix of slower top line progress and wider margins is what sits behind the earnings path that is being discussed.
On the earnings side, the consensus view ties the story together. Analysts expect net income to move from US$92.4 million today to US$138.4 million by 2029, with earnings per share reaching US$2.65 if current share count shrinkage plays out as forecast. That shift implies an earnings increase of about 50% in absolute dollar terms, with the contribution coming from both higher profitability and an expected 3.41% yearly reduction in shares outstanding over the next three years.
Valuation assumptions round out the picture for Old Second Bancorp. The analyst group is working off a 2029 revenue figure of US$357.0 million and earnings of US$138.4 million, paired with a P/E of 11.4x that is described as roughly in line with the broader US banks industry. A discount rate of around 7.2% to 7.24% underpins the exercise, which is then compared with a current share price of US$24.66 and a consensus target of US$28.00, framed as 11.9% higher.
Old Second Bancorp's narrative projects US$357.0 million revenue and US$138.4 million earnings by 2029. This requires 1.5% yearly revenue growth and an earnings increase of about US$46.0 million from US$92.4 million today.
Uncover why Old Second Bancorp's fair value indicates a 12% potential upside to its current price before the market closes that gap.
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Old Second Bancorp research is our analysis highlighting 2 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Old Second Bancorp. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Old Second Bancorp's overall financial health at a glance.
Looking For More Investment Ideas Beyond Old Second Bancorp?
If Old Second Bancorp has sharpened your focus on earnings quality, capital returns, and balance sheet strength, it can be useful to scan a broader watchlist built around the same themes.
- For investors who want resilient cash flows and conservative financial profiles, start with a curated list of solid balance sheet and fundamentals (24 results) that match those priorities.
- If your goal is to pair quality fundamentals with the chance to find underappreciated opportunities, broaden your search using the 19 high quality undiscovered gems that share similar financial hallmarks.
- For a focus on stability and capital protection, refine your universe toward companies with lower risk scores by checking out a 29 resilient stocks with low risk scores aligned with your own tolerance.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com