


EN
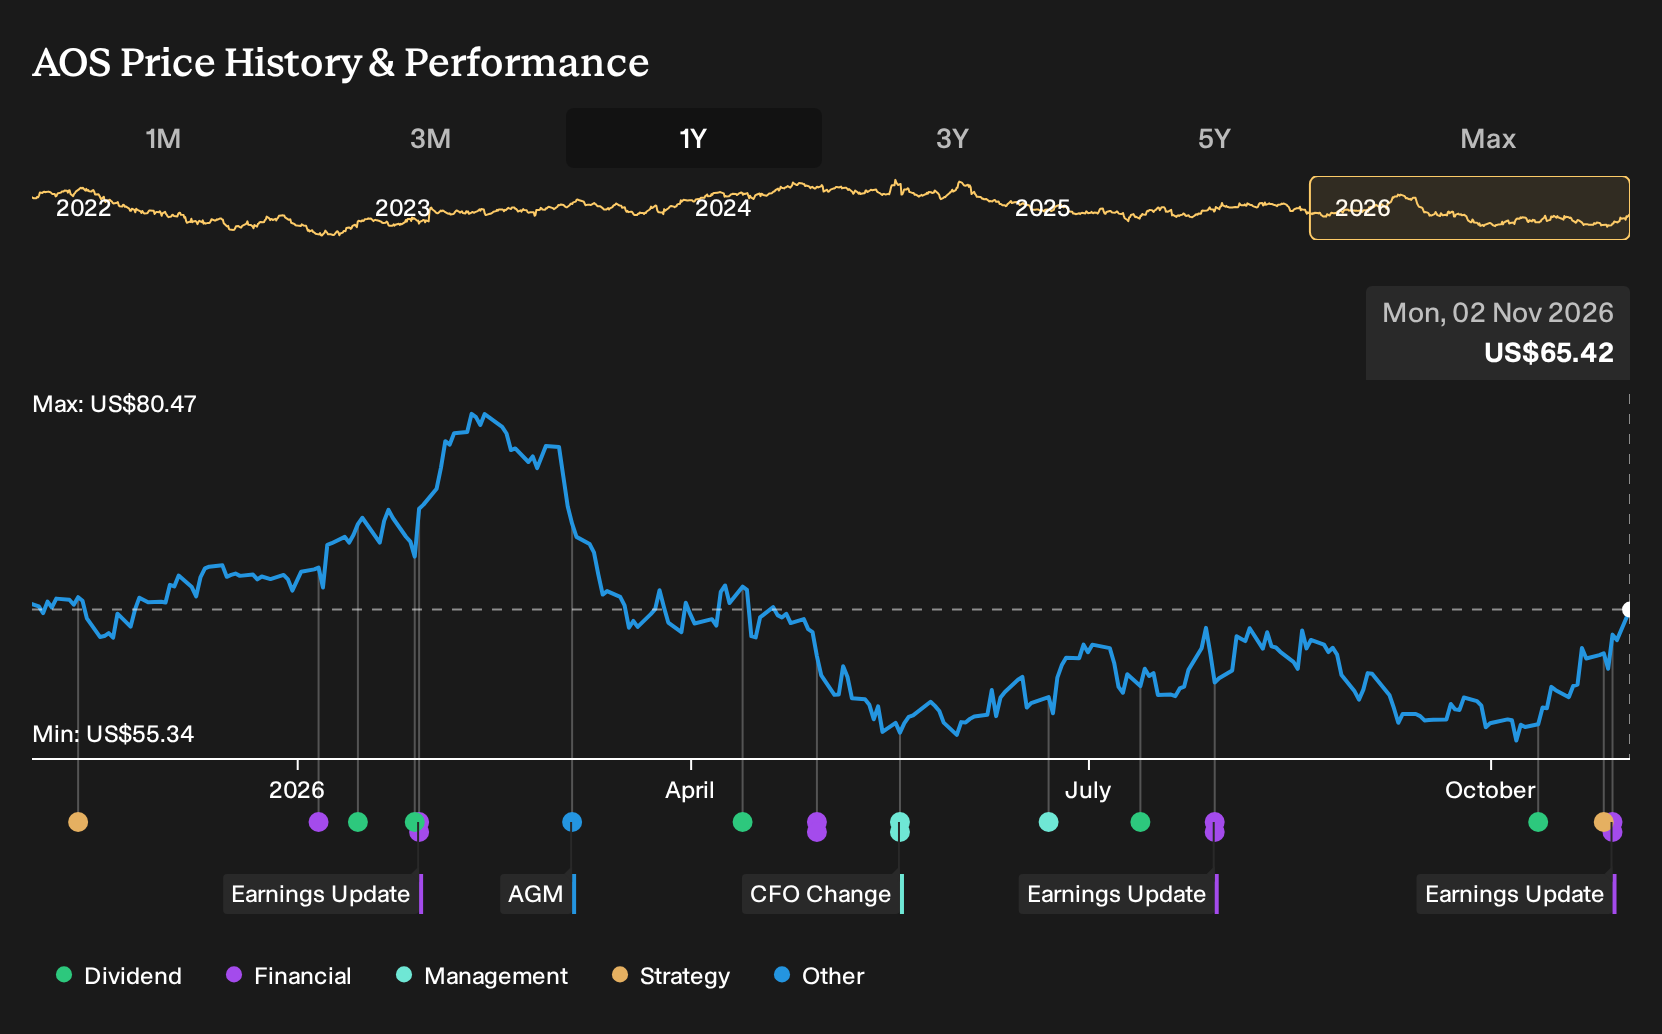
How Guidance Excluding China Will Impact A. O. Smith (AOS) Investors
- A. O. Smith reported third quarter 2026 sales of US$940.5 million and net income of US$126.3 million, and updated its 2026 guidance to US$3,270 million to US$3,290 million in net sales excluding the China business.
- Excluding China from full year guidance highlights how management now frames that operation as non core, which matters for how you judge future earnings quality and capital allocation at A. O. Smith.
- We will now assess how A. O. Smith's decision to exclude its China business from 2026 guidance could reshape the existing investment narrative.
Scan how A. O. Smith’s guidance reset compares with other industrials refocusing on core businesses by checking the hand picked list of solid balance sheet and fundamentals (24 results).
A. O. Smith Investment Narrative Recap
To own A. O. Smith, you need to be comfortable with a steady, utility like story built on water heaters, boilers, and treatment systems, with North America doing most of the heavy lifting. The key short term swing factor remains how well core demand and pricing offset softer conditions, cost inflation, and some recent pressure on net margins.
The move to give 2026 guidance that strips out China, combined with modestly lower third quarter earnings, keeps the focus squarely on execution in North America and the rest of world portfolio. For now the China guidance change mostly cleans up the near term message, rather than creating a new operational catalyst or risk by itself.
The most relevant update is the third quarter 2026 earnings release. Sales for the quarter were US$940.5 million and net income was US$126.3 million, with both quarterly and nine month profit metrics below the prior year. That keeps attention on how A. O. Smith manages costs and mix while demand in some markets is softer.
For an investor watching catalysts, that earnings step down frames the importance of product mix shifts toward higher efficiency and smart offerings, and of ongoing channel work in North America. It also underlines the risk that weaker replacement or construction activity, together with higher input costs, could limit any near term improvement in profitability even as the portfolio is refined.
A. O. Smith's analyst narrative projects US$4.3b in revenue and US$598.0 million in earnings by 2029. This assumes 4.0% yearly revenue growth and an earnings increase of about US$97.7 million from current earnings of US$500.3 million.
Uncover why A. O. Smith's fair value is consistent with its current price.
Exploring Other Perspectives
The most bearish analysts frame A. O. Smith’s China exposure as the key risk for you to watch. Before this guidance shift, that group was only pencilling in about US$4.2b of 2029 revenue and roughly US$571.4 million of earnings, with a lower 15.6x P/E. This updated exclusion of China could push those already cautious narratives to evolve further, so it pays to compare several viewpoints rather than rely on just one set of forecasts.
Explore 4 other A. O. Smith fair value estimates, including one that suggests as much as 16% downside from the current price.
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your A. O. Smith research is our analysis highlighting 4 key rewards that could impact your investment decision.
- See our latest analysis for A. O. Smith. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate A. O. Smith's overall financial health at a glance.
Looking for more investment ideas beyond A. O. Smith?
If this A. O. Smith review has sharpened your thinking and you want to cast the net wider, the Simply Wall St Screener can help you quickly filter for other opportunities that fit your style, risk tolerance, and income needs.
- If capital preservation comes first for you, focus your research on resilient businesses by scanning a curated 29 resilient stocks with low risk scores that may better match a cautious approach.
- If stable income is a priority, streamline your hunt for reliable payers by reviewing a hand picked set of 4 dividend fortresses that combine yield with underlying business strength.
- If you are hunting for overlooked opportunities, widen your watchlist with a focused group of 19 high quality undiscovered gems that many investors may not be tracking yet.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com