


EN
Delta Air Lines Stock: Analyst Estimates & Ratings
With a market cap. of $54.9 billion, Delta Air Lines, Inc. (DAL) is a leading global airline, serving more than 200 million customers annually through a workforce of approximately 100,000 employees and up to 5,500 daily flights to over 300 destinations across six continents. A founding member of the SkyTeam alliance, it operates major domestic and international hubs and has built a reputation for exceptional customer service, innovation, and operational reliability, earning Cirium’s top on-time airline recognition in North America for five consecutive years.
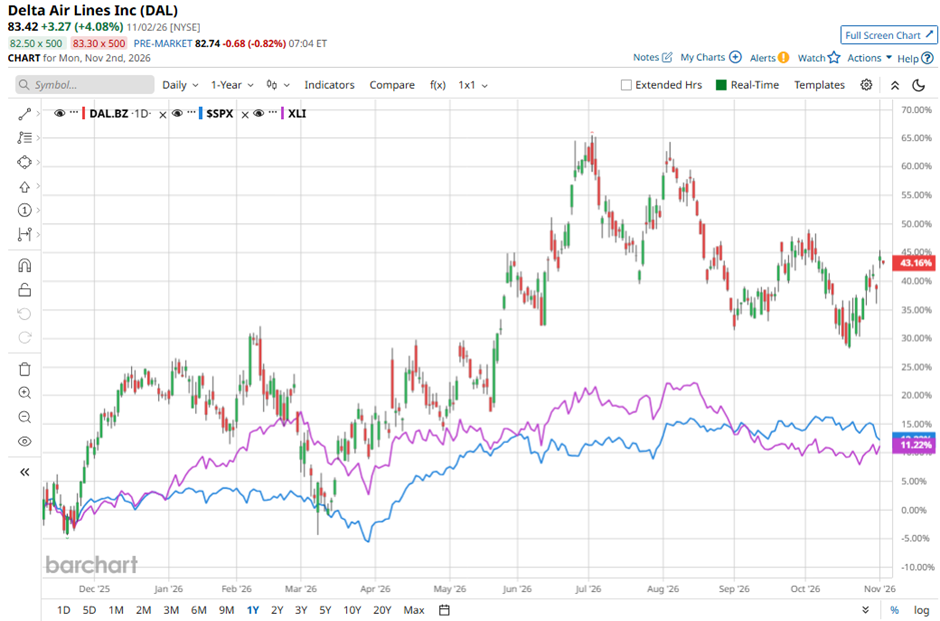
Shares of the Atlanta, Georgia-based company have outperformed the broader market over the past 52 weeks. DAL stock has climbed 45.4% over this time frame, while the broader S&P 500 Index ($SPX) has returned 10.3%. Moreover, shares of the company have increased 20.2% on a YTD basis, compared to SPX’s 10.2% gain.
Focusing more closely, the airline stock has also outpaced the State Street Industrial Select Sector SPDR ETF’s (XLI) 9.5% return over the past 52 weeks.
Delta Air Lines shares rose marginally on Oct. 9 as the company reported record September-quarter 2026 revenue of $17.6 billion, up 16% year-over-year, and adjusted EPS of $1.72, matching the prior-year level despite absorbing more than $500 million in additional fuel costs. Investor confidence was supported by strong travel demand and healthy yields, with premium revenue rising 18%, loyalty revenue increasing 18%, cargo revenue climbing 29%, and MRO revenue growing 28%, while Delta forecast approximately 20% revenue growth in the December quarter.
The company also maintained its full-year 2026 EPS outlook of $5.10 - $5.60, projected approximately $2.5 billion in free cash flow, and planned to repay more than $2 billion in debt, although higher fuel expenses and a 7.3% increase in non-fuel unit costs limited the positive reaction.
For the fiscal year ending in December 2026, analysts expect Delta Air Lines’ adjusted EPS to decline 8.3% year-over-year to $5.34. The company's earnings surprise history is mixed. It topped the consensus estimates in three of the last four quarters while missing on another occasion.
Among the 24 analysts covering the stock, the consensus rating is a “Strong Buy.” That’s based on 21 “Strong Buy” ratings, two “Moderate Buys,” and one “Strong Sell.”
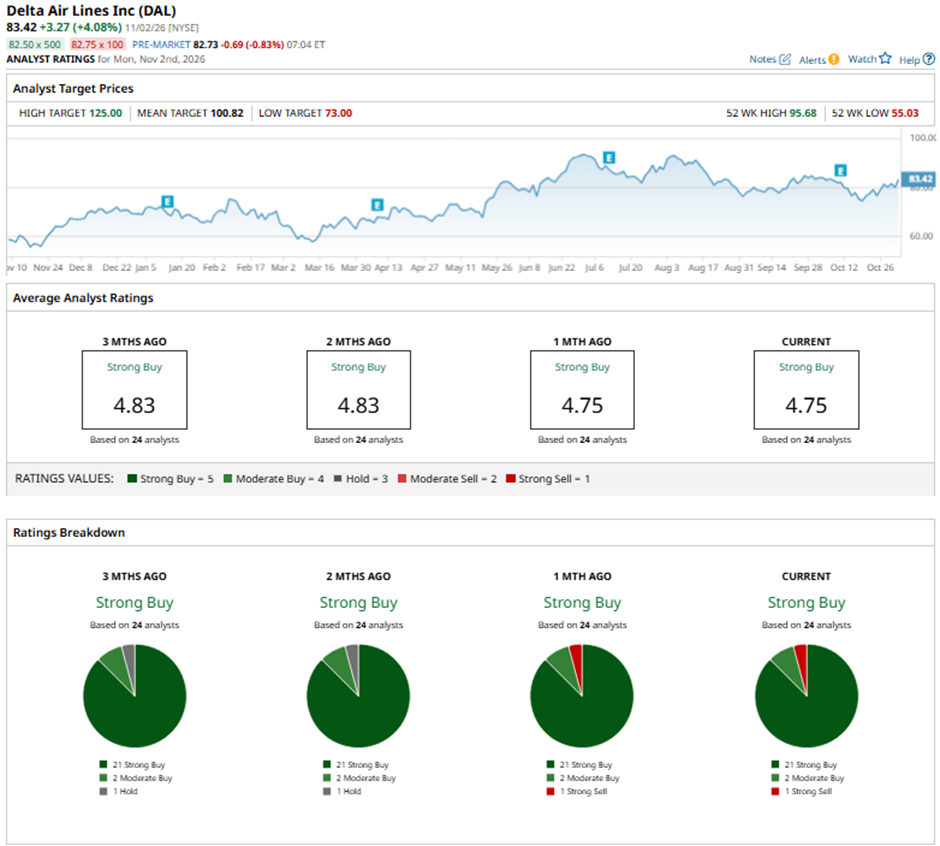
This configuration has remained unchanged over the past three months.
On Oct. 12, BMO Capital raised its price target on Delta Air Lines to $105, maintaining an "Outperform” rating.
The mean price target of $100.82 represents a 20.9% premium to DAL’s current price levels. The Street-high price target of $125 suggests a 49.8% potential upside.
On the date of publication, Sohini Mondal did not directly have a position in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.