


EN
Why ServiceNow Stock Is a Buy Now
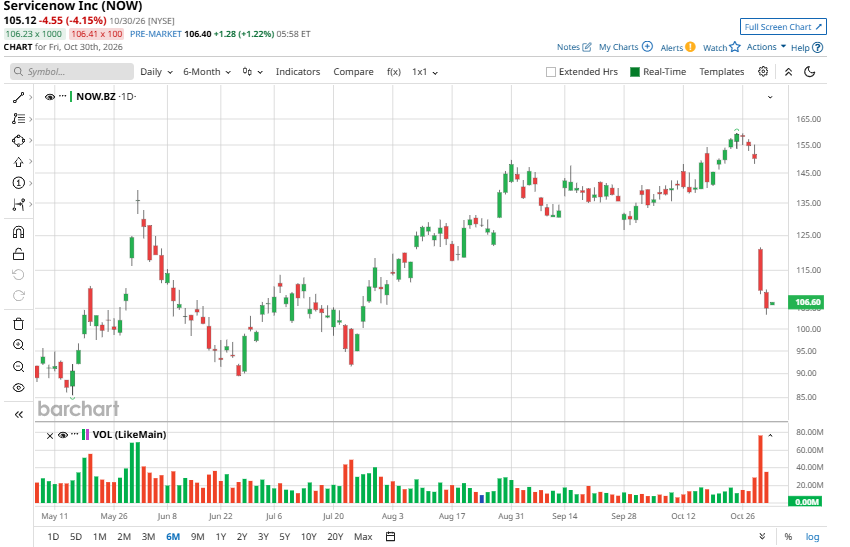
ServiceNow (NOW) stock experienced a sharp correction, declining approximately 34% over the past week following the release of the company’s third-quarter results. Although the company delivered a solid quarterly performance, investor sentiment weakened after its fourth-quarter outlook came in below expectations.
A key concern was the anticipated slowdown in current remaining performance obligations (cRPO). ServiceNow projected fourth-quarter cRPO growth of 18.5%, suggesting a sequential moderation from the 20.5% year-over-year growth reported in Q3 2026.
This deceleration in CRPO growth rate has raised concerns about the sustainability of ServiceNow’s growth trajectory. Investor apprehension has intensified amid broader market uncertainty surrounding generative artificial intelligence (AI) and its potential to disrupt traditional software-as-a-service (SaaS) business models. The possibility that increasingly capable AI models could reduce demand for conventional enterprise software has placed additional pressure on software valuations.
However, the negative market reaction is overlooking ServiceNow’s ability to monetize the technology. Its AI business is growing rapidly, supporting growth, and strengthening customer engagement.
While the projected cRPO moderation warrants caution, the sharp decline in its share price and its growing AI business support the investment case.
ServiceNow’s Outlook Remains Strong Amid Accelerating AI Adoption
ServiceNow’s growth prospects remain compelling, supported by an expanding customer base, increasing contract values, broader adoption of its integrated workflow platform, and accelerating demand for AI-driven solutions.
In Q3, subscription revenue reached $3.99 billion, up 20.5% year over year. RPO increased 22.5% in constant currency to $29.7 billion. Demand was broad-based across the portfolio. Meanwhile, customer retention and expansion remained strong.
ServiceNow maintained a strong renewal rate of 98%, reflecting the critical role its solutions play in customers’ daily operations. The company ended the quarter with 680 customers generating more than $5 million in ACV, while 31 additional customers crossed the $20 million ACV threshold over the past year. Furthermore, 19 of its 20 largest transactions included at least six products, demonstrating increasing platform penetration. This cross-selling opportunity supports higher customer lifetime value, strengthens switching costs, and creates a more predictable recurring revenue base.
AI is emerging as a significant growth catalyst for the company. AI-related net new ACV expanded 65% year over year in Q3, prompting management to raise its 2026 AI ACV target to $1.7 billion, up from the initial $1 billion objective. The number of AI transactions exceeding $1 million increased 4.5 times, while deals involving five or more AI products grew more than 8.5 times. Importantly, adoption is extending beyond established IT workflows into security, asset management, CRM, HR, and portfolio management, indicating that enterprise AI demand is broadening across business functions.
Overall, ServiceNow appears well positioned to benefit from the structural shift toward enterprise AI adoption. Its established customer relationships, expanding product ecosystem, high renewal rates, and growing AI opportunity provide multiple avenues for sustained growth.
Buy the Pullback in ServiceNow Stock
ServiceNow’s growth story remains compelling, despite some near-term concerns about a slowdown in cRPO growth. The company continues to benefit from strong customer retention, broader adoption of its enterprise platform, and increasing demand for AI-powered solutions. These factors should help sustain revenue growth.
Another positive is that ServiceNow is finding ways to capitalize on the AI opportunity while keeping capital spending under control. Lower CapEx should support stronger free cash flow generation and improve margins.
For fiscal 2026, ServiceNow raised its subscription revenue forecast by $15 million at the midpoint, implying approximately 21% year-over-year growth on a constant-currency basis. The company also increased its full-year free cash flow margin target by 100 basis points, from 35% to 36%, reflecting lower-than-expected capital expenditure requirements.
Overall, ServiceNow’s strong recurring revenue base, expanding AI opportunities, and improving cash flow profile continue to support its long-term prospects. The recent sell-off has brought the stock's valuation to more attractive levels, creating a buying opportunity.
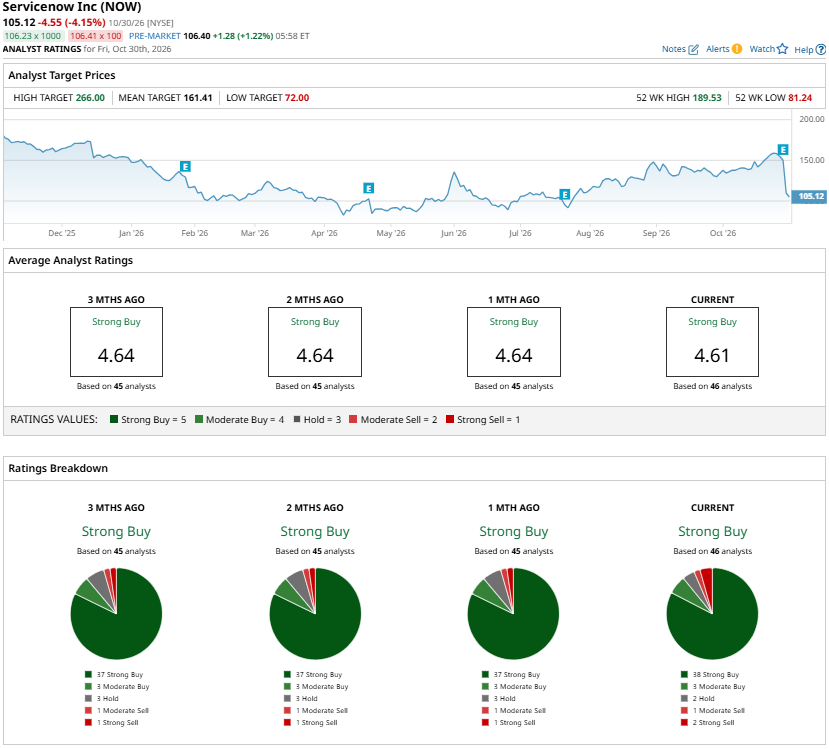
Wall Street remains optimistic about the company's outlook, with analysts maintaining a “Strong Buy” consensus rating on NOW stock.
On the date of publication, Amit Singh did not directly have a position in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.