


EN
YETI Holdings (YETI) On Split Valuation Calls Is The Premium Earned Or Priced In
Debate around YETI Holdings (YETI) has sharpened after fresh coverage highlighted a split view on its valuation. Some commentary points to productivity savings, while others focus on inflation driven cost pressure and premium P/E levels.
Recent trading has tilted in YETI Holdings' favor, with a 1 month share price return of 11.13% and a 7 day move of 4.25%, even though the 3 month share price performance is still down 12.23%. That rebound sits alongside a 1 year total shareholder return of 35.42%, which contrasts sharply with a 5 year total shareholder return that is down 56.71%. This hints that recent enthusiasm is rebuilding after a much tougher longer term journey, while investors debate whether the current premium valuation is justified by earnings quality and productivity gains.
Spot opportunities beyond YETI Holdings by scanning our hand picked 34 high quality undervalued stocks, which may offer a similar mix of brand strength and debated valuation.After a sharp 1 month bounce, YETI Holdings still trades below both intrinsic fair value estimates and analyst targets. Is that discount caution that fits the 5 year record, or mispricing that the recent reset already reflects?
Most Popular Narrative: 17.3% Undervalued
At a last close of $45.42 against a narrative fair value of $54.93, YETI Holdings is framed as undervalued while the market debates whether mid single digit growth and premium branding deserve that gap.
The structured effort to deepen multi product ownership, where moving 10% of U.S. owners up one quartile and reaching 10% of look alike non owner households is calculated as about US$2.2b of incremental opportunity, provides a clear path for higher revenue and supports the long term earnings profile.
See why 13 investors see YETI Holdings as 17% undervalued.
Result: Fair Value of $54.93 (UNDERVALUED)
Still, rising input costs and any disappointment compared with the mid to high single digit growth narrative could quickly challenge the idea that YETI Holdings is mispriced.
Find out about the key risks to this YETI Holdings narrative.
Another View: What YETI’s P/E Is Signalling
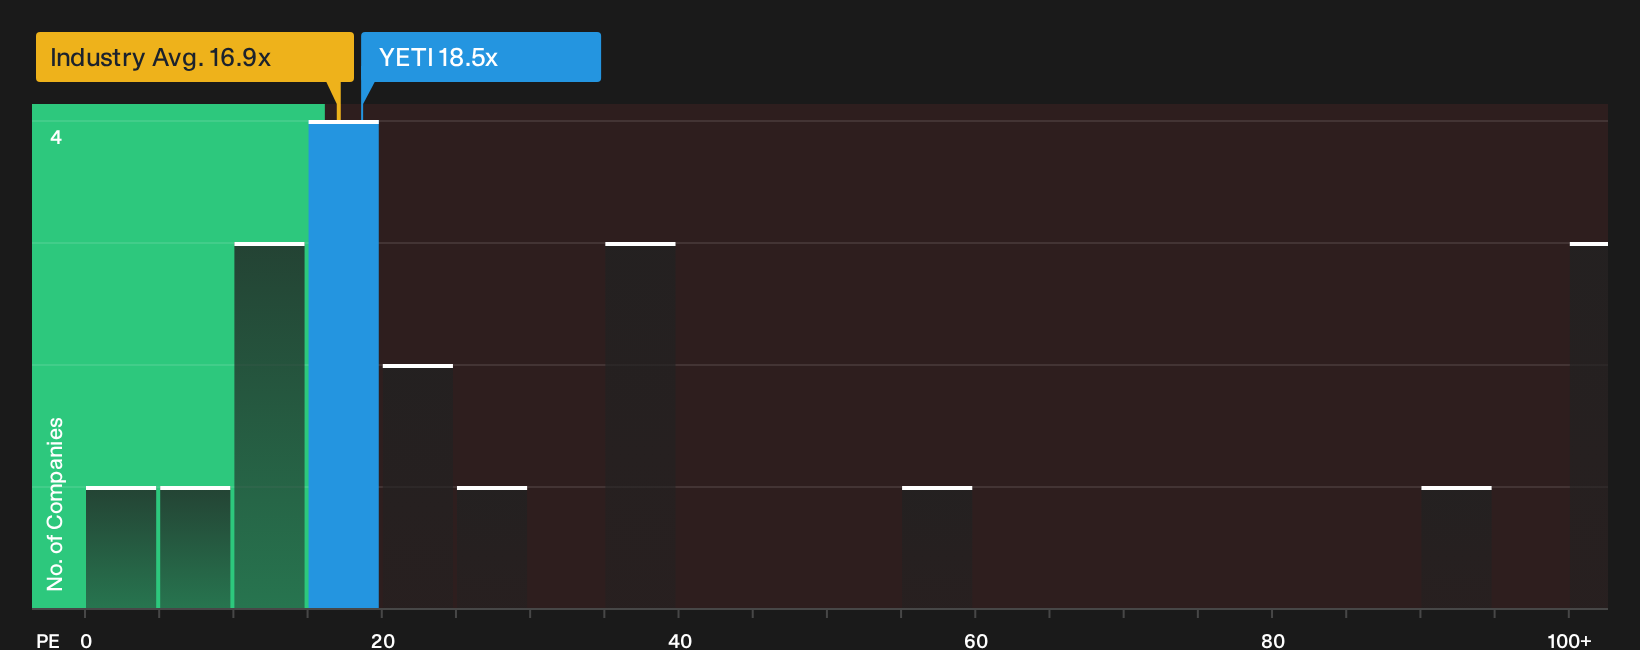
There is a twist when the valuation shifts from fair value models to the plain P/E ratio. YETI Holdings trades on 18.5x earnings, above the 16.5x fair ratio estimate and the 16.9x Global Leisure average, yet below peers at 23.7x. That mix points to both optimism and compression risk if sentiment cools.
For anyone weighing whether that premium is warranted by earnings quality and return on equity, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Balanced or stretched, the YETI Holdings story will ultimately be decided by your own reading of the numbers. Move fast and review both the market debate and the 3 key rewards.
Looking for more investment ideas beyond YETI Holdings?
If you stop with YETI Holdings, you only see one angle. Broaden your watchlist and you may spot opportunities that better match your goals and risk comfort.
- Target potential mispricing by scanning a curated pool of quality stocks that look overlooked on fundamentals through the 19 high quality undiscovered gems.
- Strengthen portfolio resilience by focusing on companies with robust finances and healthy leverage using the list of solid balance sheet and fundamentals (24 results).
- Dial down volatility by concentrating on businesses with lower risk scores and more stable profiles inside the 29 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com