


EN
Earnings Beat Might Change The Case For Investing In Sandvik Stock (OM:SAND)
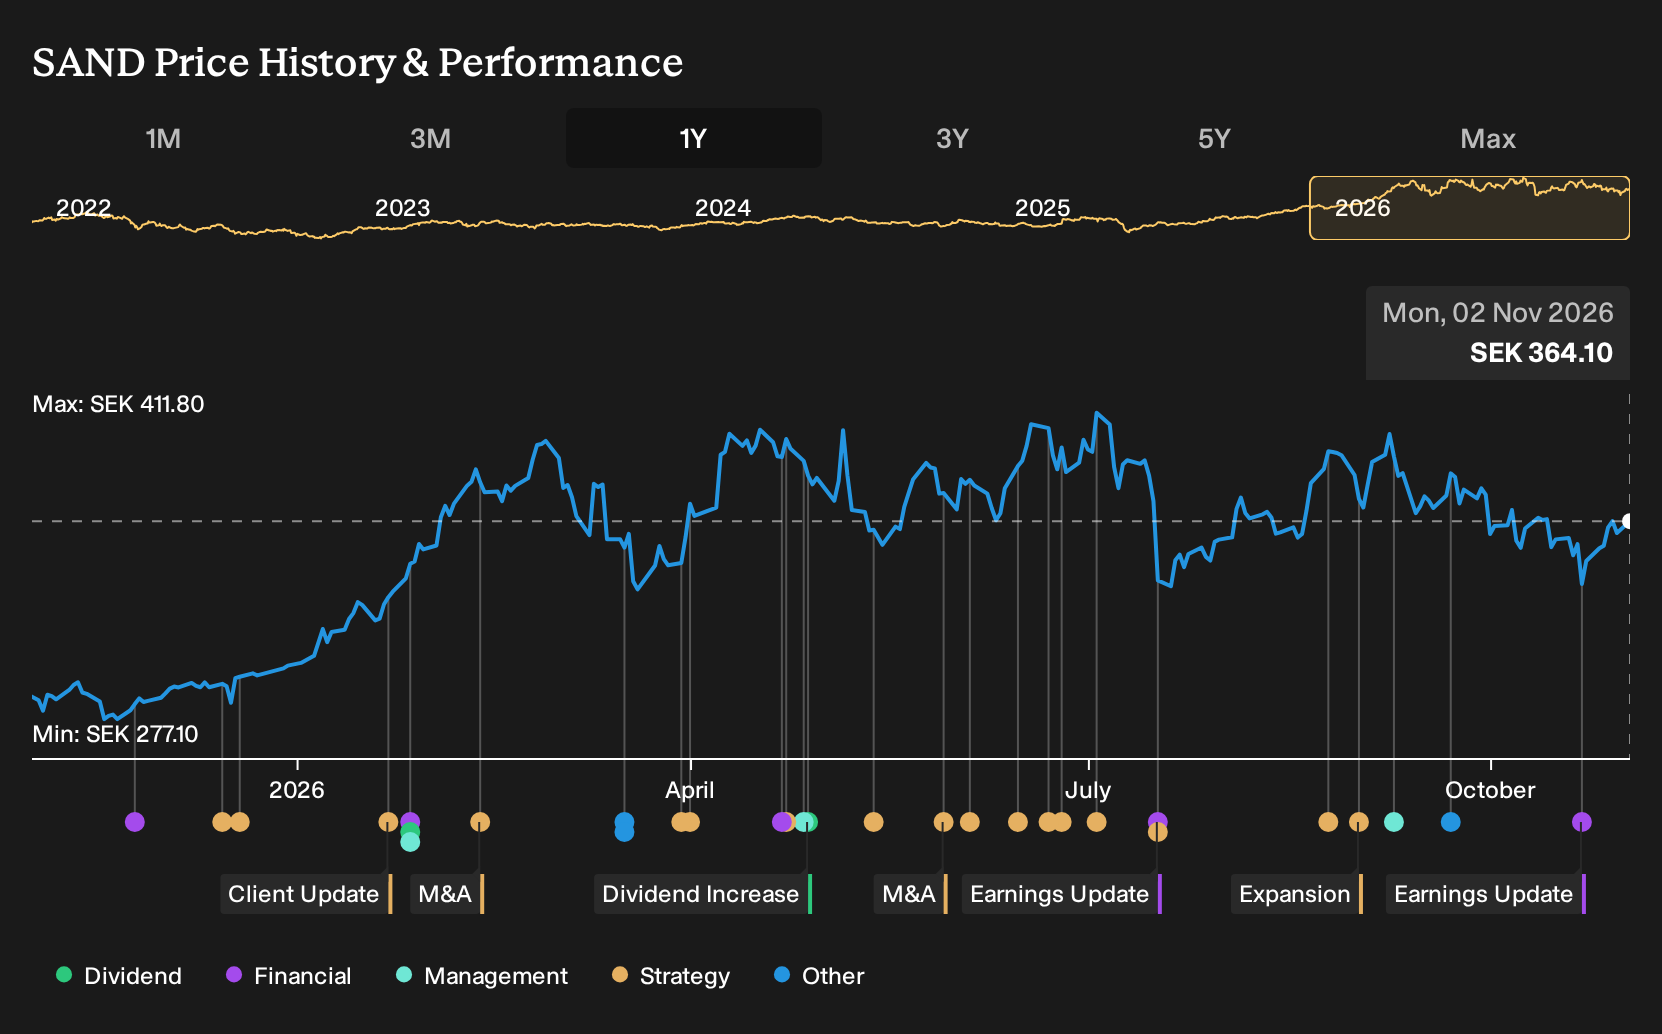
- Sandvik reported third quarter 2026 sales of SEK 37,728 million and net income of SEK 5,770 million, with basic earnings per share from continuing operations of SEK 4.6.
- For the first nine months of 2026, Sandvik recorded SEK 105,164 million in sales and SEK 14,883 million in net income, highlighting earnings power across the wider period rather than a single quarter.
- We will now look at how Sandvik's third quarter earnings, particularly the higher net income, interact with the existing investment narrative.
Scan how Sandvik's Q3 momentum compares with peers and see which industrial players are posting similar earnings power with the hand picked 192 high quality undervalued stocks.
Sandvik Investment Narrative Recap
To own Sandvik, you need to be comfortable with a story where mining, automation and digital tools carry more weight than slower areas like general engineering and automotive. Q3 and nine month earnings show that equipment, aftermarket and software driven activities together can support SEK 14,883 million of profit, even while some cyclical end markets stay soft.
In the near term, the key swing factor is whether the stronger Mining and digital mix can offset pressure in Cutting Tools, Infrastructure and Rock Processing margins. The latest quarter confirms earnings power is holding up against that risk, rather than radically changing the near term catalyst or the main operational concern.
With no fresh corporate actions announced alongside these results, the most relevant update for Sandvik is still the Q3 and nine month report itself. Sales of SEK 37,728 million in the quarter and SEK 105,164 million year to date, plus SEK 11.86 of basic EPS from continuing operations so far in 2026, provide a clearer base to judge execution.
Those numbers matter because they sit next to the existing catalysts already in focus in mining automation, digital tools and Rock Processing improvement. When you think about risks such as weaker general engineering demand or structurally lower margins in some segments, this latest earnings run rate is what you would probably stress test against your own scenarios.
Sandvik's analyst narrative points to revenues of SEK 175.6b and earnings of SEK 26.7b by 2029, based on assumed revenue growth of 10.8% per year and an earnings increase of SEK 9.8b from SEK 16.9b today.
Uncover how Sandvik's fair value indicates a 7% potential upside to its current price. This could narrow quickly as Sandvik's earnings story beds in.
Exploring Other Perspectives
One alternate view focuses on Sandvik’s mining aftermarket as a potential weak spot. The most cautious analysts were working off revenue of about SEK 164.5b and earnings of SEK 24.2b by 2029 before these Q3 figures. That is a much more muted story. Use this earnings release to consider where you personally sit between those narratives.
Explore 4 other Sandvik fair value estimates, including one that suggests as much as 18% downside from the current price.
Form Your Own Verdict
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Sandvik research is our analysis highlighting 2 key rewards that could impact your investment decision.
- See our latest analysis for Sandvik. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Sandvik's overall financial health at a glance.
Looking For More Investment Ideas Beyond Sandvik?
Once you have a view on Sandvik, it often helps to scan a wider watchlist so you can compare quality, resilience and income potential across other businesses.
- If you want income to do more of the heavy lifting in your portfolio, check out companies offering 221 dividend fortresses that go beyond headline yield and focus on durability.
- For investors who care most about balance sheet strength and fundamentals, filter for firms in the list of solid balance sheet and fundamentals (196 results) to see which businesses pair financial resilience with disciplined capital use.
- If you are hunting for ideas that sit off the beaten track, the 603 high quality undiscovered gems can help surface underfollowed companies with solid underlying metrics that might warrant a closer look.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com