


EN
Is Steven Madden (SHOO) Undervalued After UBS Backed Stronger Q3 And Full Year Outlook?
Why UBS is Watching Steven Madden Ahead of Q3 Results
UBS Securities recently highlighted Steven Madden (SHOO) after suggesting the footwear and accessories group could outperform third quarter earnings expectations and lift full year guidance, supported by momentum in its Steve Madden and Kurt Geiger brands.
Recent trading tells a mixed story for Steven Madden. The share price is at US$43.53, with a 7 day share price return of 1.8% but a 90 day share price return down 10.9%. The 1 year total shareholder return of 35.5% points to stronger momentum over a longer stretch as investors weigh UBS’s upbeat earnings view against earlier weakness.
Scan how Steven Madden compares with other footwear and consumer brands on our hand picked 34 high quality undervalued stocks that blend quality fundamentals with potential mispricing.
Given Steven Madden’s pullback over three months but strong one year return, the real tension now is simple. Does the current valuation still skew the risk reward toward buyers as earnings expectations rise?
Most Popular Narrative: 17% Undervalued
Against the last close at $43.53, the most followed narrative pins Steven Madden’s fair value at $52.40, implying the market price sits below the earnings power that narrative assumes.
Strong double digit digital growth in direct to consumer for Steve Madden and Kurt Geiger, with global DTC revenue rising 30.6% in the latest quarter and continued increases in marketing spend to about 5.3% to 5.4% of revenue, supports a mix shift toward higher margin channels that can lift gross margin and earnings.
See why 3 investors see Steven Madden as 17% undervalued.
Result: Fair Value of $52.40 (UNDERVALUED)
Still, the bullish Steven Madden story meets real friction if tariff costs rise beyond management’s assumptions, or if private label weakness drags on wholesale momentum.
Find out about the key risks to this Steven Madden narrative.
Another Lens On Steven Madden’s Valuation
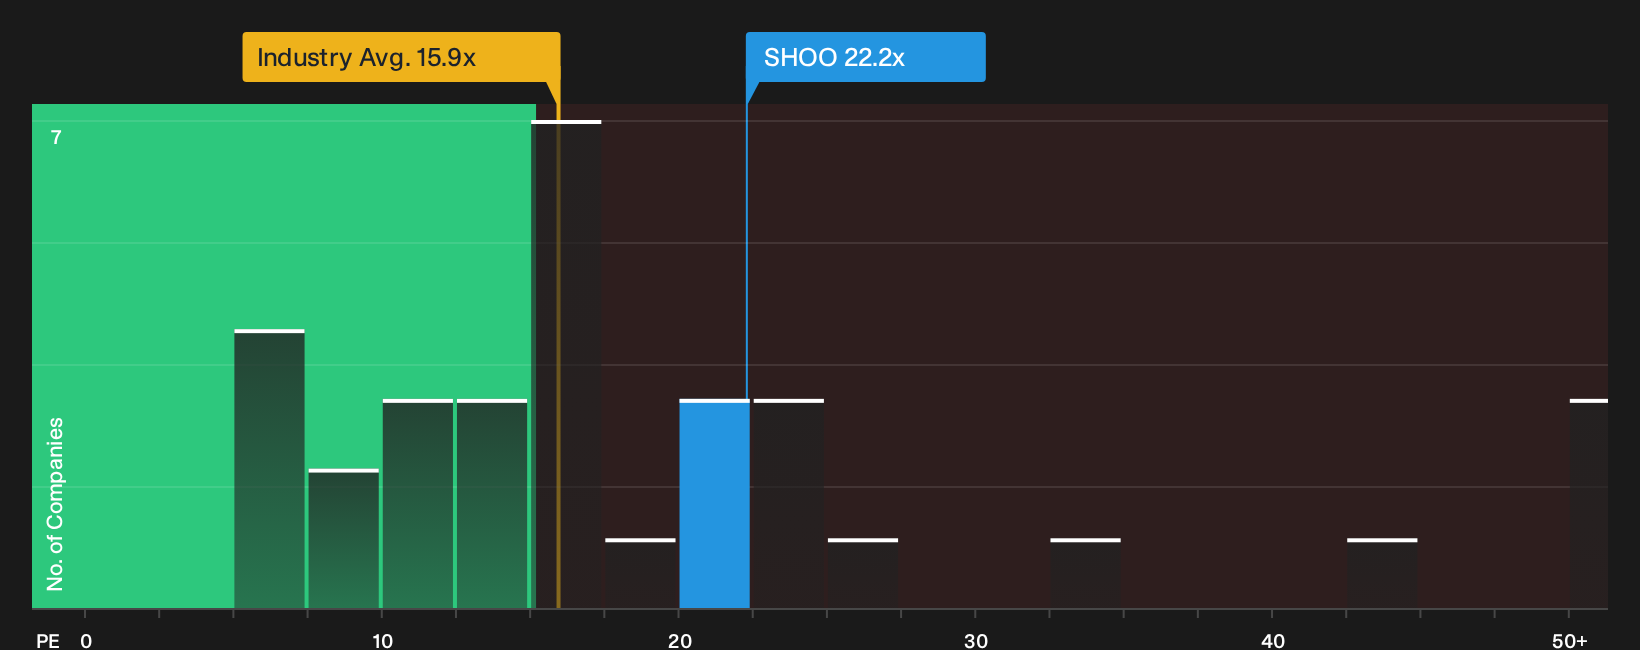
The first narrative leans on earnings power and a fair value of $52.40, yet on simple pricing Steven Madden looks anything but cheap. The stock trades on a P/E of 22.2x compared with 15.9x for the US Luxury industry and 13.7x across peers, while the fair ratio is 22.5x. That narrow gap between today’s multiple and the fair ratio points to limited room for error if growth or margins disappoint. Investors may want to consider how comfortable they are paying a premium tag for what is framed as an undervalued story.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals or early opportunity, either way the balance of risks and potential rewards around Steven Madden is now on you to interpret quickly. Start by weighing the 3 key rewards and 2 important warning signs.
Looking For More Investment Ideas Beyond Steven Madden?
Steven Madden might be on your radar today, but your next strong idea could be hiding in plain sight if you only look a little wider.
Use the Simply Wall Street Screener to quickly surface fresh opportunities that match your risk tolerance and income goals before others move first.
- Target resilient balance sheets and steady fundamentals by scanning our list of solid balance sheet and fundamentals (24 results).
- Hunt for potential mispricing by reviewing the 19 high quality undiscovered gems that combine quality metrics with limited market attention.
- Secure potential income streams by checking the 4 dividend fortresses built around higher yielding, income focused candidates.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com