


EN
Vita Coco Company (COCO) Lifts Guidance After Earnings Beat As Undervalued View Holds
Vita Coco earnings and guidance shift investor attention
Vita Coco Company (COCO) just put fresh numbers on the table, with third quarter sales of US$243.83 million and net income of US$35.02 million, alongside higher full year 2026 net sales guidance.
The earnings beat and higher 2026 guidance arrived after a mixed stretch for Vita Coco Company, with the share price roughly flat over the past quarter but still up 8.89% year to date. The 1 year total shareholder return of 42.60% and 3 year total shareholder return of 101.28% point to strong longer term momentum and shifting expectations around its growth profile.
Fresh catalysts keep feeding that story, from the October earnings release and guidance raise to new Vita Coco Kids products at select Walmart stores and a recent Homesick candle collaboration that keeps the brand in front of consumers.
Scan for other beverage and consumer brands showing similar momentum and guidance upgrades with our curated list of 19 high quality undiscovered gems.
After a sharp reset in expectations and a strong year for Vita Coco, the real tension now sits in the valuation. Is the meaningful upside still ahead, or has most of it already played out in the share price?
Most Popular Narrative: 26% Undervalued
Against the last close of $58.21, the most followed narrative anchors Vita Coco Company at a fair value of $78.60, which frames the current share price as meaningfully below that central estimate while still acknowledging execution risk and high expectations already baked in.
The main factor that has to go right is that Vita Coco Company continues to scale international and private label volumes while managing higher packaging, energy and freight costs without eroding the mid teens net sales growth and high teens adjusted EBITDA margin framework that management targets.
The current valuation, with research summaries citing P/E multiples around 49x to 58x against lower fair value estimates, even as some discounted cash flow work indicates intrinsic value upside, implies that Vita Coco Company shares already reflect strong execution and leave limited room for disappointment.
See why 25 investors see Vita Coco Company as 26% undervalued.
Result: Fair Value of $78.60 (UNDERVALUED)
Still, Vita Coco investors face real swing factors if high P/E expectations collide with slower category growth, or if freight and packaging costs tighten profit margins again.
Find out about the key risks to this Vita Coco Company narrative.
Another View: Vita Coco through a multiples lens
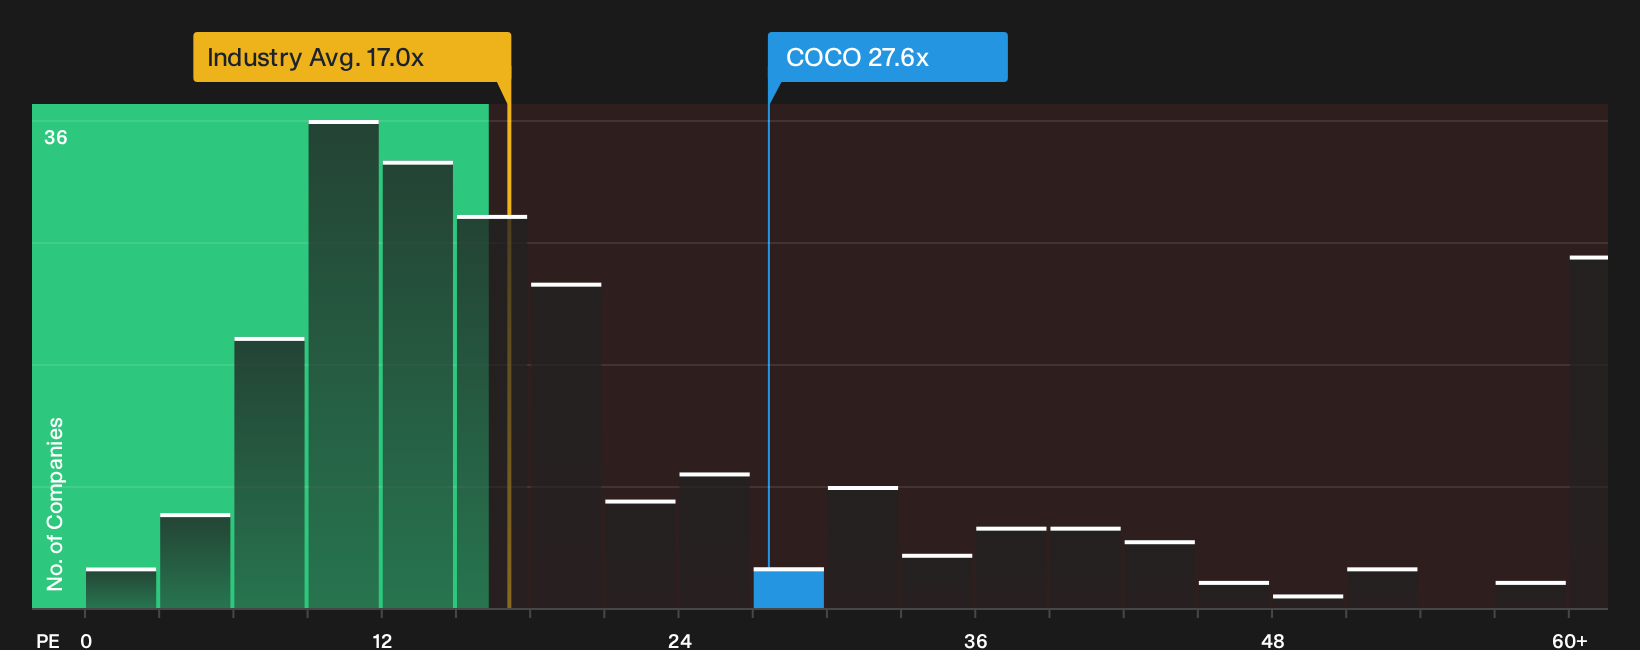
There is a catch to the Vita Coco Company undervaluation story. The stock trades on a P/E of 27.6x, while the global beverage group sits nearer 17x and the fair ratio sits at 17.7x. This signals that investors are already paying up and taking more valuation risk for growth and quality.
That premium is less extreme when compared with closer peers at 57.1x P/E. However, the gap versus both the industry and the fair ratio raises a simple question for holders and potential buyers: How comfortable are you paying above what the market could move toward if sentiment cools?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If this mix of enthusiasm and caution around Vita Coco Company resonates, do not sit on the sidelines and allow others to set the narrative for you. Start by weighing the upside signals in the 4 key rewards.
Looking for more investment ideas beyond Vita Coco?
Do not let your research stop with Vita Coco Company. Use the Simply Wall St screener to line up your next watchlist candidates and stay ahead of the herd.
- Target steadier paths by reviewing companies with stronger fundamentals and balance sheets through the list of solid balance sheet and fundamentals (24 results).
- Hunt for potential mispricing by scanning the 34 high quality undervalued stocks that combine stronger cash flows with cleaner balance sheets.
- Shift focus toward capital preservation by filtering for 29 resilient stocks with low risk scores that score well on resilience and lower risk profiles.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com