


EN
US stock outlook | The three major stock index futures had mixed ups and downs, and the US midterm elections weakened after officially voting on Apple and Palantir stock performance today
Pre-market market trends
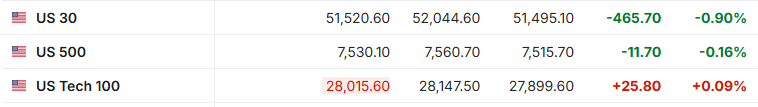
1. Before the US stock market on November 3 (Tuesday), futures for the three major US stock indexes had mixed ups and downs. As of press release, Dow futures were down 0.90%, S&P 500 futures were down 0.16%, and NASDAQ futures were up 0.09%.
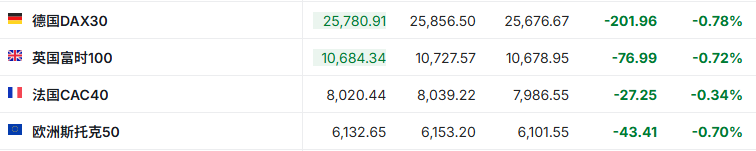
2. As of press release, the German DAX index fell 0.78%, the UK FTSE 100 index fell 0.72%, the French CAC40 index fell 0.34%, and the European Stoxx 50 index fell 0.70%.
3. As of press release, WTI crude oil rose 2.23% to $98.61 per barrel; Brent crude rose 1.71% to $106.56 per barrel.

Market news
The US midterm elections were officially voted on today, and the power pattern may be changed. According to reports, voting officially began in the US midterm elections on November 3, local time. All 435 seats in the House of Representatives, about one-third of the Senate seats, and multiple governor positions will be re-elected. The results will determine the congressional power pattern for the next two years and influence the Trump administration's administration space. As of October 31, a record 50 million people had voted early; pre-election polls showed that the Democratic Party is expected to take back the House of Representatives, competition for the Senate is tight, and the cost of living is viewed as the voters' primary concern. Risk aversion heated up before the election. Analysts believe that the post-election results were clear or prompted some exit funds to return to risky assets.
The Reserve Bank of Australia raised interest rates by 25 basis points to 4.85%, and the end of global austerity continued. At 11:30 on Tuesday, the Reserve Bank of Australia announced its interest rate decision, raising the November cash interest rate from 4.6% to 4.85%, continuing its austerity stance against the backdrop of unresolved inflationary stickiness. This is the latest rate hike in major developed economies, which echoes the market's pricing of the Federal Reserve's continued interest rate hike in December. Despite a decline in US inflation, pressure on core services and wages remains, and the “higher for longer” tone remains unchanged, putting continued pressure on equity valuations, especially long-term growth stocks.
PIMCO: AI funding may be “excessive.” Emmanuel Roman, CEO of Pacific Investment Management Corporation (PIMCO), said that in the next five years, the scale of AI-related financing may reach about 10 trillion US dollars, which may eventually exceed a reasonable level. Roman estimates that in the next five years, the artificial intelligence industry may add about 2 trillion US dollars in financing requirements every year to support capital expenditure. By contrast, the US bond market is about $12 trillion.
Goldman Sachs has drastically raised global data center capacity and predicts that capital expenditure over the next 5 years may reach 8.5 trillion US dollars. Goldman Sachs said it has updated its global data center capacity forecast based on the latest data from the 451 Research database. Currently, it is estimated that by 2030, the global data center supply will reach 273 GW (previously the forecast was 217 GW at the time of the last update in July 2026), which means that 170 GW of capacity will be added after 2025, and the net additional capacity in 2026, 2027, and 2028 will be 25 GW, 32 GW, and 35 GW, respectively. Goldman Sachs anticipates that the net increase in data center capacity will not slow down in the medium term. According to empirical estimates of investing 50 billion US dollars per GW, this additional capacity of 170 GW means that capital expenditure will reach 8.5 trillion US dollars over the next 5 years. But at the same time, Goldman Sachs also noticed that IT infrastructure costs continue to face upward pressure.
IEA: The war with Iran may have caused the biggest annual decline in global LNG supply in history. The IEA predicts that global LNG supply will drop 3% this year, a reduction of nearly 20 billion cubic meters. The blockage of shipping in the Strait of Hormuz and Iran's attacks on critical infrastructure in the region have drastically curtailed exports from Qatar and the UAE. The IEA expects that trade flows through Hormuz will continue to be severely disrupted until at least the end of this year. Increased production in other regions mitigated supply shocks to a certain extent. The commissioning of new projects in North America and Africa, as well as an increase in natural gas supply from existing LNG plants in Africa, Asia, and Russia, contributed to a 14% increase in production outside the Persian Gulf from March to October, making up for about two-thirds of the Persian Gulf supply loss. However, according to the IEA, global LNG production still declined by about 6% during the war.
Is Iran involved in the conflict between Saudi Arabia and the Houthis? Iran says it is holding talks with Saudi Arabia. As the exchange of fire between Saudi Arabia and the Houthis continues to escalate, Iranian Foreign Minister Alagzi said that we are continuing our dialogue with Saudi Arabia. Our goal is to reach a new regional security arrangement led by the regional countries themselves, away from any foreign military presence. Recently, senior officials from Saudi Arabia, Turkey, and Pakistan from the three countries of the “Mecca Defense Agreement” visited Tehran and held meetings with Iran. This is the first time since August this year that Iran has held high-level contacts with these three countries.
Individual stock news
The new CEO of Apple (AAPL.US) reported a double increase in revenue in its first earnings report, and the Greater China region fell short of expectations. After the market on November 2, Apple announced the results for the fourth fiscal quarter of fiscal year 2026: revenue of US$114.477 billion increased 11.7% year on year, diluted EPS of 2.10 US dollars increased 14% year on year; gross profit margin was 47.9%. By business, iPhone revenue of $57.58 billion (+17.5%) and Mac revenue of 10.79 billion US dollars (+23.7%) were impressive; iPad revenue of 6.23 billion US dollars (-10.4%) and wearables of 8.3 billion US dollars (-7.9%) weakened, and service revenue of US$31.57 billion (+9.8%) reached a record high but the growth rate fell below 10%. Greater China's revenue of US$17.539 billion increased 21% year over year, but fell short of the forecast of US$18.75 billion. Management warned of an “unprecedented” rise in memory costs, gross margin guidance for the next quarter falling 45% to 46% lower than market expectations, and pre-market stock prices falling more than 4%.
Palantir (PLTR.US)'s Q3 revenue nearly doubled and guidance was raised, and it still fell more than 7% before the market. Palantir announced the third quarter earnings report after the market on November 2: revenue of US$2,313 billion surged 96% year on year, breaking US$2 billion for the first time and exceeding expectations of US$2.18 billion; net profit of US$1,128 million more than doubled year on year; adjusted EPS of $0.44 exceeded expectations of $0.41. The highlight is that US commercial revenue soared 148% year over year to 984 million US dollars, surpassing US government revenue of 953 million US dollars for the first time in history, confirming the explosion in corporate AI demand. The company raised its annual revenue guide to US$8.530 billion to US$8.534 billion (previously $8.155 billion), and expects Q4 revenue to be approximately US$2.65 billion. However, Q4's month-on-month growth rate was about 15% lower than the previous quarter's 20%, compounded by high valuations. After exceeding expectations for the 10th consecutive quarter, it “ran out of benefits” and fell nearly 8% before the market.
Pfizer (PFE.US)'s Q3 profit exceeded expectations, and non-COVID-19 products increased 7%, raising full-year results guidance. Pfizer's third-quarter adjusted diluted earnings of $0.87 per share were flat year over year, significantly higher than the market's consensus estimate of $0.73; GAAP diluted earnings per share of $0.56, down 9% year over year. Total revenue for the quarter was US$16.583 billion, which was basically the same as the previous year. After excluding COVID-19 products Comirnaty and Paxlovid, the revenue and operating caliber for the quarter increased 7%; among them, the revenue and operating caliber of listed and M&A products surged 32%, making it the biggest highlight of the quarter. Looking ahead, the company raised its 2026 revenue guidance from US$60.5 billion to US$62.5 billion to US$62-64 billion (midpoint increase of US$1.5 billion); the adjusted diluted earnings per share guidance was raised and narrowed from US$2.80-3.00 to US$2.95 to US$3.05.
AMD (AMD.US) will release an after-hours earnings report tonight. The market focuses on data center and PC demand. AMD is scheduled to announce third-quarter results after the US stock market on November 3. Wall Street expects revenue of about US$13 billion to US$13.2 billion (up about 18% year on year) and diluted EPS of about US$1.93 to 1.97. Among them, data center revenue is expected to be around US$8.19 billion (up 88% year over year), which is the absolute core; however, gaming business revenue may drop 49% to US$655 million, affected by a shortage of memory and storage driving up prices and dragging down demand for video cards and mainframe chips. The market is paying particular attention to the Q4 guidelines: if it is confirmed that the PC market is slowing down, mass production of Helios server racks and Instinct MI450 is delayed, or gross margin guidelines fall below 56%, analysts warn that the stock price may fall more than 10%. The current AI stock sell-off and Intel's disappointing earnings report last week have multiplied the pressure.
CrowdStrike (CRWD.US) spent $495 million to acquire two AI security startups. CrowdStrike will acquire Fiddler AI, headquartered in Palo Alto, California, for approximately $400 million. The company was founded in 2018 to develop software to monitor and interpret the behavior of intelligent agents. CrowdStrike also purchased DreadNode for approximately $95 million — an automated security testing platform that was established in 2023 to detect vulnerabilities in AI models before they go live. CrowdStrike said that most of the two purchase prices were paid in cash, and the remaining portion was restricted stock, with vesting conditions.
Nvidia (NVDA.US) Wong In-hoon endorsed the $100 billion merger between MRVL.US (MRVL.US) and Lumentum (LITE.US). People familiar with the matter revealed that the heads of the two companies, Maywell Technology and Lumentum, received support from Nvidia CEO Wong In-hoon before finalizing this nearly $103 billion merger deal. Maywell CEO Matt Murphy and Lumentum CEO Michael Helston spoke with Hwang In-hoon on the phone to ask for his opinion before the deal was announced. This is the second largest merger and acquisition case in technology history. Hwang In-hoon's statement highlights that Nvidia, as a leader in the AI field, is actively promoting integration among its key suppliers. Nvidia invested $2 billion in Maywell and Lumentum earlier this year, respectively.
Oracle (ORCL.US) raised $20 billion for AI expansion. Oracle announced on November 2, local time, that it will raise about 20 billion US dollars by issuing bonds and selling shares to support the construction of AI and cloud computing infrastructure. Oracle is issuing 86.2 million shares at a price of 116 US dollars per share, a discount of about 11.2% from last Friday's closing price. The bond portion consists of five batches of fixed-rate notes with terms ranging from 2029 to 2046, with interest rates ranging from 7% to 8.65%. The company stated that the funds raised will be used for general corporate purposes such as capital expenditure, debt repayment, investment or acquisition, and dividend payments and stock repurchases.
Key economic data and event forecasts
23:00 Beijing time: Revised monthly rate of US durable goods orders in September, US JOLTS job vacancies in September, US monthly factory order rate in September
The next day at 05:30 Beijing time: API crude oil inventory for the week from the US to October 30
Performance Forecast
Wednesday morning: AMD, AMGN.US, Arista Networks (ANET.US), Booking Holdings (BKNG.US), Astera Labs (ALAB.US), Ultra Microcomputer (SMCI.US), SWKS.US
Wednesday pre-market: Novo Nordisk (NVO.US), McDonald's (MCD.US), Uber (UBER.US), Datadog (DDOG.US), Emerson Electric (EMR.US)