


EN
Williams Companies (WMB) Reports Higher Earnings And Files Shelf Registration, Is It Fully Priced?
Williams Companies earnings and shelf registration move into focus
Williams Companies (WMB) just paired higher third quarter and nine month earnings with a fresh universal shelf registration, a combination that puts both recent profitability and future financing options on investors' radar.
The latest earnings and the fresh shelf filing landed after a sharp 1 day share price decline of 4.25%, yet Williams Companies still carries a 16.99% year to date share price return and a 1 year total shareholder return of 24.27%. This suggests that longer term momentum has held up better than the recent pullback implies.
Scan beyond Williams Companies and size up other energy infrastructure plays that show resilient earnings and balance sheet strength using our curated list of solid balance sheet and fundamentals (24 results) list.
Williams Companies has the pipes, the cash flow and fresh flexibility from that universal shelf. After a long run and a sudden drop, are investors paying a fair price for that strength today?
Most Popular Narrative: 17% Undervalued
Williams Companies last closed at $71.19, while the most followed narrative pegs fair value closer to $85.61. This puts the current shelf registration and capital spending plans in a different light for investors weighing risk and reward.
The Power Innovation platform, backed by a US$5.34b equity funding commitment from partners, is supporting a series of behind the meter projects such as Socrates and Neo that carry multi year contracts, which can add incremental contracted earnings and improve overall returns on invested capital.
The commercialization of Neo, a 682 MW behind the meter power project with a 12.5 year contract and an expected build multiple of about 5x, together with continued phases of Socrates, provides Williams Companies with a growing base of long duration power cash flows that can support EBITDA growth beyond the traditional pipeline business.
See why 31 investors see Williams Companies as 17% undervalued.
Result: Fair Value of $85.61 (UNDERVALUED)
Still, two pressure points could shake that Williams Companies narrative: slower progress or setbacks on key Haynesville and Power Innovation projects, and leverage drifting above the 4.0x comfort zone.
Find out about the key risks to this Williams Companies narrative.
Another View: What Williams Companies' P/E Ratio Is Signaling
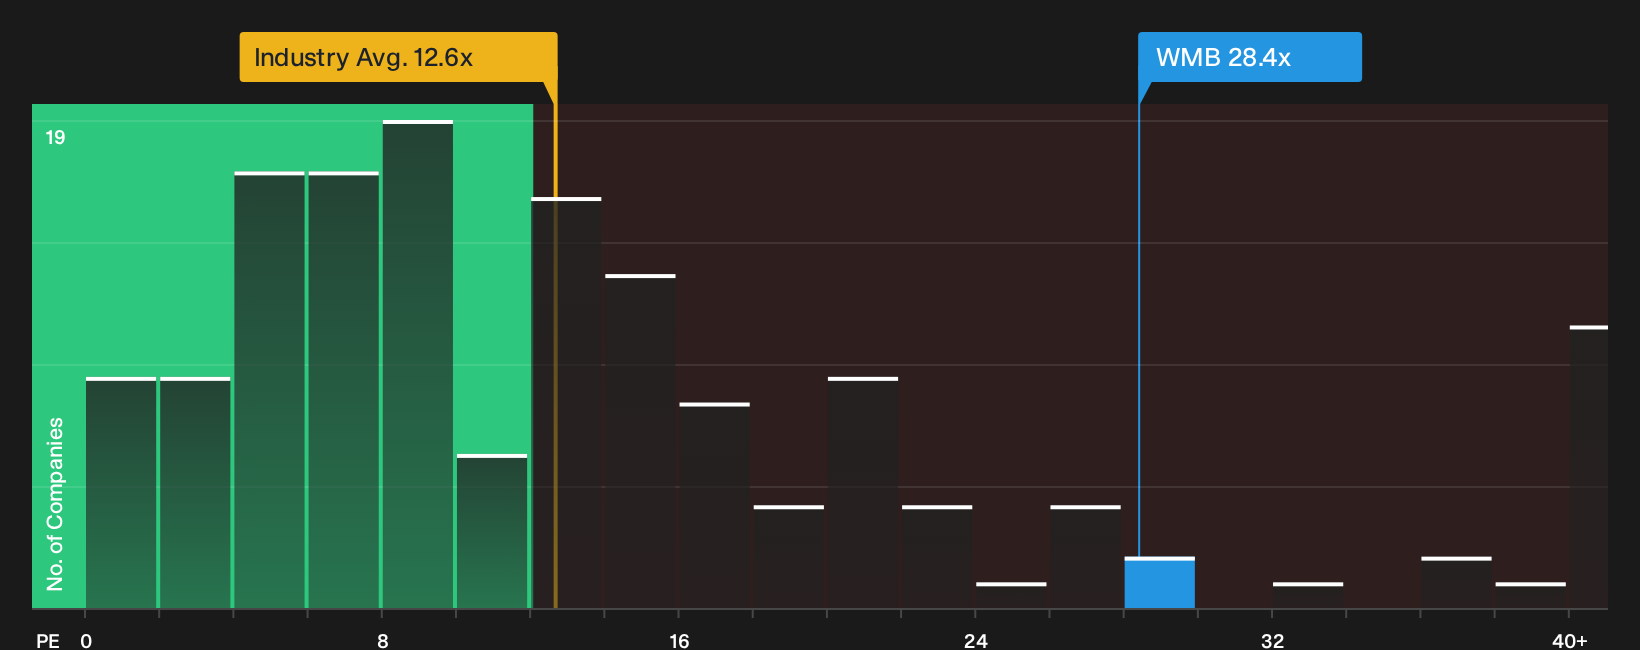
On a simple earnings multiple, Williams Companies tells a very different story. The stock trades on a P/E of 28.4x compared with a peer average of 17x and a fair ratio estimate of 24x, which points to a richer valuation and less room for error if the growth narrative stumbles.
That kind of gap can reflect confidence in Williams Companies' contracted projects, or it can mean investors are already paying up for a lot of optimism. The question is whether you see that premium as justified upside potential or valuation risk that deserves a margin of safety before committing fresh capital.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals on Williams Companies valuation and risk do not need to leave you on the fence. Weigh the recent moves, review the data, then pressure test your own thesis with the 3 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Williams Companies?
If Williams Companies sharpened your focus on quality and valuation, do not stop here. Broaden your watchlist now so you are not chasing the next move after it happens.
- Target potential mispricings by scanning a curated pool of quality companies using the 34 high quality undervalued stocks.
- Prioritise resilience by reviewing a 29 resilient stocks with low risk scores that aims to keep downside in check while you hunt for upside.
- Spot fresh opportunities early by working through a 19 high quality undiscovered gems before they land on everyone else's radar.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com