


EN
Vor Biopharma (VOR) Stock May Look Reasonable On Telitacicept Trial Progress
Vor Biopharma has climbed sharply this year, yet long term holders have seen a very different experience, which puts fresh focus on what its current share price says about the business it is building. With the stock now trading at US$19.25, the live question is whether that quote is adequately grounded in Vor Biopharma's earnings profile.
- The share price has fallen 94.7% over the past 5 years, so every move today feels like a referendum on what the underlying earnings potential is worth.
- Recent clinical progress for telitacicept, including advanced trials in autoimmune and kidney conditions and expectations that existing cash may fund operations into early 2029, can shape how quickly earnings might eventually scale relative to ongoing development spending.
- The analysts covering Vor Biopharma have run their own numbers. See what analysts think Vor Biopharma's shares could be worth.
The stock's next move may depend on whether Vor Biopharma's current earnings picture can reasonably support where the shares trade today.
To see how this question about Vor Biopharma's earnings translates across a wider opportunity set, compare it with companies in the 34 high quality undervalued stocks.
Is Vor Biopharma a Bargain on Earnings?
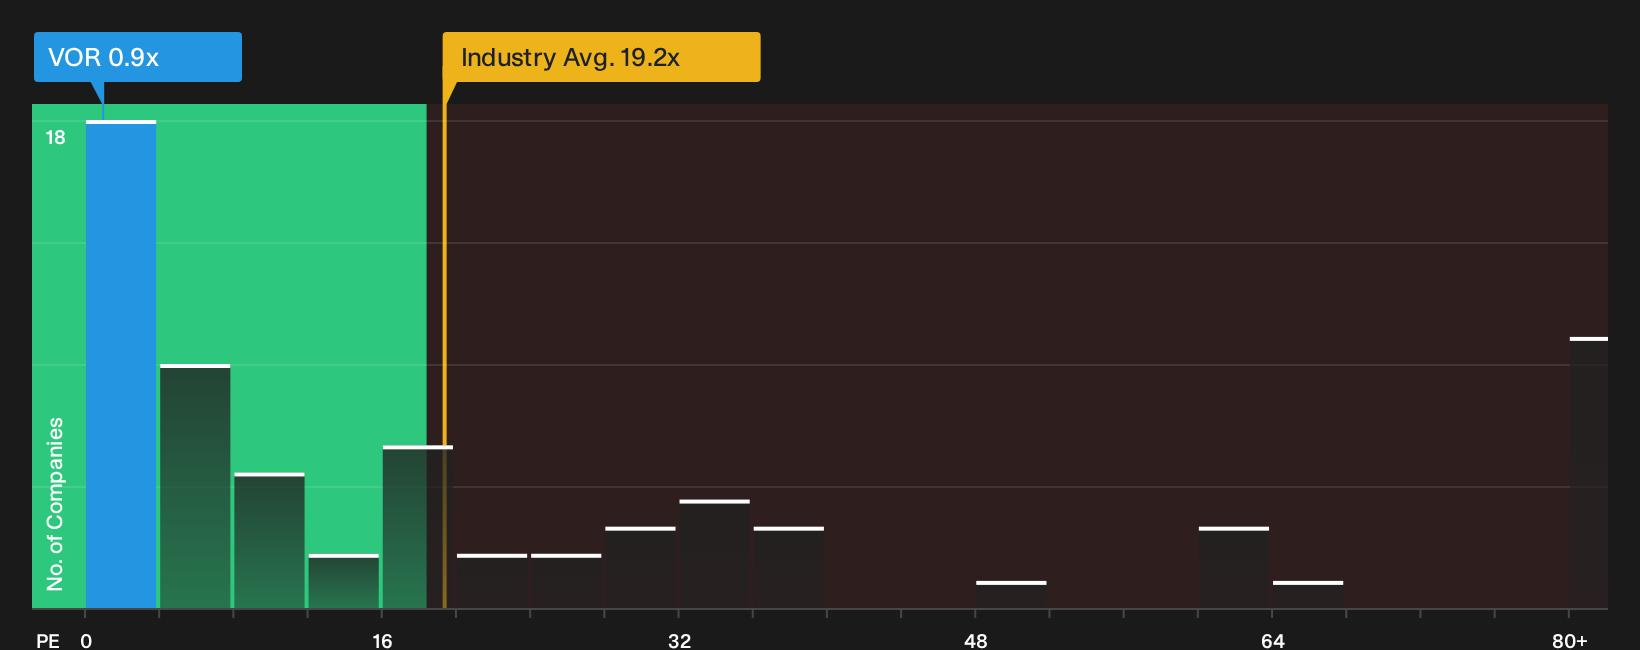
The P/E ratio is useful for Vor Biopharma because it ties the current share price directly to the small earnings base investors are paying for today. On this measure, the stock trades on a P/E of 0.9x, which is far below the Biotechs sector average of 19.2x and also below the peer group at 5.9x. Against a tailored fair multiple that blends the sector backdrop with Vor Biopharma's own risk profile, that gap points to the shares screening as undervalued on this specific yardstick.
Because the recent telitacicept trial progress has sharpened attention on the pipeline, the very low P/E suggests the market is still cautious about how durable those earnings will be. For a reader, the key question is whether Vor Biopharma's clinical and cash runway profile justifies a valuation multiple closer to peers, or whether the current discount fairly reflects the development and regulatory risks that remain. Explore the numbers behind Vor Biopharma's P/E valuation.
The Vor Biopharma Narrative: What Would Justify Today's Price?
Vor Biopharma’s valuation puzzle only really makes sense once you spell out what would need to happen to future growth, margins and earnings for the stock to be worth materially more or less than today’s share price. That is where Simply Wall St Narratives come in on the Community page. Each scenario lays out the earnings and cash flow assumptions sitting behind its view of fair value, so you can measure those expectations against Vor Biopharma's reported results over time.
One of the top community narratives on Vor Biopharma: 67% undervalued
"Repurposing telitacicept, which already has six approvals and extensive use in China, into Western markets could widen Vor Biopharma’s addressable base..."
Discover why this Narrative puts Vor Biopharma at 67% undervalued.
Why Vor Biopharma’s share price is only half the story
Before you treat Vor Biopharma’s valuation as the whole picture, it is worth asking who is actually steering the business, how their pay is structured, and whether those incentives truly line up with your own. See who runs Vor Biopharma and how they are paid.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com