


EN
3 Cash Flow Stocks With Up To 50% Fair Value Upside
Interest rates in Australia are now at an 18 year high of 4.85% as the Reserve Bank tries to keep inflation in check. When borrowing costs rise, investors often pay closer attention to businesses that steadily generate cash and still trade at a discount to what their future cash flows suggest. This article highlights three such undervalued cash flow stocks that feature on the SWS DCF driven value screen.
The three stocks highlighted below are only a small sample, with the full SWS DCF screen surfacing 458 additional companies whose cash flow profiles and current pricing raise similarly interesting questions for value driven investors.
To identify and analyze the ideas that best fit your own criteria, head straight to the Undervalued Stocks Based On Cash Flows screener.
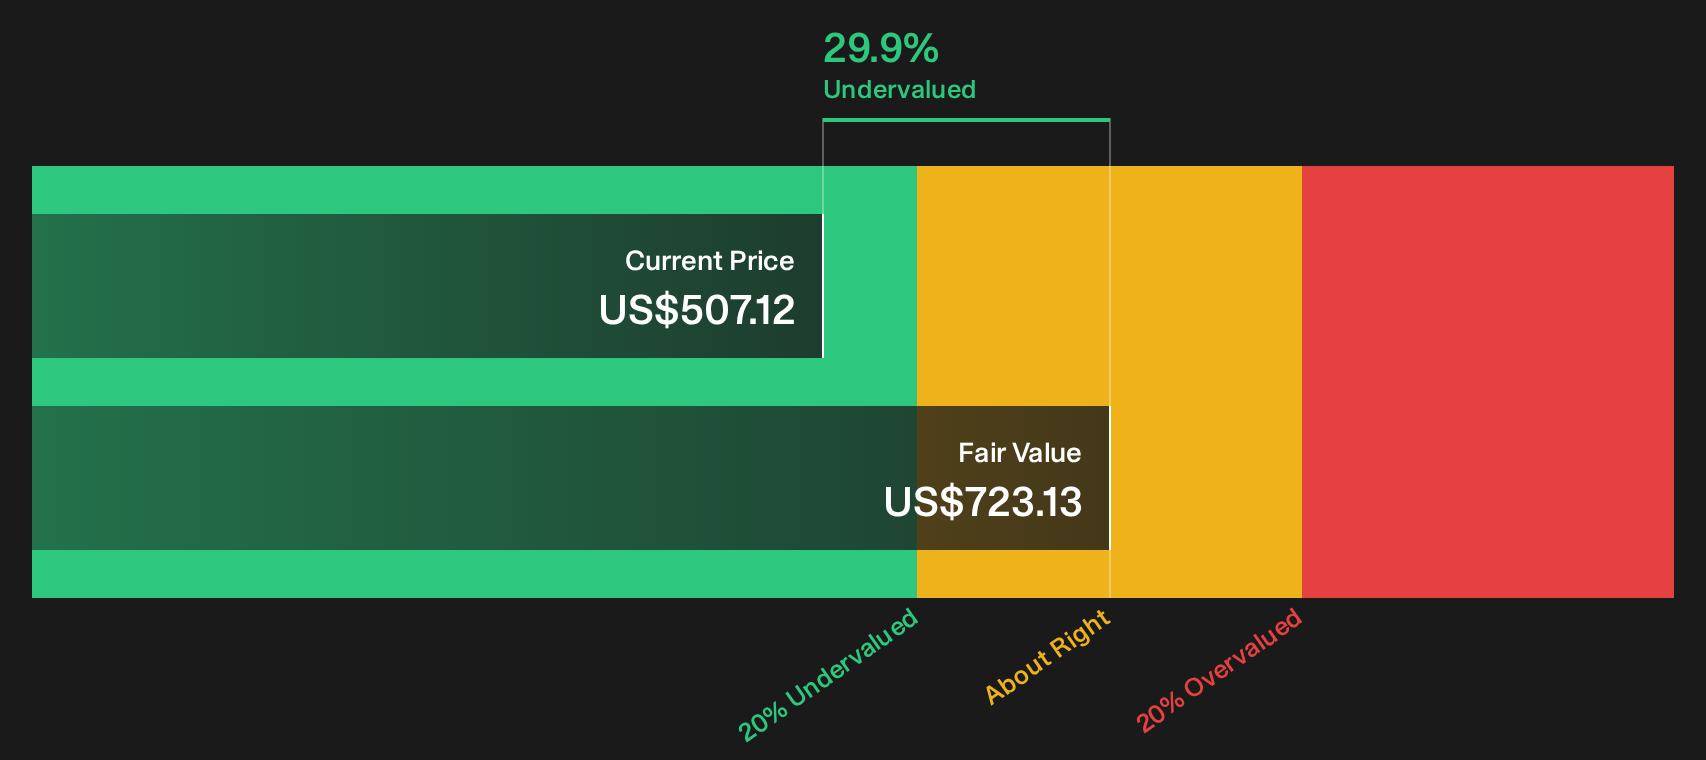
Microsoft (MSFT)
Microsoft matters for this cash flow focused screen because its large cloud and AI operations help generate recurring income streams that underpin discounted cash flow estimates. This is occurring while the wider business still spans Office, Windows, gaming and hardware.
Microsoft is a global technology group providing software, cloud computing, business applications, gaming and devices. Its revenue is split between the United States at about US$180.2b and other countries at roughly US$166.3b, and it has a market value near US$3,875.8b.
"The most immediate threat to Microsoft’s financial health is the significant Capital Expenditure (CapEx) commitment. Microsoft is currently pouring tens of billions of dollars per quarter into AI infrastructure on the assumption that this will yield substantial software margins."
What eventually happens to those margins will depend on how one relatively quiet structural pressure on this cash-intensive buildout resolves over time.
That pressure point is exactly where the story gets interesting, and the full narrative for Microsoft lays out how this CapEx surge could either compress or accelerate Microsoft’s long term cash engine.
Alphabet (GOOGL)
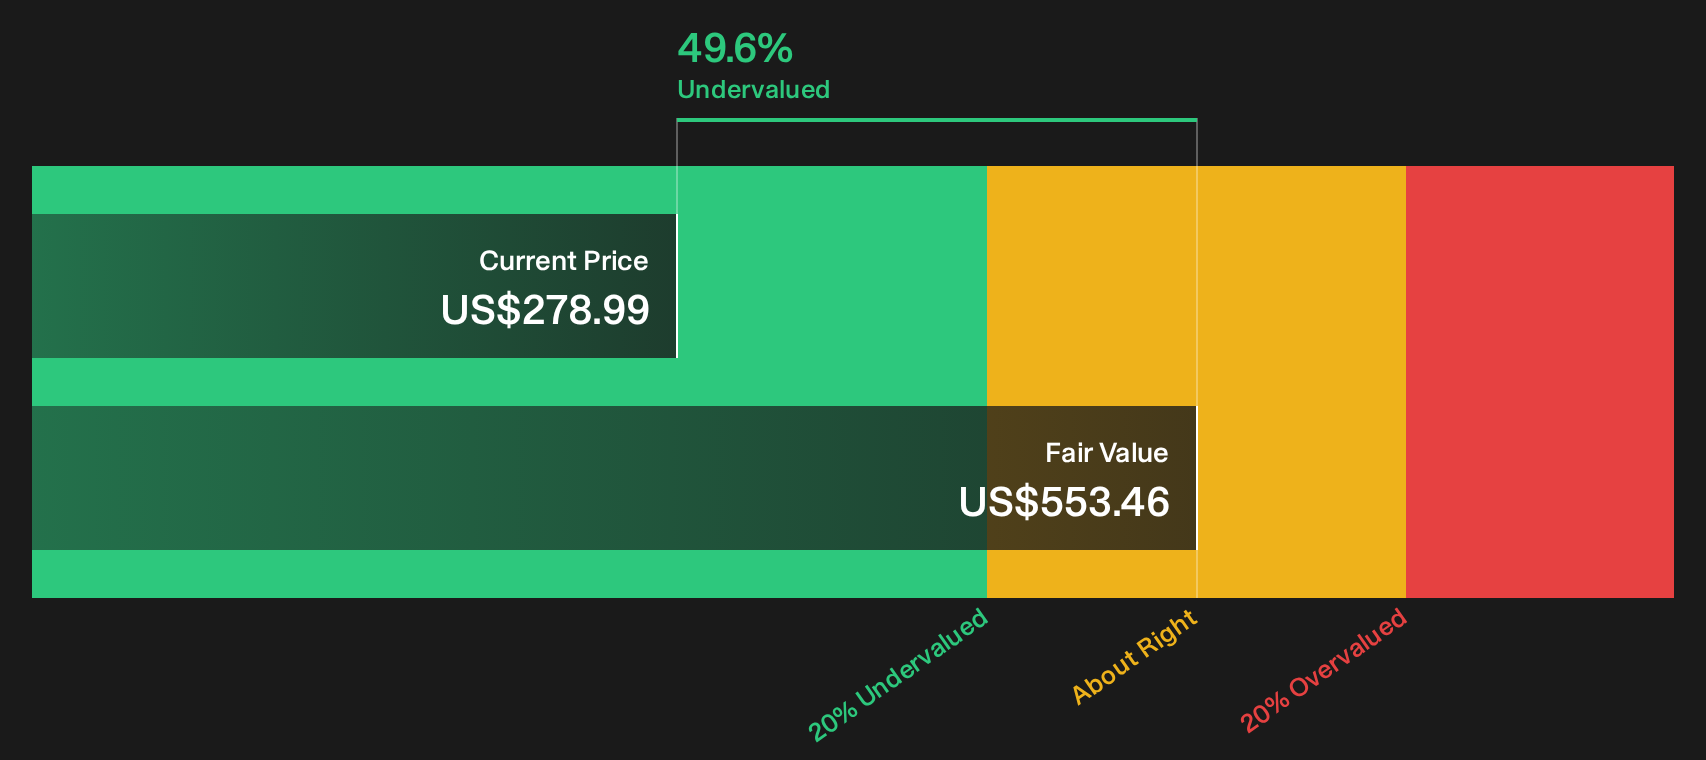
Alphabet is best known for Google Search and YouTube, yet the reason it fits this cash flow screen is the growing weight of Google Cloud and its AI platforms, which add subscription and usage based income on top of a large advertising and consumer services base.
Alphabet runs Google Services, Google Cloud and Other Bets, with Google Services generating about US$376.3b in revenue, Google Cloud about US$93.2b and Other Bets roughly US$1.5b. The group, headquartered in Mountain View, carries a market value near US$3,431.3b.
For investors focused on cash flow driven value, Alphabet ties a large advertising engine to a younger cloud and AI arm that highlights the role recurring enterprise contracts can play when pricing long term cash streams.
"Google Cloud has gone from “meh” to money-maker. • Now #3 globally behind AWS and Azure, with over 11% market share."
The key variable is how one steadily building source of AI related demand ultimately flows through to long term profitability and free cash generation.
When that AI demand story starts to bite, the full narrative for Alphabet shows how Alphabet’s cash engine could accelerate, decouple from ads and reshape the business mix.
Caterpillar (CAT)
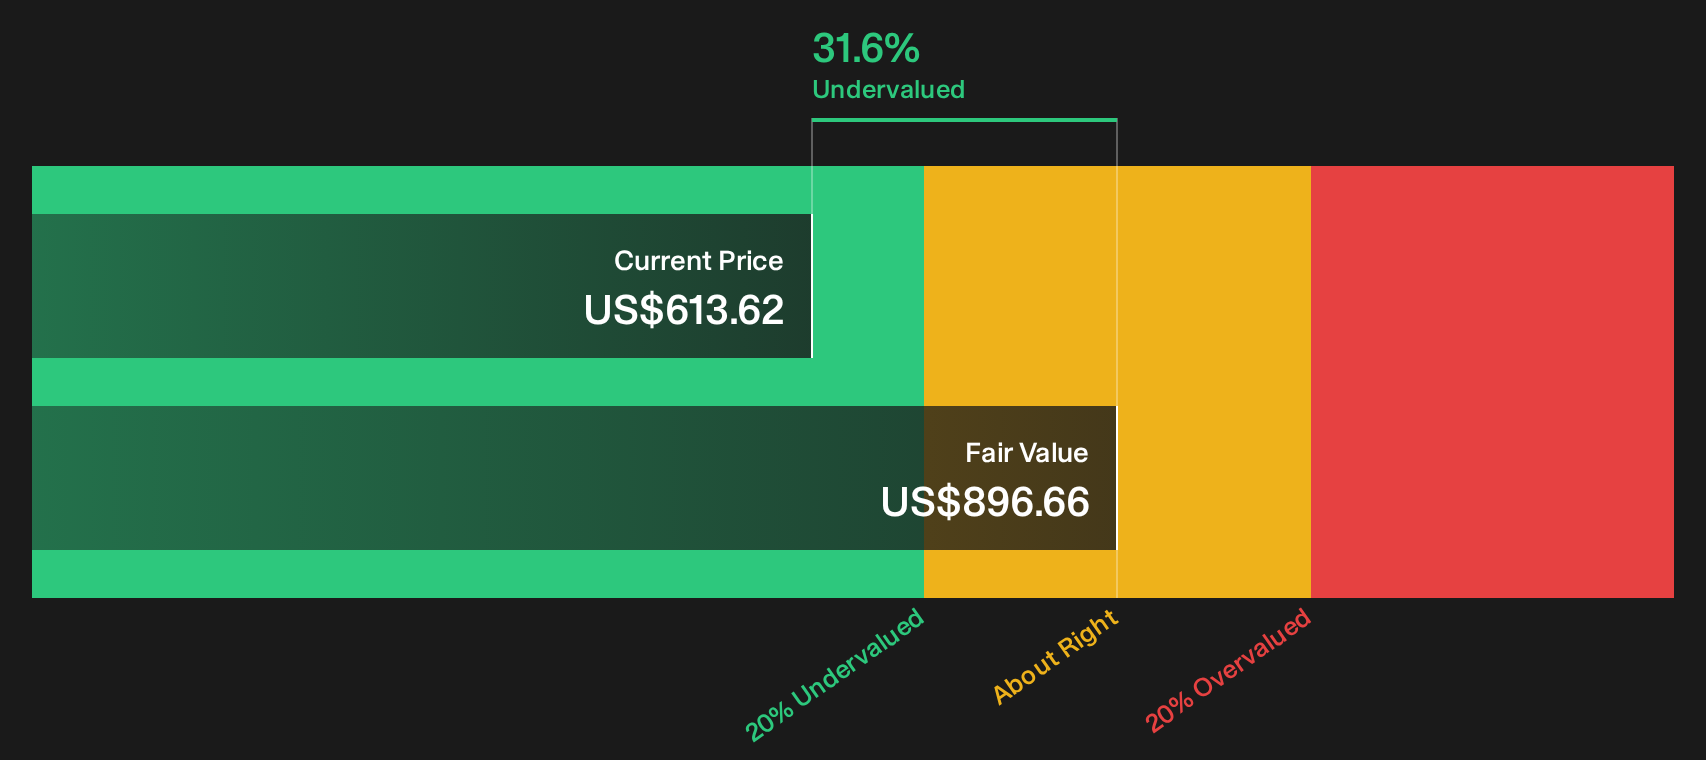
Caterpillar anchors this cash flow themed list because heavy equipment, aftermarket services and in house financing combine into a machine that can throw off recurring cash, even though not every segment is tied directly to those long lived construction and mining assets.
Caterpillar is a global industrial group best known for construction and mining machinery, with Financial Products generating about US$4.6b of revenue alongside broader segment activity that feeds its equipment and services ecosystem. The business is valued at roughly US$286.3b.
Caterpillar’s relevance to this undervalued cash flow screen rests on how much of its future income stems from equipment that keeps working for decades, and the parts, service contracts and financing that follow each unit into the field.
"Record sales and revenues of US$20.5b in Q2 2026 alongside a US$72b backlog concentrated in equipment and power systems that are still to be produced and delivered give Caterpillar multi quarter visibility on future shipments, which can support revenue and earnings as this backlog converts."
What really moves the needle from here is whether one less visible cost pressure quietly eats into those hard won margins as that backlog rolls through.
If that cost pressure proves smaller than feared, the full narrative for Caterpillar reveals how Caterpillar’s backlog, services and financing could keep cash generation accelerating.
Seeking Alternatives Before Others Do
Fresh ideas move first. Some tickers are building quiet momentum, others are dropping into value territory and a few are still under the radar for now. Do not get caught watching. Consider researching these opportunities early if they fit your strategy.
- Explore potential income by reviewing a curated group of companies screened for resilience and yield in the 4 dividend fortresses before that combination of cash flow and payouts changes.
- Track where real AI revenue meets discipline by scanning the 40 profitable AI stocks that aren't just burning cash while many investors still focus on stories rather than underlying earnings quality.
- Review companies exposed to electrification trends by checking the hand picked producers in the 16 top copper producer stocks while the link between metals supply and future grid spending still feels distant for some investors.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com