


EN
What AUTO1 Group Investors Missed Before The Fall
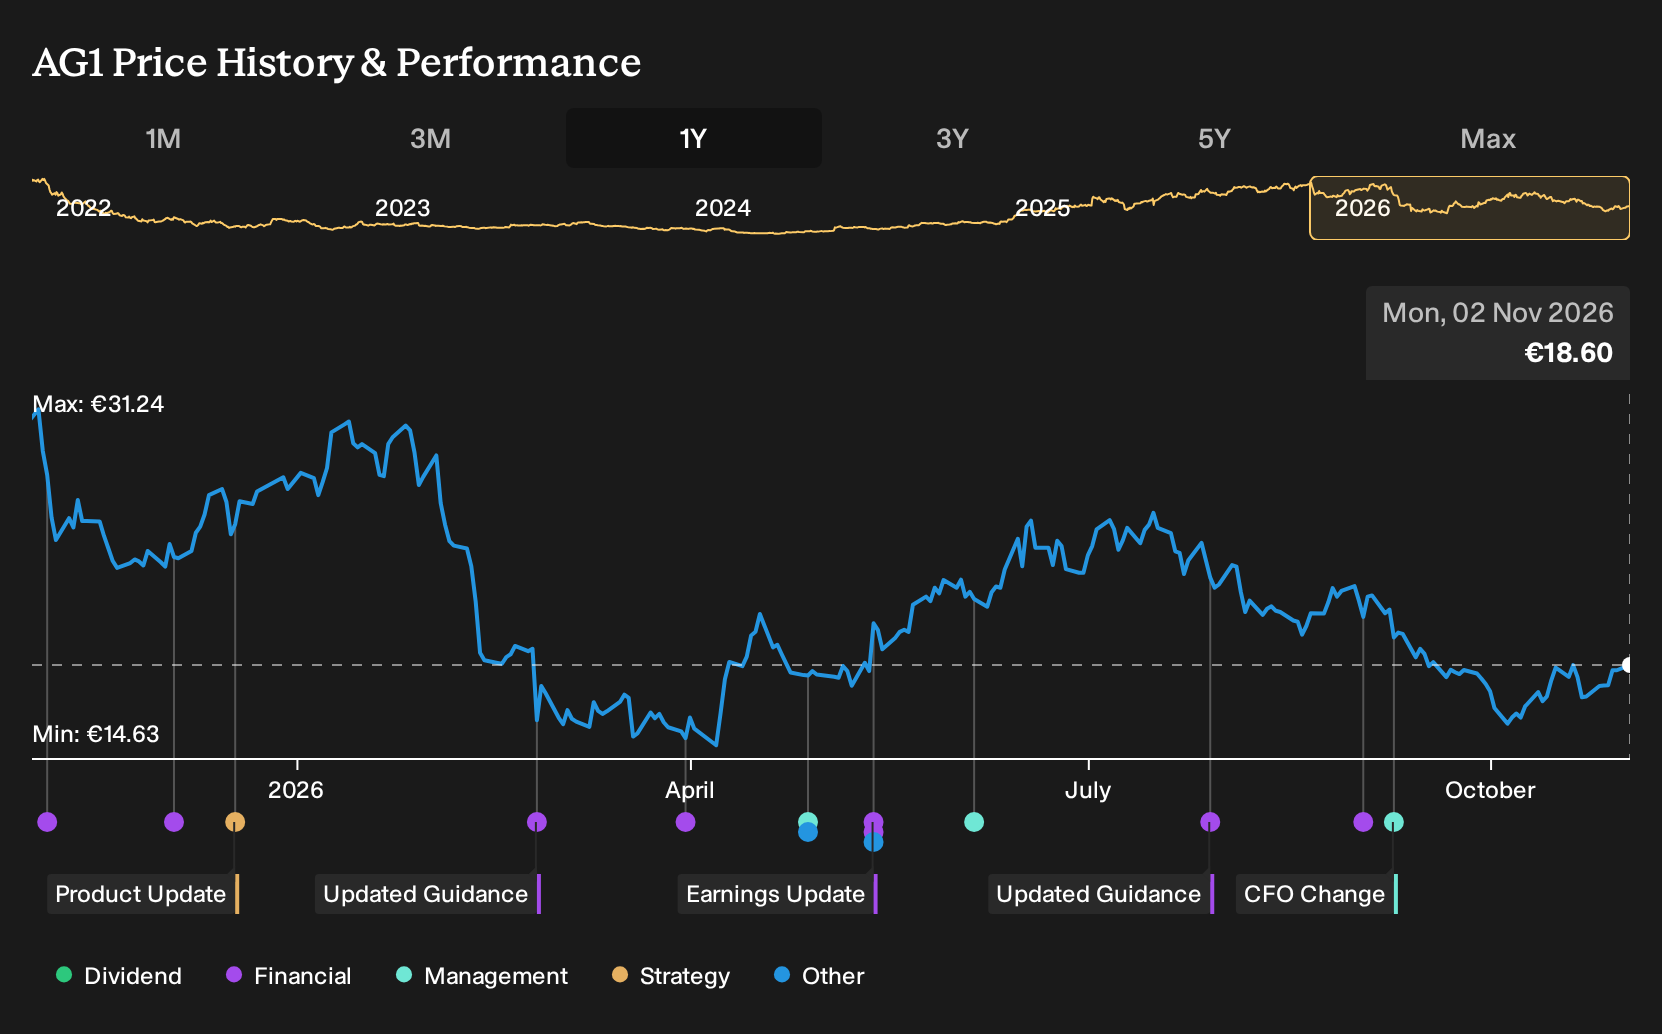
If you had looked at AUTO1 Group in late 2025 and decided it felt too optimistic to buy into growth targets and expanding branches, that pass would have avoided a difficult year. Investors who held AUTO1 Group over the past year are down 40.5%, including dividends. With that outcome now visible and fresh 2026 results on the table, which assumptions from the earlier bullish and cautious cases most clearly deserved tougher scrutiny at the time?
The useful thing about a Narrative is that the reasoning is checkable: the assumptions sit beside the argument, and together they imply an estimated Fair Value you can disagree with.
This theme extends beyond AUTO1 Group. See which of 53 AI infrastructure stocks may still merit a closer look.
The Argument You Would Have Been Weighing Up On AUTO1 Group
The shares cost €30.44 at the start of the period, and the debate around AUTO1 Group turned on how far a digital used car platform could push its model before the economics hit resistance.
The bullish Narrative saw a Fair Value of €35 and leaned on 15.6% annual revenue growth assumptions plus profit margins rising to 2.7%, with AUTO1 using network effects and a closed-loop finance ecosystem to lift high margin income.
The more cautious view anchored on Fair Value of €28.09 and focused on expanding branches and platform upgrades, while flagging higher operational spending and seasonal softness as risks to near term profitability.
What The Results Changed For AUTO1 Group
AUTO1 Group’s Q2 2026 report showed revenue of €2,432.055m and net income of €23.159m, with net margin at 1.0%. That shift from €1,970.567m revenue and €15.489m profit, with a 0.8% margin in Q2 2025, leaned toward the view that scale and efficiency could lift both sales and profitability, although margins remained well below the 2.7% target.
The useful takeaway is clear. When a story leans on future margin expansion, track the reported net margin quarter by quarter and compare it directly with the percentage path that was assumed in the original case.
What You Are Being Asked To Believe About AUTO1 Group Today
AUTO1 Group now trades at €18.6, and the selected Narrative sees Fair Value above that level based on how earnings quality and cash generation might evolve.
The core pitch is that profit growth is real. However, the key test is whether AUTO1 Group can turn adjusted EBITDA and network scale into stronger, sustained cash conversion.
"The main requirement for improvement is that AUTO1 Group continues to grow Merchant and Autohero volumes and gross profit, while expanding adjusted EBITDA and improving cash conversion through its AI-enabled operations, financing products and ABS funding structures."
That disagreement has a full argument behind it. → Uncover the higher Fair Value this Narrative argues for
Looking Past AUTO1 Group
AUTO1 Group leans on data, financing and software to move cars efficiently. One step away, another business works on the digital rails behind many online transactions.
Instead of focusing on vehicles, this operator builds broad commerce and cloud infrastructure. Merchants rely on it to reach buyers, handle payments and manage logistics.
On top of that base, the group develops its own AI models and tools. Those systems support search, recommendations and productivity apps across its ecosystem.
The interesting thread is simple. As more activity shifts online and into software, control of that infrastructure could matter as much as owning the storefront.
One Narrative has already put a figure on it. → Uncover the company trading 58% below one Narrative's Fair Value
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com