


EN
Does Q3 Earnings Preview Change The Bull Case For Host Hotels & Resorts (HST)?
- Host Hotels & Resorts set a Nov. 4 release for its Q3 2026 earnings, with expectations for year over year gains in revenue and adjusted funds from operations supported by leisure travel, group bookings and higher room rates.
- The focus on revenue per available room and adjusted funds from operations highlights how underlying travel demand and pricing trends may matter more than headline earnings, especially with interest expenses putting pressure on the bottom line.
- We will look at how Host Hotels & Resorts' investment narrative lines up with expected Q3 RevPAR and AFFO strength.
Scan how Host Hotels & Resorts compares with other travel exposed real estate plays by reviewing our hand picked list of solid balance sheet and fundamentals (24 results) that may better handle higher interest costs.
Host Hotels & Resorts Investment Narrative Recap
For Host Hotels & Resorts, the big belief is that leisure and group travel can keep doing the heavy lifting while the large renovation pipeline gradually feeds into better RevPAR and AFFO. The upcoming Q3 2026 report mainly tests that demand picture. If RevPAR and AFFO track expectations, the near term thesis probably stays intact.
The main near term swing factor remains how much higher interest costs bite into earnings, even if hotel level performance looks healthy. Structural pressure in business travel, weather related disruption at resort markets and sizable capital spending commitments all sit on the risk side. The Q3 print matters for confirming that these headwinds remain manageable.
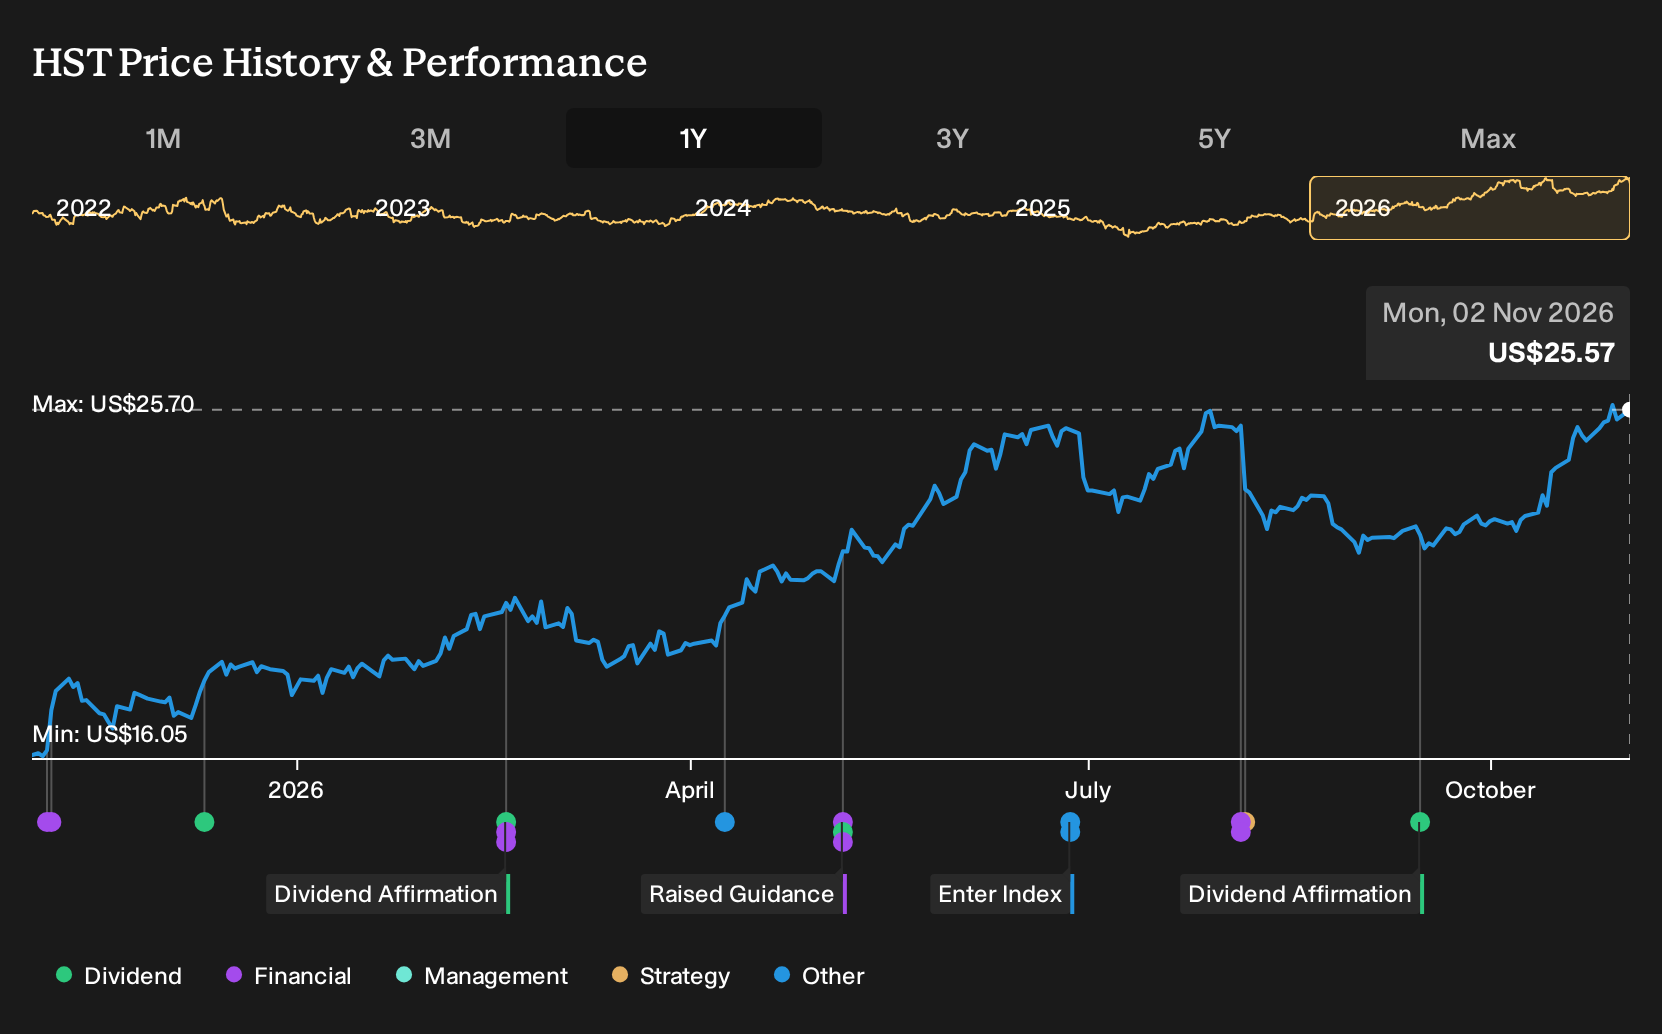
The Q3 2026 earnings release on 4 November is the key event tying together this operating story. Management is expected to show how leisure travel, higher room pricing and group bookings translate into RevPAR and AFFO per share. That update provides fresh data on whether the recent improvement in earnings and margins is still coming through.
This announcement also matters because higher interest expense has been an open issue for Host Hotels & Resorts. The new numbers will show how much AFFO can absorb that drag, while the 34 hotel renovation and development projects continue to require cash. For anyone tracking catalysts, the report helps connect property level momentum with balance sheet pressure in a clear way.
Host Hotels & Resorts is modeled to generate US$6.4b of revenue and US$831.3m of earnings by 2029, with analysts assuming revenue stays broadly flat and earnings decline by about US$168.7m from current earnings of roughly US$1.0b.
Uncover why Host Hotels & Resorts' fair value is consistent with its current price.
Exploring Other Perspectives
One alternate view on Host Hotels & Resorts leans hard into wage inflation risk. The most bearish analysts argue that rising labor and operating costs could squeeze margins toward about 10.6% and hold earnings near US$657.5m by 2029 instead of US$831.3m. These forecasts were all set before the upcoming Q3 release, so treat them as starting points and compare multiple perspectives before you decide how this new information might reshape your own view.
Explore another Host Hotels & Resorts fair value estimate, including one that suggests it could be worth just $25.82.
Reach Your Own Conclusion
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Host Hotels & Resorts research is our analysis highlighting 2 key rewards and 4 important warning signs that could impact your investment decision.
- See our latest analysis for Host Hotels & Resorts. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Host Hotels & Resorts' overall financial health at a glance.
Looking for more investment ideas beyond Host Hotels & Resorts?
If the Host Hotels & Resorts story has sharpened how you think about balance sheets, cash generation and income, you can use that same lens across the wider market with the Simply Wall St Screener.
- For investors who want potential growth with strict price discipline, scan a curated set of 34 high quality undervalued stocks that combine quality fundamentals with lower implied expectations.
- If capital preservation sits high on your list, you can focus on a 29 resilient stocks with low risk scores to see companies that score well on financial strength and volatility.
- When you prefer lesser known stories with solid underpinnings, review a 19 high quality undiscovered gems that may not be widely followed but still show robust metrics.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com