


EN
Norwegian Cruise Line Holdings (NCLH) Could Be 4% Undervalued On Raised EBITDA Guidance
Why Norwegian Cruise Line Holdings Is Back on Investor Radar
Norwegian Cruise Line Holdings (NCLH) moved into focus after third quarter results beat expectations, management raised full year adjusted EBITDA guidance, and analysts responded with a wave of rating upgrades.
Over the past week, Norwegian Cruise Line Holdings has surged, with a 7 day share price return of 17.64% and a 30 day share price return of 18.49%, as stronger third quarter earnings, higher full year adjusted EBITDA guidance, and fresh management commentary on bookings shifted investor perceptions of risk and recovery potential. That short term momentum contrasts with a year to date share price return that is down 21.25% and a 1 year total shareholder return that is down 19.12%. Even though the 3 year total shareholder return is up 36.84%, the recent rally appears more like a rebound within a longer, uneven performance record rather than a completed turnaround.
Scan the rebound in Norwegian Cruise Line Holdings in comparison with hand-picked travel and leisure plays with solid balance sheets using the list of solid balance sheet and fundamentals (24 results).Norwegian Cruise Line Holdings now trades only modestly below the average analyst target after a sharp bounce. Is that discount a fresh opportunity, or a fair reflection of lingering balance sheet and earnings risk?
Most Popular Narrative: 4% Undervalued
Norwegian Cruise Line Holdings last closed at $17.94, compared with a widely followed fair value estimate of $18.63 that uses a 12.54% discount rate to weigh future cash flows and risks.
Measured fleet renewal that retires older ships, adds higher earning vessels and moderates capacity growth after 2027 is set to reduce growth capex by about US$1b annually from 2028. This can free up cash flow that supports deleveraging and, over time, net margin and earnings quality.
See why 54 investors see Norwegian Cruise Line Holdings as 4% undervalued.
Result: Fair Value of $18.63 (UNDERVALUED)
Still, Norwegian Cruise Line Holdings faces heavy debt and ongoing yield pressure at its core brand, which could quickly erode confidence in this undervalued narrative.
Find out about the key risks to this Norwegian Cruise Line Holdings narrative.
Another View: SWS DCF Flags A Very Different Picture
The popular narrative has Norwegian Cruise Line Holdings trading about 4% below an $18.63 fair value. The SWS DCF model points in the opposite direction. On that framework, NCLH at $17.94 sits well above an estimated future cash flow value of just $2.80, which frames the stock as heavily overvalued on cash generation alone. Which lens do you trust more when earnings and cash flow tell different stories?
Look into how the SWS DCF model arrives at its fair value.
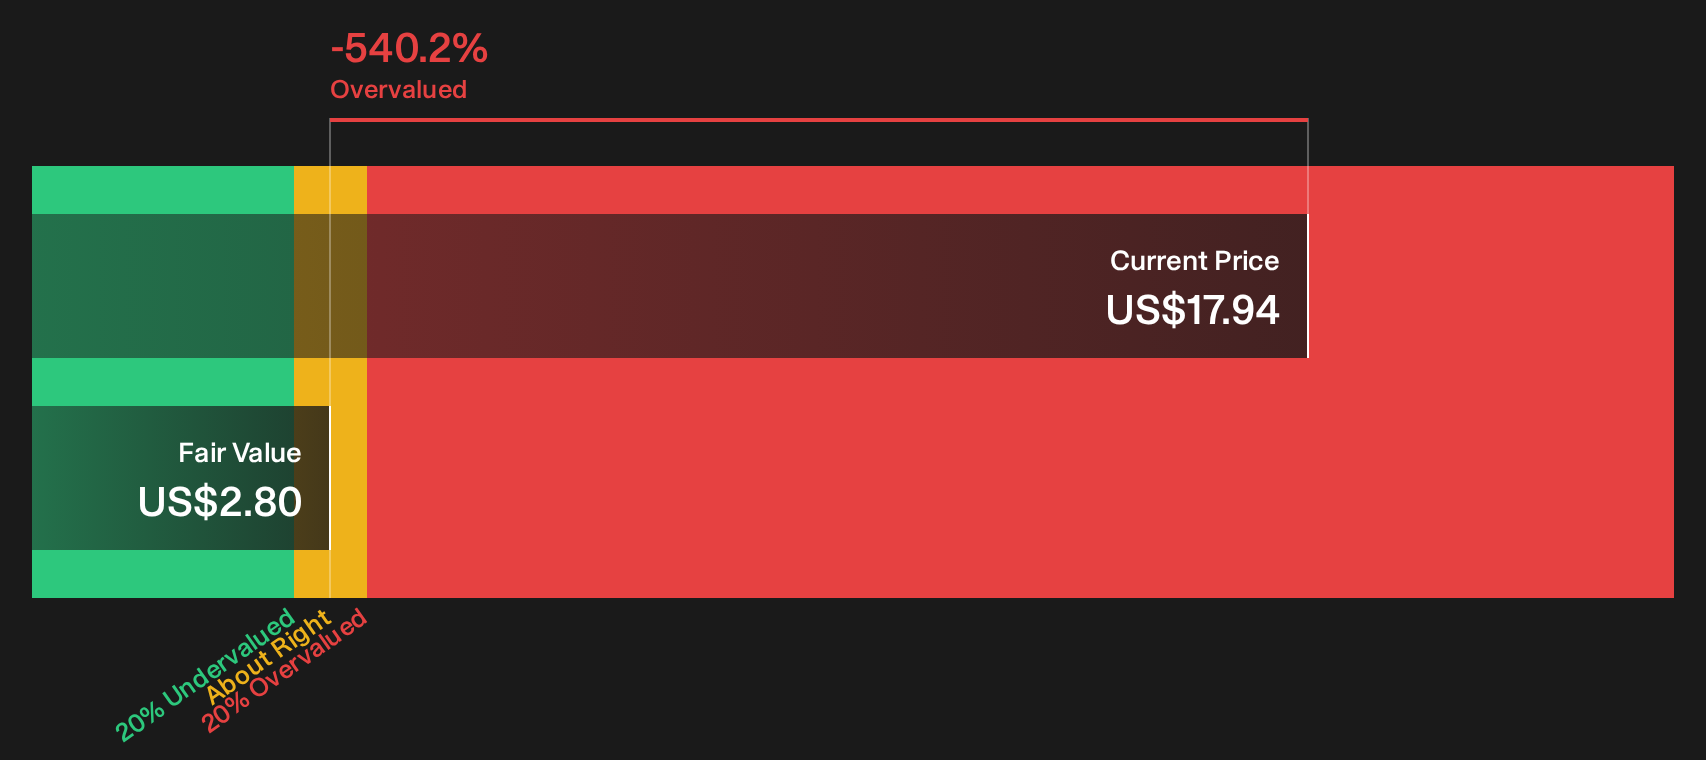
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Norwegian Cruise Line Holdings for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 34 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals on Norwegian Cruise Line Holdings so far. If the cross currents feel strong, move quickly to review the data and form your own takeaway using 3 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Norwegian Cruise Line Holdings?
Do not stop with one cruise operator. Use the Simply Wall Street Screener to compare more companies, cross check risks, and pressure test your own thesis.
- Spot potential bargains early by scanning our global set of underpriced quality businesses through the 34 high quality undervalued stocks.
- Prioritise resilience first by filtering for companies with stronger balance sheets and fundamentals using the list of solid balance sheet and fundamentals (24 results).
- Hunt for overlooked opportunities by reviewing the 19 high quality undiscovered gems before the wider market pays attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com