


EN
Learn Why The Bull Case For MannKind Stock Could Change Following Product Approvals
- MannKind has had a difficult 2026, with attention turning to whether the current valuation aligns with its cash flow potential as revenue reflects contributions from the Furoscix ReadyFlow acquisition and recent product approvals.
- The key angle is how a growing mix of owned therapies, including Furoscix ReadyFlow, could reshape MannKind's future cash generation profile, even while the business still reports losses.
- The focus is now on how this renewed attention on MannKind's revenue and cash flow outlook could influence its broader investment narrative.
Compare MannKind's setup with other potential rebound stories by scanning the hand picked 34 high quality undervalued stocks that pair solid fundamentals with compressed valuations.
MannKind Investment Narrative Recap
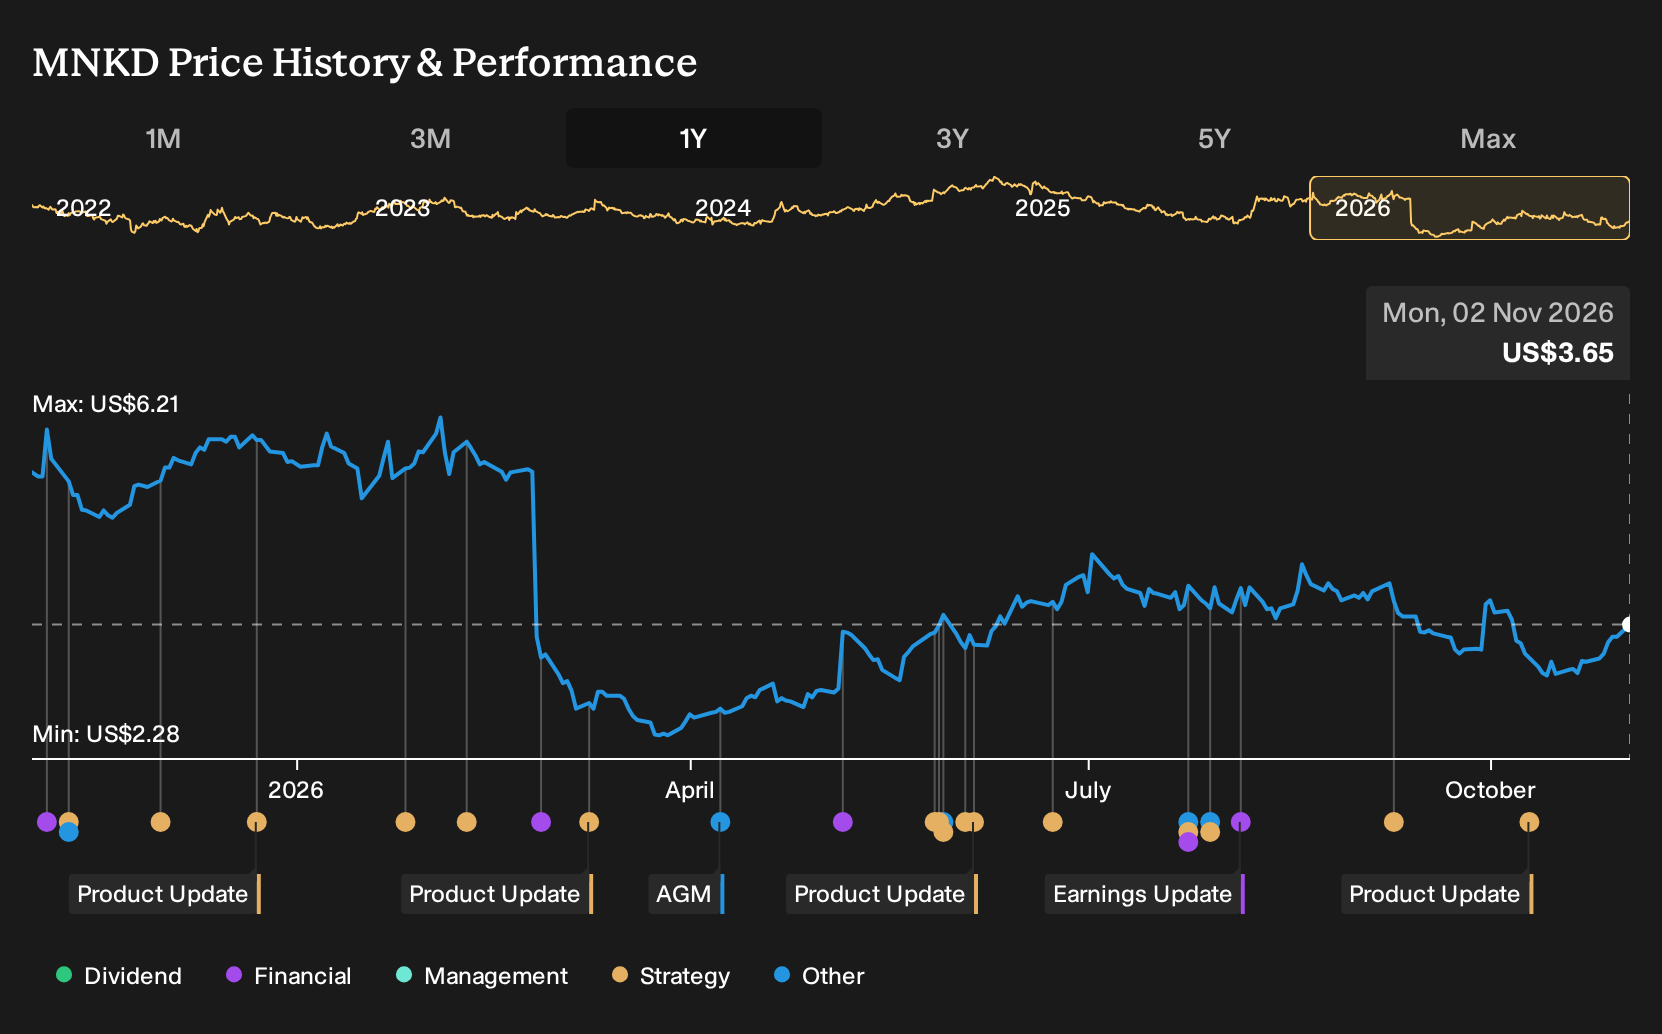
MannKind asks you to believe that owned therapies like Afrezza, Furoscix ReadyFlow and Tyvaso DPI can fund a shift from losses to durable cash generation over time. The recent 37.5% share price decline in 2026 does not change the basic operational story, which still rests on execution in diabetes, heart failure and pulmonary disease.
The key near term swing factor is how cleanly MannKind scales revenue from these products while keeping R&D and SG&A from running too far ahead. The main risk is that elevated launch and pipeline spending, combined with negative shareholders equity, keeps the business in the red longer than investors are comfortable with.
The most relevant recent development is the FDA approval of Furoscix ReadyFlow as a 10 second autoinjector for heart failure and chronic kidney disease. That decision reshapes MannKind’s profile by putting more weight on a therapy that can sit alongside Afrezza as part of a broader chronic care portfolio rather than a single product bet.
This matters for catalysts because Furoscix ReadyFlow is expected to carry better manufacturing economics than the original wearable format, which directly touches gross margin potential. The operational question for you is whether MannKind can turn this new device into steady, high quality product sales before competition, pricing pressure or sustained operating costs undercut the expected cash flow trajectory.
MannKind's Analyst Framework And What It Implies
MannKind's narrative projects US$549.9 million revenue and US$33.5 million earnings by 2029. This assumes 11.8% yearly revenue growth and an earnings swing of roughly US$77.1 million from a current loss of US$43.6 million.
Analysts are baking in a shift from loss making operations to positive profit over the next few years, with margins moving from an 11.1% loss today to a 6.1% profit level in three years. That is a big change in how each dollar of sales would flow through the income statement, especially for a business still leaning on Afrezza, Furoscix ReadyFlow and partnered inhaled therapies to do the heavy lifting.
The earnings bridge is important for you to keep front of mind. Moving from a loss of US$43.6 million to forecast income of US$33.5 million by 2029 implies the business would need to add enough gross profit to cover launch spending, pipeline work and higher selling costs, then still have cash left over. That does not say how the path unfolds year by year, but it shows the size of the gap that Afrezza pediatrics, Furoscix ReadyFlow and Technosphere royalties are expected to close.
On top of that, the analyst framework assumes the share count rises about 4.71% per year over the next three years. More shares can mute earnings per share even if absolute profit improves, so anyone building a model around MannKind needs to stress test what happens to per share metrics if dilution tracks above or below that glide path.
For this forecast to line up with current price targets, MannKind would also need to trade on a P/E of 111x those 2029 earnings, compared with a current industry level around 17.2x for US biotechs. That kind of multiple usually signals that investors are paying up for a long pipeline runway or a differentiated product set, or both. It also means any shortfall in execution can feed into a sharp reset in expectations.
Uncover why MannKind's fair value indicates a 118% potential upside to its current price. This gap could narrow quickly if sentiment shifts.
Exploring Other Perspectives
One alternate angle on MannKind focuses on Afrezza and Furoscix promotion costs as the real swing factor. The most cautious analysts were only penciling in about US$480.4 million of revenue and US$82.8 million of earnings by 2029 before this news. That sketches a more restrained narrative. Use it as a prompt to compare several viewpoints, not a verdict.
Explore 2 other MannKind fair value estimates, including one that suggests it could be worth just $4.40!
The Verdict Is Yours
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your MannKind research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for MannKind. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate MannKind's overall financial health at a glance.
Looking For More Ideas Beyond MannKind?
If MannKind has sharpened your focus on risk, reward and execution, use that same lens to scan a wider watchlist with the Simply Wall St screener and line up a few contenders side by side.
- For investors hunting for quality on sale, start by checking a curated 34 high quality undervalued stocks that pair sturdy fundamentals with subdued valuations.
- If resilience and capital protection matter most to you, narrow the field to a 29 resilient stocks with low risk scores that tend to show steadier risk profiles.
- When balance sheet strength is non negotiable, focus on companies drawn from a list of solid balance sheet and fundamentals (24 results) so you can compare MannKind to businesses with more robust finances.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com