


EN
Rivian Automotive (RIVN) Shares Moved, So What Is Behind The Attention?
How Rivian’s latest earnings and guidance reset the conversation
Rivian Automotive (RIVN) has moved back into focus after its third quarter 2026 earnings release, updated 2026 delivery guidance, and a 3.2% share price move following an analyst rating upgrade.
The automaker reported third quarter revenue of US$2,155 million compared with US$1,558 million a year earlier, alongside a net loss of US$913 million versus US$1,173 million in the same period of 2025.
For the first nine months of 2026, Rivian Automotive posted revenue of US$5,194 million compared with US$4,101 million a year earlier, with the loss narrowing to US$2,162 million from US$2,835 million.
Management also adjusted full year 2026 delivery guidance to a range of 67,000 to 70,000 vehicles compared with the previous range of 65,000 to 70,000 units, signaling a slightly tighter lower bound.
Alongside the new guidance, the firm ended the quarter with more than US$5.5b in cash. This gives investors a reference point when weighing Rivian’s ongoing spending on production, software, and partnerships.
Rivian Automotive’s latest earnings and guidance came against a choppy backdrop, with the share price rising 8.47% on a 1-day basis and 15.40% over 7 days, yet still down 32.05% on a year to date share price return and showing a 3-year total shareholder return decline of 23.22%.
The recent move to US$13.19, alongside stronger R2 commentary, updated delivery guidance, and the analyst upgrade, signals that investors are reassessing both growth potential and risk, even after a 90-day share price return that is still down 16.31%.
Capitalize on the renewed focus around Rivian Automotive by scanning our hand picked 19 high quality undiscovered gems that share strong fundamentals yet remain off most investors’ radar.After a sharp move in Rivian Automotive to US$13.19, you are looking at a stock that trades at a double digit discount to both analyst targets and intrinsic value estimates. Is that a bargain or a warning sign?
Most Popular Narrative: 27% Undervalued
Rivian Automotive’s most followed valuation story points to a fair value of $18.16 against the last close at $13.19. This frames the current discount as a bet on future execution rather than today’s earnings profile.
The Autonomy Plus package, supervised point to point driving targeted for initial rollout toward year end, and a roadmap toward eyes off and personal Level 4, together with encouraging early attach rates, create a growing base of higher margin software and subscription revenue that can add to automotive gross profit and EBITDA.
See why 259 investors see Rivian Automotive as 27% undervalued.
Result: Fair Value of $18.16 (UNDERVALUED)
Still, the whole Rivian Automotive story relies heavily on a smooth R2 production ramp and on autonomy software that is not yet fully proven or commercialized.
Find out about the key risks to this Rivian Automotive narrative.
Another View: Multiples Point To A Richer Price Tag
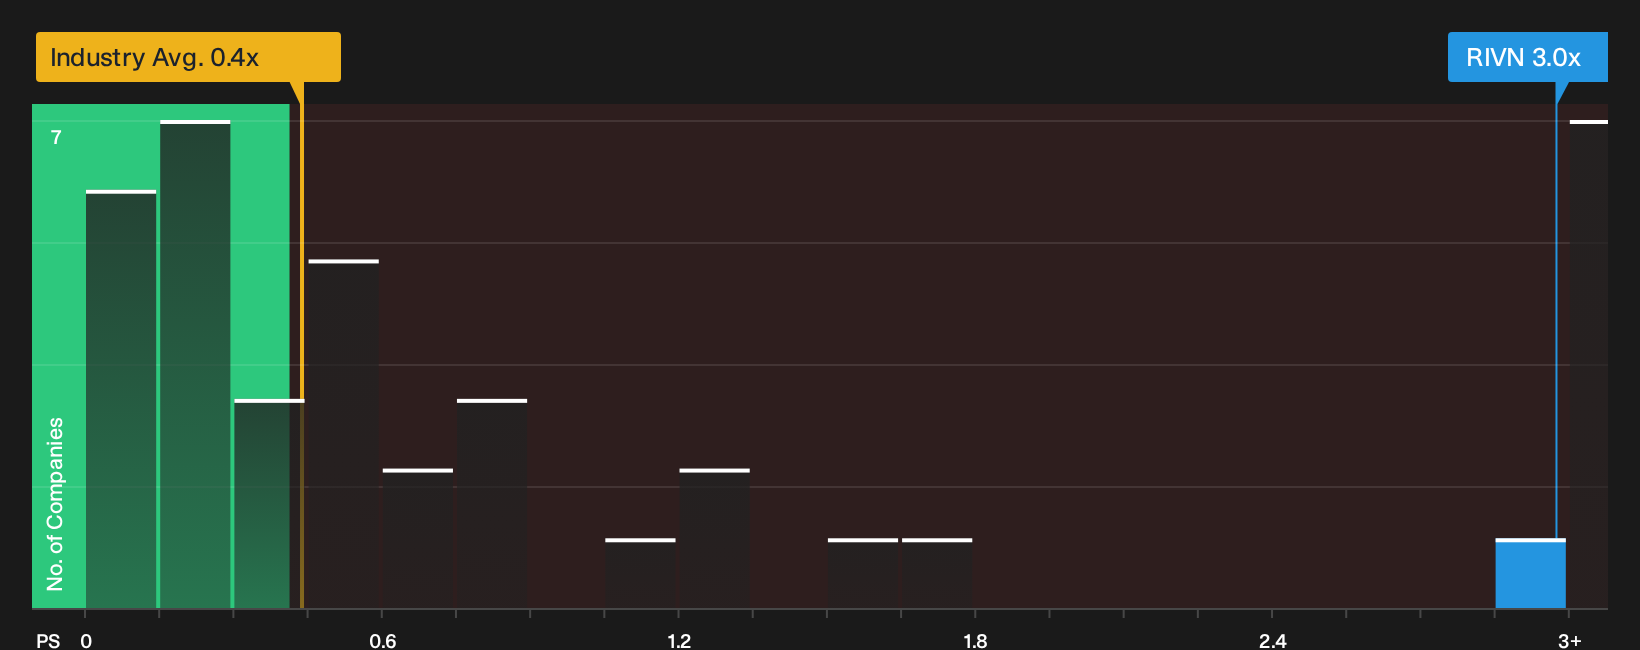
The story looks very different once you shift from future cash flows to today’s sales multiple. Rivian Automotive trades on a P/S of roughly 3x, while the US Auto group sits near 0.4x and the fair ratio is 1.8x. That gap suggests investors are already paying up heavily for the promise in R2 and software. Is that a risk you are comfortable underwriting?
To stress test that premium against hard numbers, review the valuation breakdown via the See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Mixed signals on Rivian Automotive so far. Act quickly: review both the concern list and the potential upside, then weigh the 3 key rewards and 2 important warning signs against your own judgment.
Looking for more investment ideas beyond Rivian Automotive?
Do not stop at one opportunity. Use the Simply Wall St Screener to line up your next potential moves and avoid watching others act while you stay on the sidelines.
- Target resilient balance sheets and steady fundamentals by scanning the list of solid balance sheet and fundamentals (24 results) that have the financial strength to handle tougher conditions.
- Hunt for quality at a discount by reviewing the 34 high quality undervalued stocks that pair solid fundamentals with prices that may not fully reflect their strengths.
- Prioritize capital preservation and smoother rides by focusing on the 29 resilient stocks with low risk scores that carry comparatively lower overall risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com