


EN
Is Quantum Computing (QUBT) Cheap On Book Value After Insider Selling?
Quantum Computing has seen its share price swing hard in recent years, which puts a spotlight on a simple question for anyone looking at the stock today. Is the current market value supported by what the company has built up on its balance sheet in book value terms?
- Over the past 3 years the share price has risen by roughly 7x, which puts a lot of weight on whether the underlying equity in the business can justify that kind of move.
- Heavy insider selling across major pure play quantum computing companies, including Quantum Computing, suggests management teams may be taking advantage of strong pricing, which can matter for how much book value investors are effectively paying for.
- Your read on Quantum Computing is one view; the desks covering it have another. See what analysts think Quantum Computing's shares could be worth.
The issue now is whether Quantum Computing's current share price lines up with the book value investors are buying into.
If sharp price swings around Quantum Computing have you questioning the risk, a focused stock screen can be a cleaner starting point for research than any single headline, especially with tools like 29 resilient stocks with low risk scores.
Is Quantum Computing Still Cheap on Book Value?
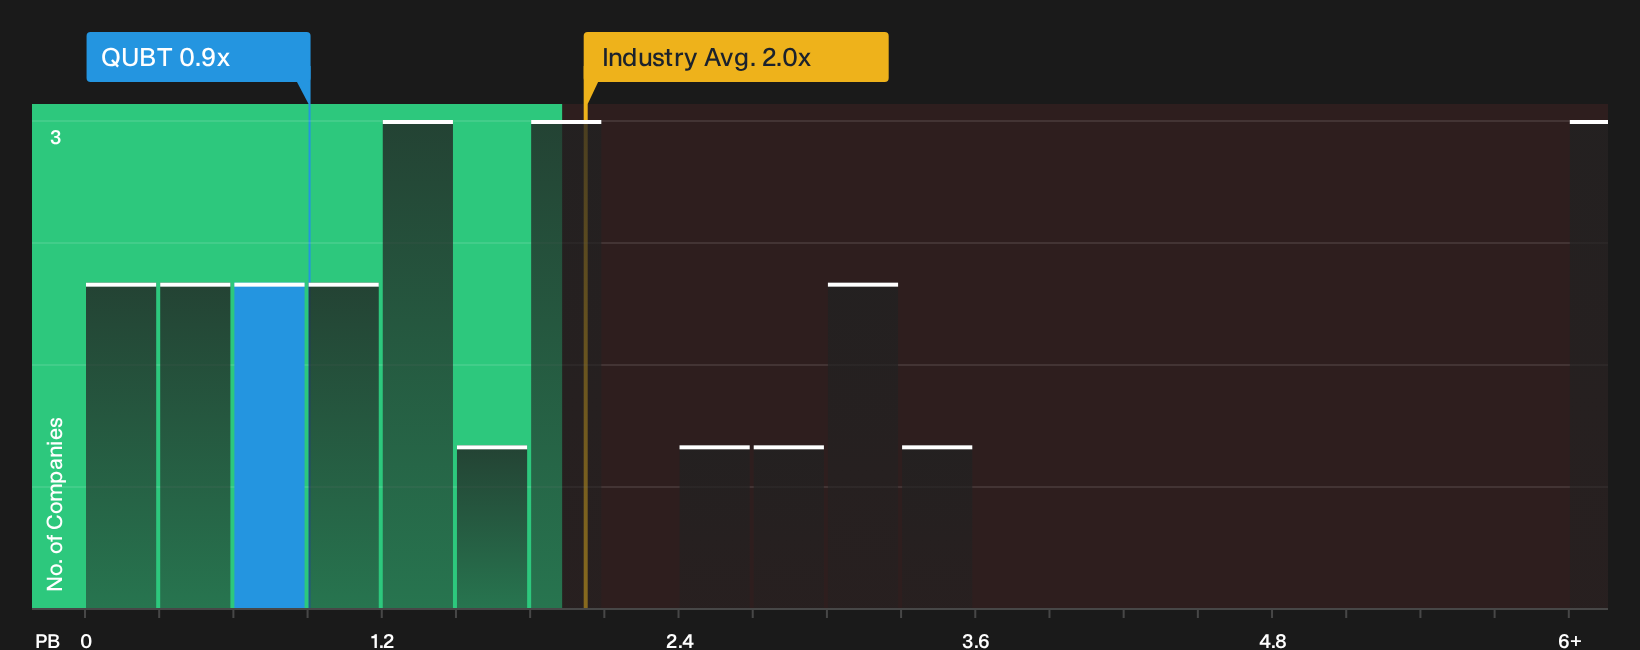
P/B fits Quantum Computing because the business is still loss making on free cash flow and investors are effectively paying for the balance sheet and future optionality rather than current profits. On this yardstick, Quantum Computing trades on a P/B of about 0.9x, compared with a Tech industry average near 2.0x and a peer group closer to 2.0x as well. That means the market price sits below the sector’s typical valuation for each dollar of equity and screens as undervalued on this single metric.
Insider selling highlighted in recent coverage matters here because it shows management reducing exposure even though the stock trades at a discount to book relative to peers. This raises questions about how durable that apparent value may be. For anyone considering the shares, the low P/B indicates that the market assigns a cautious price to Quantum Computing’s assets and future returns. You would need to weigh whether the technology roadmap and funding position justify a potential re-rating closer to industry norms. Explore the numbers behind Quantum Computing's P/B valuation.
The Quantum Computing Narrative: What Would Justify Today's Price?
Simply Wall St Narratives continue where the Quantum Computing valuation question leaves off and explain what kind of growth, margins and earnings profile would need to hold for the stock to be worth meaningfully more or less than it is today, based on clear assumptions rather than guesswork. Each one sets out a fair value as a thesis you can track over time, so you can see how the story holds up as the business develops on the Community page.
One of the top community narratives on Quantum Computing: 65% undervalued
"Expanding collaboration with ecosystem partners such as POET Technologies, membership in industry consortia and early wins with global automotive, financial and aerospace customers..."
Discover why this Narrative puts Quantum Computing at 65% undervalued.
One more angle on Quantum Computing that could change the story
Balance sheet metrics only show what Quantum Computing looks like today, while independent analyst projections sketch out where the business might be a few years from now and give you a different benchmark to compare with current pricing. Explore where analysts expect Quantum Computing to be in a few years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com