


EN
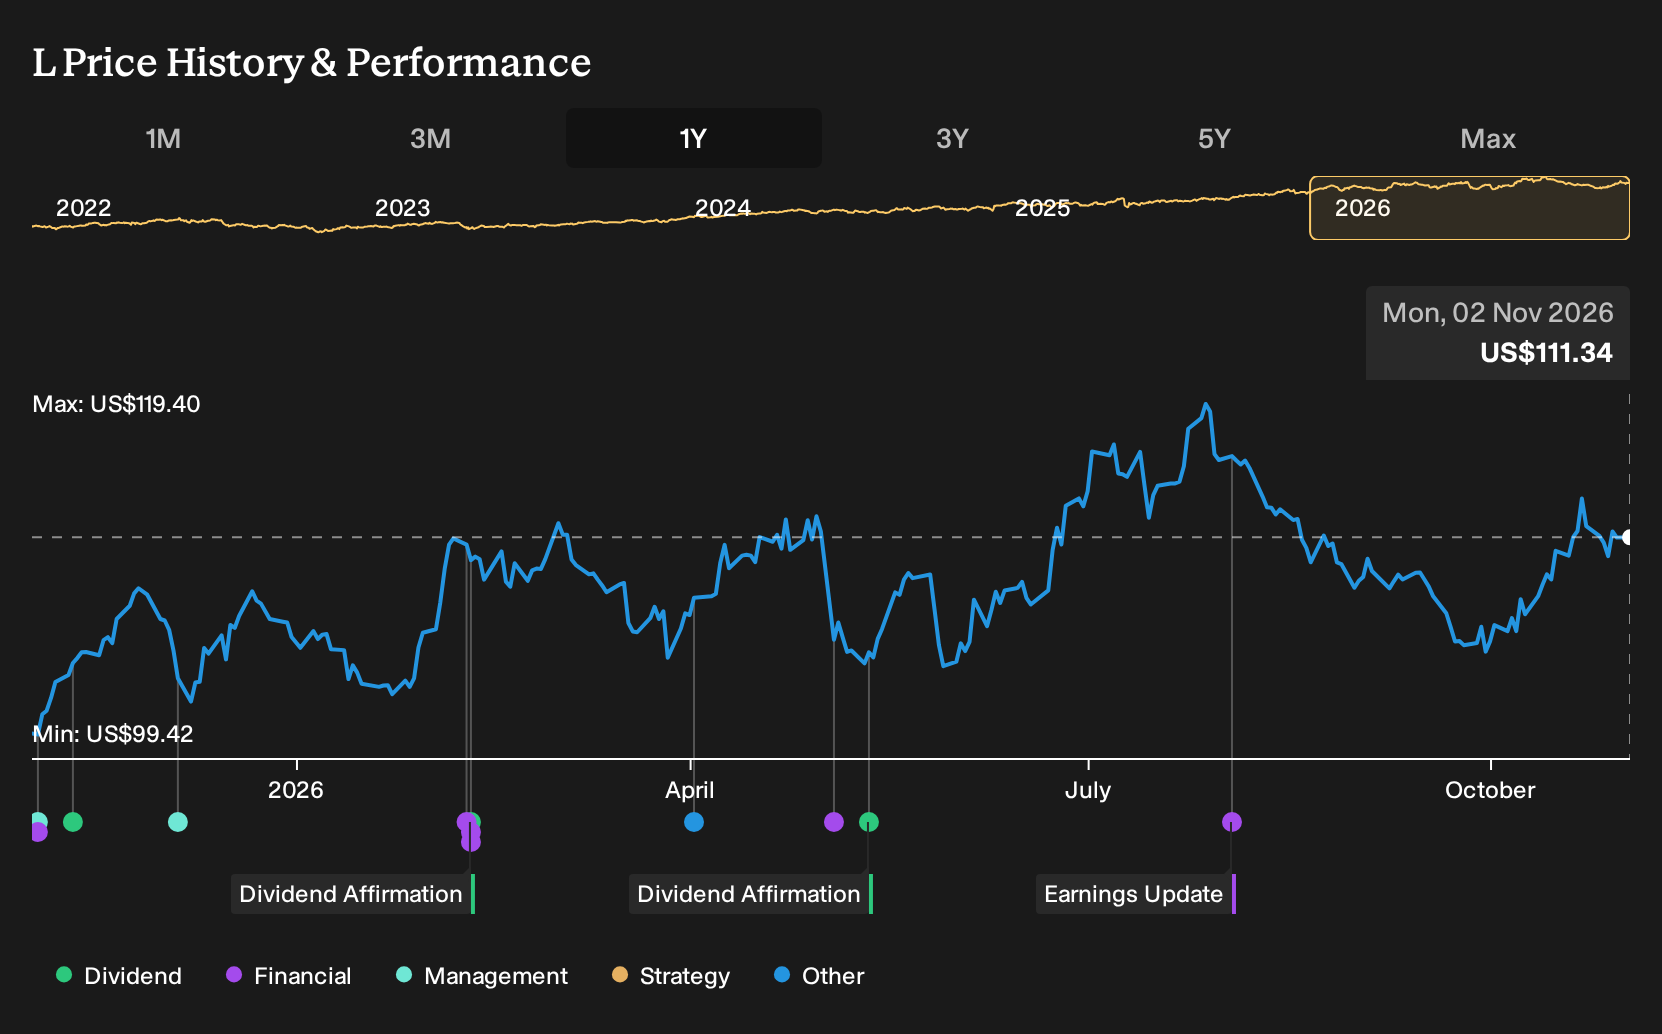
How Earnings Beat Will Impact Loews (L) Stock
- Loews Corporation reported third quarter 2026 revenue of US$4,759 million and net income of US$306 million, with earnings per share from continuing operations of US$1.50. The company also shared nine month results showing higher revenue than the prior year but lower net income and earnings per share.
- The most material swing factor came from CNA Financial, where long term care reserve updates and weaker underwriting, along with mixed results at Boardwalk Pipelines and a stronger Loews Hotels contribution, reshaped how earnings were spread across the group.
- Now the focus turns to what this earnings mix shift, especially the CNA long term care charge, might mean for Loews' investment narrative.
What Is Loews' Investment Narrative?
Owning Loews is really about being comfortable with a holding company that leans heavily on insurance through CNA, steadier fee based cash flow from Boardwalk Pipelines, and more cyclical exposure via Loews Hotels. The recent quarter put that mix in sharp focus. CNA's long term care reserve charge and softer underwriting hit profit, while hotels moved in the opposite direction and the pipeline arm worked through higher costs and one offs. In the short term, the key swing factors remain insurance reserve assumptions, underwriting discipline, and how consistently hotels can fill rooms at solid rates.
The earnings reset does not necessarily break the Loews story, but it does shift attention back to execution. Investors now have fresher data on how management reacts when one large subsidiary stumbles and another pulls more weight. The group still looks reliant on careful capital allocation across capital intensive businesses, with a P/E of 13.5x that sits below the broader US market but above the US insurance peer average. That balance between diversified profit streams and concentrated insurance risk is where the thesis really lives.
Even so, there is a structural pressure point inside Loews that could matter far more in the next downturn if ...
There's only one way to know the right time to buy, sell or hold Loews. Head to Simply Wall St's company report for the latest analysis of Loews's Fair Value.
Exploring Other Perspectives
The two fair value estimates from the Simply Wall St Community cluster tightly between US$109.41 and US$118.52, which shows a narrow band of opinions even before the latest Loews earnings release. You now have fresh information on CNA's long term care charge and mixed subsidiary results, so explore alternative views before forming your own stance.
Explore another Loews fair value estimate, including one that suggests it could be worth just $109.41.
The Verdict Is Yours
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Loews research is our analysis highlighting 2 key rewards that could impact your investment decision.
- See our latest analysis for Loews. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Loews' overall financial health at a glance.
Looking for more investment ideas beyond Loews?
If Loews has sharpened your thinking but you want a broader watchlist, use the Simply Wall St Screener to spot other companies with different risk and return profiles that still line up with your preferences.
- If capital preservation matters most to you, start with a basket of sturdier candidates through the 29 resilient stocks with low risk scores.
- For investors focused on income, scan for payout opportunities that pair yield with business resilience using the 4 dividend fortresses.
- If you want financially sound operators with room to grow, filter for stronger balance sheets and fundamentals through the list of solid balance sheet and fundamentals (24 results).
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com