


EN
Uranium Energy (UEC) Stock Looks Fully Valued As Security Council News Lands
Uranium Energy has seen a sharp reset in its share price over the past year, which puts fresh attention on a simple question for investors who care about fundamentals. Is the current market value of the stock still in step with what its balance sheet and book value suggest the business is worth?
- Over the past 5 years the share price has gained 47.8%, which makes it important to check whether that long stretch of compounding is still backed by the assets recorded on Uranium Energy's books.
- The recent creation of a National Security Advisory Council filled with former nuclear security officials may support expectations that Uranium Energy can extend its role along the uranium fuel cycle, which matters for how investors think about future capital needs and the return the company aims to earn on its asset base.
- The analysts covering Uranium Energy have run their own numbers. See what analysts think Uranium Energy's shares could be worth.
The issue now is whether Uranium Energy's current share price is adequately explained by its book value relative to the industry average.
If you want a wider view on this uranium theme while you assess Uranium Energy against its book value, a focused screen of 16 nuclear energy infrastructure stocks is a useful next step.
Does Uranium Energy Look Pricey on Book Value?
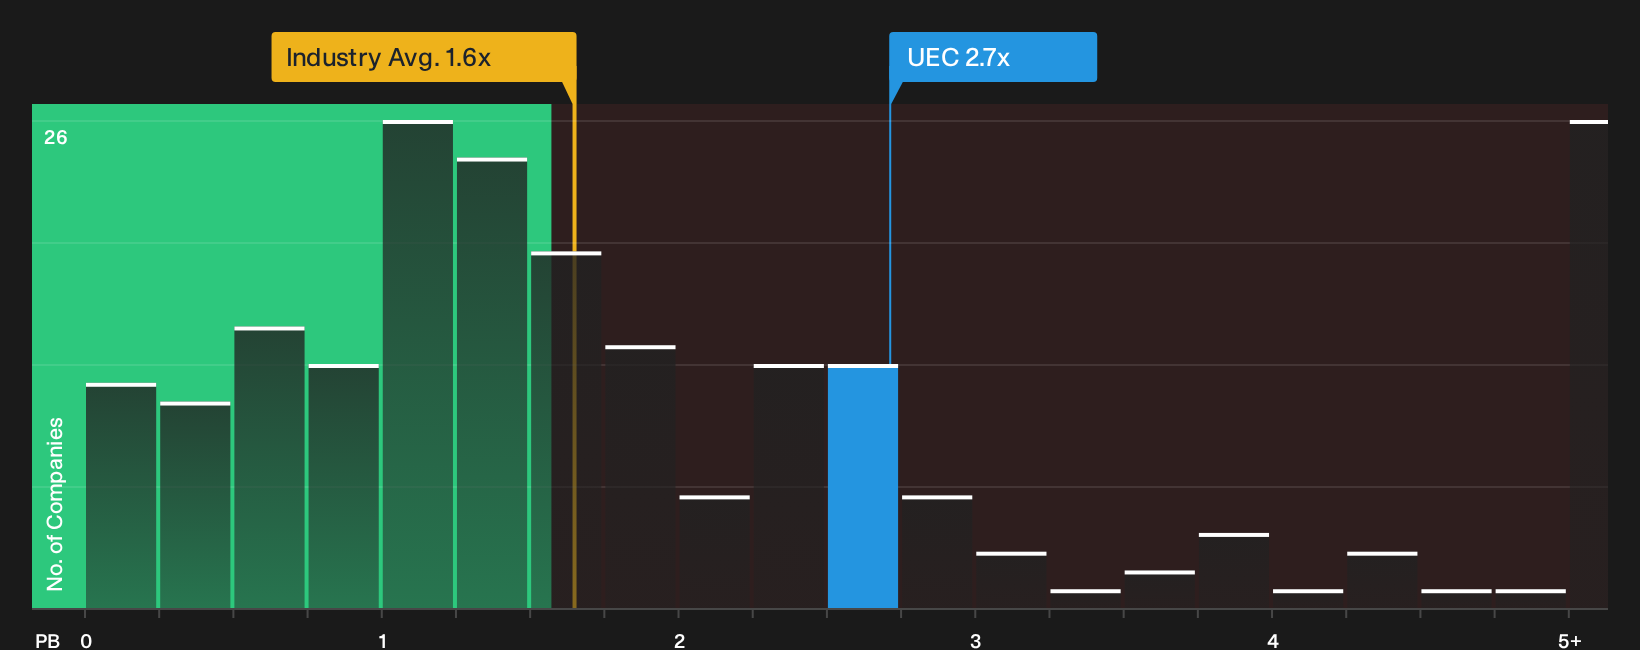
For Uranium Energy, the P/B ratio is a useful lens because the business is capital intensive and investors often anchor expectations to the value of its assets. The stock currently trades at a P/B of 2.7x, while the broader Oil and Gas industry average sits near 1.6x and the peer group clusters around 1.5x. That pricing suggests the market is willing to pay a clear premium over both the sector and similar companies for each dollar of Uranium Energy's equity on the balance sheet.
Because recent appointments to Uranium Energy's National Security Advisory Council have sharpened interest in its role along the fuel cycle, the higher P/B multiple appears more like a valuation that already reflects meaningful optimism than one that leaves clear room for disappointment. If you are weighing whether that premium is justified, the practical question is whether the asset base and future capital deployment can support the expectations implied by paying 2.7x book value rather than something closer to industry norms. Explore the numbers behind Uranium Energy's P/B valuation.
The Uranium Energy Narrative: What Would Justify Today's Price?
Narratives on Simply Wall St take the valuation puzzle around Uranium Energy and spell out which combinations of future growth, profitability and earnings power would need to play out for the stock to trade meaningfully above or below today's level. They sit on the Community page so you can line up different scenarios. Each narrative links its implied number to a clear view on how Uranium Energy's growth profile, margins and key risks might evolve, which you can revisit as fresh information arrives.
One of the top community narratives on Uranium Energy: 55% undervalued
"Launch of United States Uranium Refining and Conversion Corp positions UEC as the only American producer with both uranium and UF6 capabilities, allowing it to capture more of the nuclear fuel value chain over time..."
Discover why this Narrative puts Uranium Energy at 55% undervalued.
The Uranium Energy share price is only one piece of the decision
Before you stop at Uranium Energy's valuation, it is worth asking who is steering the business, how their incentives line up with shareholders and what that might mean for your risk. See who runs Uranium Energy and how they are paid.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com