


EN
BioMarin (BMRN) Stock May Still Be A Bargain On Fabry Licensing Deal
BioMarin Pharmaceutical has added fresh deals and pipeline assets while its stock has declined 31.2% over the past five years, which puts a sharper spotlight on whether its current market value is well supported by its sales base. With the share price at US$57.44 after a mixed run over shorter time frames, investors are asking if the recent business moves line up with what the revenue line can reasonably carry.
- The stock has fallen 31.2% over five years, which raises the question of whether the market is rethinking how much it wants to pay for each dollar of BioMarin Pharmaceutical's sales.
- New Fabry disease licensing agreements and the completed Amicus acquisition add products and potential revenue streams, which can change how investors assess the relationship between current sales and the price tag on the business.
- The analysts covering BioMarin Pharmaceutical have run their own numbers. See what analysts think BioMarin Pharmaceutical's shares could be worth.
The issue now is whether BioMarin Pharmaceutical's current share price is justified by the sales it is generating today and those investors expect it to produce over time.
If you want to stress test whether BioMarin Pharmaceutical's pricing on its sales lines up with what you see elsewhere in the market, compare it with 34 high quality undervalued stocks.
Is BioMarin Pharmaceutical Still Cheap on Sales?
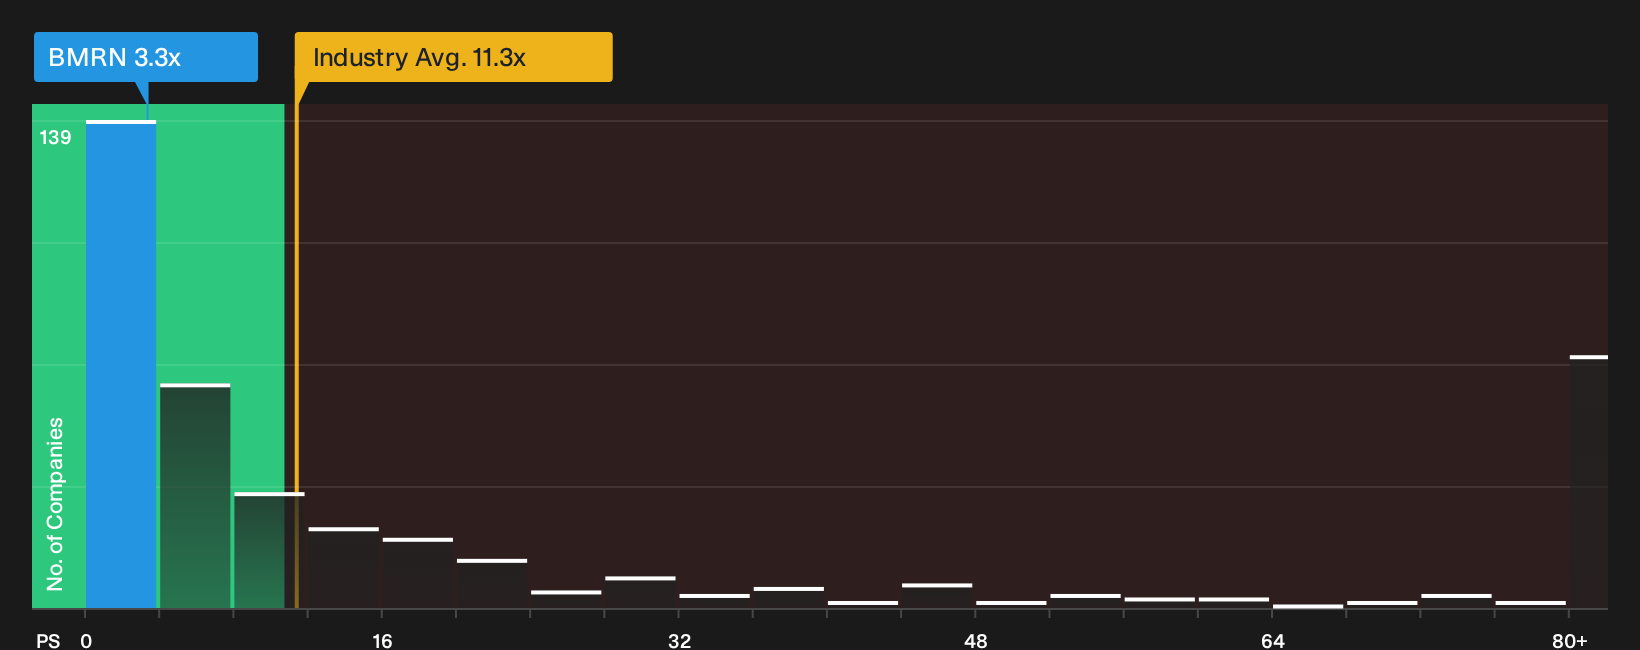
P/S fits BioMarin Pharmaceutical because the business is still building out profitability while already reporting meaningful product revenue. On this metric, the stock changes hands at about 3.3x trailing sales, which is well below the biotech sector average of roughly 11.3x and also below a peer group closer to 15.7x. That gap means you are paying fewer dollars per dollar of revenue than is common across comparable drug developers.
Because the current P/S is also lower than the multiple implied by a tailored fair-value framework that factors in BioMarin Pharmaceutical's growth profile, margins, size and risk mix, the shares screen as undervalued on this measure. Despite the Amicus acquisition and Fabry licensing deal giving BioMarin Pharmaceutical a broader rare disease portfolio, the P/S still reflects a discount to what this model suggests investors might typically pay for similar fundamentals. Explore the numbers behind BioMarin Pharmaceutical's P/S valuation.
The BioMarin Pharmaceutical Narrative: What Would Justify Today's Price?
Simply Wall St Narratives for BioMarin Pharmaceutical pick up where this valuation puzzle leaves off by spelling out which future paths for growth, margins and earnings would need to play out for the current share price to look too low or too high. Each narrative links its number to a specific view on how BioMarin Pharmaceutical's growth, profitability and risk profile might evolve, which you can then revisit as fresh information comes through the Community page.
One of the top community narratives on BioMarin Pharmaceutical: 21% undervalued
"The Amicus Therapeutics end 2025 acquisition has understandable strategic fit and adds two US- and EU-approved rare-disease therapies, accretive after closing…"
Discover why this Narrative puts BioMarin Pharmaceutical at 21% undervalued.
BioMarin Pharmaceutical's valuation still leaves one crucial issue hanging
Before you get comfortable with where BioMarin Pharmaceutical trades on sales, it is worth checking the specific risk flags our research has picked up and weighing how they might affect your thesis. Take a closer look at 4 warning signs before settling on a valuation.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com