


EN
Why Everyone Is Watching Enpro (NPO) Today
Dividend affirmation and upcoming earnings put Enpro in focus
Enpro (NPO) has approved a quarterly dividend of $0.32 per share and is set to report Q3 2026 results and host its earnings call on November 3, which is drawing fresh attention to the stock.
Recent trading tells a mixed story for Enpro. The share price has retreated about 19% over the past month and over the last quarter, even though the year to date share price return is 22.7% and the 5 year total shareholder return is 166.89%. This suggests long term holders have still seen strong compounding while short term momentum has cooled ahead of the upcoming earnings release.
Scan how Enpro compares with other industrials that have resilient balance sheets and earnings power by reviewing the hand picked list of solid balance sheet and fundamentals (24 results) in the same space.
The share price reset leaves Enpro trading well below both analyst targets and intrinsic value estimates. Is that gap pointing to mispricing, or is it simply reflecting more cautious expectations as earnings approach?
Most Popular Narrative: 30.9% Undervalued
Enpro last closed at $268.98, while the most followed narrative anchors fair value at $389.50. This frames the recent pullback as a discount to what those projections imply when using an 8.6% discount rate.
The Enpro 3.0 focus on highly engineered, mission critical sealing products with strong positions in customer specifications, alongside more than 60% of Sealing Technologies revenue coming from recurring aftermarket sales in early 2026, points to an ongoing mix shift toward businesses that structurally support company level net margins and earnings stability.
See why 2 investors see Enpro as 31% undervalued.
Result: Fair Value of $389.50 (UNDERVALUED)
Still, the bullish Enpro story can unravel quickly if semiconductor and AI capital spending cools, or if the US$60 million environmental reserve requires higher or faster cash outflows.
Find out about the key risks to this Enpro narrative.
Another View: Enpro’s rich earnings multiple
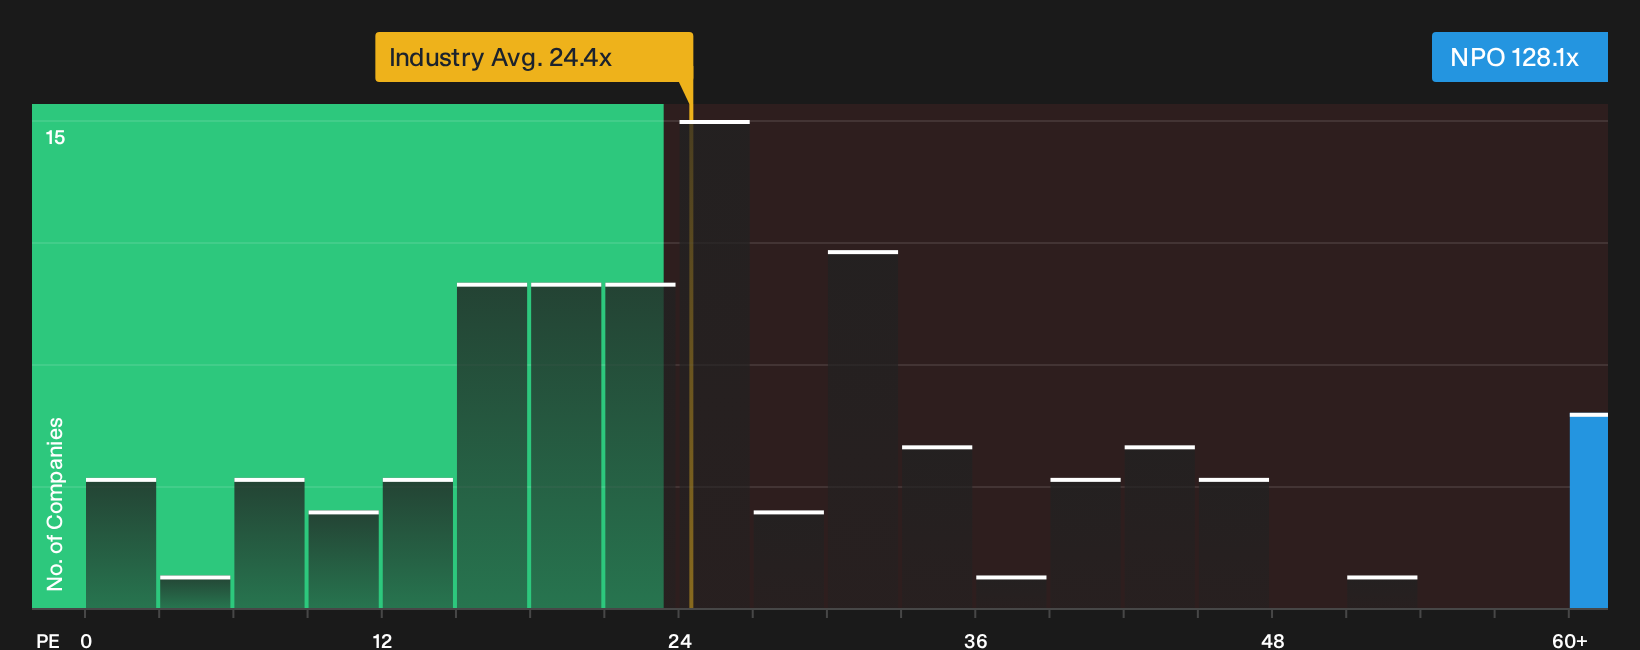
The narrative on Enpro leans on discounted cash flows and analyst targets, yet the current P/E of 128.1x tells a very different story. That is far above the US Machinery sector on 24.4x, peers on 26.8x, and even the 50.5x fair ratio that the market could move toward over time.
If sentiment drifts back toward that fair ratio, the share price would need to compress materially. This introduces valuation risk even if the business delivers on earnings forecasts. So is the recent pullback a reset that continues, or just a pause before optimism returns to this multiple?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If the mixed tone on Enpro leaves you split, move fast and review the numbers yourself so your stance is based on evidence not headlines. To weigh both the bright spots and the pressure points in one place, start with the 3 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Enpro?
Do not stop with Enpro. Broaden your watchlist quickly by testing fresh ideas through targeted stock screens that highlight quality, value, and resilience in one sweep.
- Hunt for mispriced opportunities that pair strong fundamentals with appealing valuations by scanning the 34 high quality undervalued stocks.
- Prioritise preservation of capital while still staying invested by reviewing the 29 resilient stocks with low risk scores.
- Spot potential future leaders before they hit the mainstream by working through the 19 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com