


EN
Sunoco (SUN) Secures New York Terminal Deal, Is The Stock Still Undervalued?
Why Sunoco’s latest New York terminal deal matters for investors
Sunoco (SUN) just locked in a long-term fuel terminal arrangement in New York City with Approved Oil Company, extending into the 2040s and tying the partnership directly to a key regional supply hub.
The move arrives as terminal options in the city have narrowed and reliance on dependable fuel infrastructure has become more important for distributors, independent retailers, and wholesale customers planning their long-range supply needs.
Recent trading has been choppy for Sunoco, with the share price down 3.03% on the day and 8.08% over the past month, even though the year to date share price return is 30.27% and the 5 year total shareholder return is 138.07%. This points to strong longer term momentum.
Short term weakness around the $68.69 level comes as investors absorb this new New York terminal agreement alongside the late October distribution increase. Those moves can shift how the market prices both Sunoco’s income profile and perceived infrastructure risk over time.
Scan income-focused infrastructure plays that share Sunoco’s mix of fuel distribution scale and terminal assets with our hand picked 4 dividend fortresses.
Sunoco now combines a fresh New York terminal anchor with a stock that has pulled back from recent highs. Does that mix still tilt the risk reward balance toward buyers at today’s price, once valuation is laid out?
Most Popular Narrative: 17% Undervalued
Against Sunoco’s last close at $68.69, the most followed narrative pegs fair value at $83, which implies a sizeable gap that hinges on how well the fuel and terminal roll up plays out over time.
The integration of Parkland, NuStar, TanQuid and additional bolt ons such as Alexander Oil Company and the agreed Offen Petroleum deal is creating a more geographically diverse platform across the U.S., Canada, the Caribbean, South America and Europe, which can widen volumes and support earnings resilience across different markets.
Synergy capture and operational optimisation remain central to the Sunoco playbook, with Parkland integration expected to deliver US$125 million of in year synergies in 2026 toward a targeted annual run rate above US$250 million. This directly targets higher EBITDA and distributable cash flow per unit from acquired assets.
See why 21 investors see Sunoco as 17% undervalued.
Result: Fair Value of $83 (UNDERVALUED)
Still, the Sunoco story can break if flat fuel demand forces heavier reliance on acquisitions, or if higher maintenance spending squeezes future cash available for investors.
Find out about the key risks to this Sunoco narrative.
Another View: Sunoco Through The P/E Lens
The SWS DCF model points to a large gap between Sunoco’s current price of $68.69 and an estimated future cash flow value of $260.28, which leans heavily toward an undervalued call. The picture looks more mixed when you switch to simple earnings multiples.
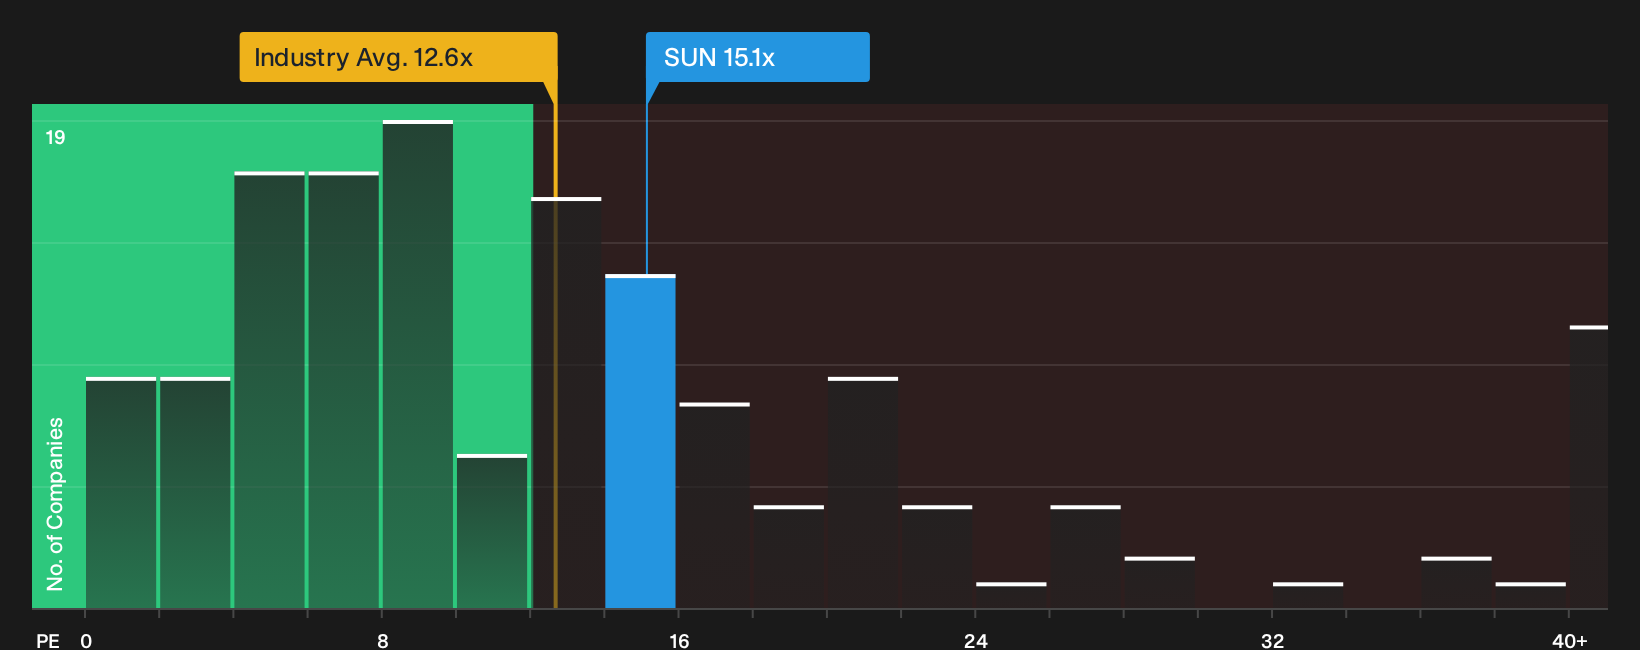
On P/E, Sunoco trades at 15.1x earnings. That is higher than the US Oil and Gas industry average of 12.6x, yet below a peer average of 23.6x and under the SWS fair ratio of 23.8x. Does that blend of slight premium to the sector but big discount to peers and fair ratio signal upside, or just justify today’s price?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals across Sunoco’s valuation, income profile, and integration risks can look confusing at first, so review the data promptly and form your own take using the 5 key rewards and 1 important warning sign.
Looking for more Sunoco investment ideas?
Ready to move beyond a single ticker and line up your next potential moves with a wider watchlist of income, value, and quality opportunities that fit your style.
- Target resilient income by scanning companies with robust payouts that echo Sunoco’s income appeal using the 4 dividend fortresses.
- Hunt for mispriced opportunities across the market and see which tickers line up with your value checklist through the 34 high quality undervalued stocks.
- Focus on financial strength first by filtering for businesses with healthy leverage and fundamentals via the list of solid balance sheet and fundamentals (24 results).
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com