


EN
LyondellBasell (LYB) Stock May Be Undervalued Following Refinery Sale News
LyondellBasell Industries has logged a strong run over the past year, and that kind of move naturally puts the spotlight on whether the current share price still lines up with what its earnings can support. With the latest headlines focused on portfolio reshaping and cash generation, the question now is how much of that story is already embedded in the valuation.
- The stock has gained 53.7% over the past year, which raises the question of how much earnings strength the market is already pricing in.
- Recent earnings and the agreed sale of the Houston refinery site for US$320.5 million may support a cleaner, more cash-focused business mix that can influence how investors value its profit stream.
- Your read on LyondellBasell Industries is one view; the desks covering it have another. See what analysts think LyondellBasell Industries's shares could be worth.
The issue now is whether LyondellBasell Industries' current price around US$66.88 is justified by the earnings power the business is generating today.
If you want context for LyondellBasell Industries' recent earnings driven rerating, it can help to line it up against other cash focused operators screened for solid balance sheet and fundamentals stocks screener (24 results).
Is LyondellBasell Industries a Bargain on Earnings?
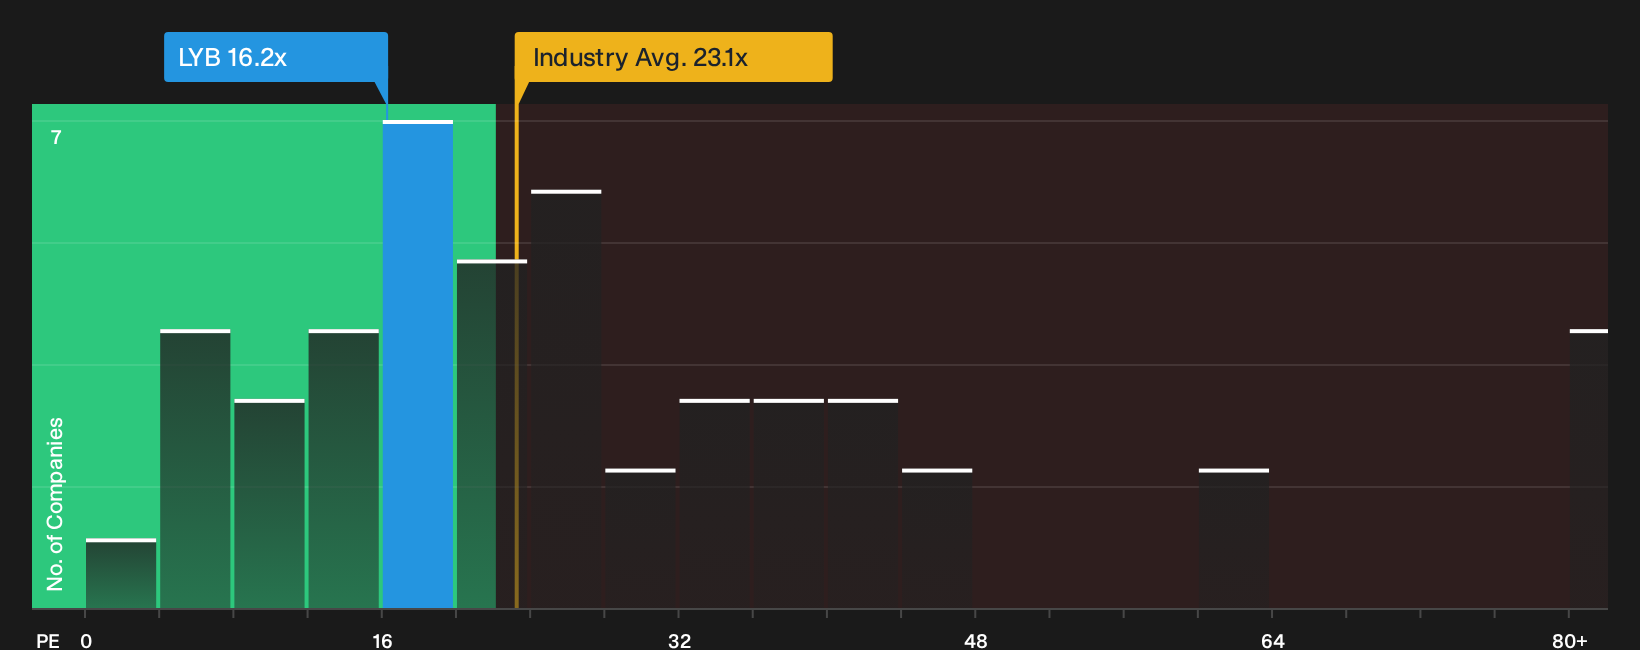
The P/E ratio gives a clean read on what you are paying for each dollar of LyondellBasell Industries earnings. On this lens, the stock trades on about 16.2x earnings, which is below the broader chemicals industry average of roughly 23.1x and well under the peer group closer to 28.4x.
Because the recent refinery sale and Q3 2026 profit print have sharpened the focus on cash generation, this discount matters. A tailored fair P/E that reflects LyondellBasell Industries mix, profitability profile and risk sits above the current 16.2x. As a result, the shares screen undervalued on this framework even after the run in the price. Despite the share price reaction to the refinery deal and results, the current P/E still prices LyondellBasell Industries below what this model suggests as a more fitting multiple for its earnings power. Explore the numbers behind LyondellBasell Industries's P/E valuation.
The LyondellBasell Industries Narrative: What Would Justify Today's Price?
Simply Wall St Narratives take that P/E gap for LyondellBasell Industries and turn it into clear, explicit assumptions about future growth, margins and earnings that would need to hold for the stock to be worth far more or far less than today’s price, and they sit on the Community page. Each Narrative treats fair value as a concrete thesis about how the business could play out over time so you can watch whether that idea holds up as new information arrives.
One of the top community narratives on LyondellBasell Industries: 19% undervalued
"The current valuation and cash generation profile together suggest that the share price reflects limited credit for tight global petrochemical supply…"
Discover why this Narrative puts LyondellBasell Industries at 19% undervalued.
One more angle on LyondellBasell Industries that could shift your view
Valuation only tells part of the story, and the latest research on LyondellBasell Industries also highlights specific risk checks that deserve a closer look before you form a firm opinion. Take a closer look at 3 warning signs before settling on a valuation.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com