


EN
Why Did WisdomTree (WT) Stock Drop Today?
Earnings beat meets market skepticism
WisdomTree (WT) just delivered third quarter results with higher revenue, higher net income, and an affirmed dividend, yet the share price slipped as investors questioned the long term payoff of its digital and tokenized push.
Over the past month, WisdomTree’s share price has fallen 16.9%, extending a 9.6% decline over 90 days. Even so, the year-to-date share price return is 61.9% and the 1-year total shareholder return is 70%, indicating that recent momentum looks softer following a strong multi-year run.
Compare WisdomTree’s digital push and recent price swing with other financials on our curated list of 19 high quality undiscovered gems that have strong fundamentals but remain under the radar.
WT now trades at $20.25, while analyst targets cluster near $25.86 and one intrinsic estimate points far higher. The question is where a reasonable fair value should anchor after this pullback.
Most Popular Narrative: 23% Undervalued
Against the last close of $20.25, the widely followed WisdomTree narrative pins fair value near $26.29. The recent pullback still sits against a higher long term anchor built on digital assets, private markets, and model portfolios.
The acquisition of Ceres Partners positions WisdomTree to continue building out private market and alternative asset exposures in areas such as U.S. farmland. Management links this to higher revenue capture and wider operating margins over time as additional committed capital is drawn and deployed.
WisdomTree's early investments in blockchain, tokenization and digital asset infrastructure are now tied to a growing base of tokenized assets, which reached about US$1.3b by September 2026. This creates a path for further product launches and fee or spread based income that can support both revenue and margin expansion.
See why 8 investors see WisdomTree as 23% undervalued.
Result: Fair Value of $26.29 (UNDERVALUED)
Still, the WisdomTree narrative can crack if tokenized assets see weaker adoption than analysts assume or if higher discretionary spending fails to lift fee revenue meaningfully.
Find out about the key risks to this WisdomTree narrative.
Another view on WisdomTree’s valuation
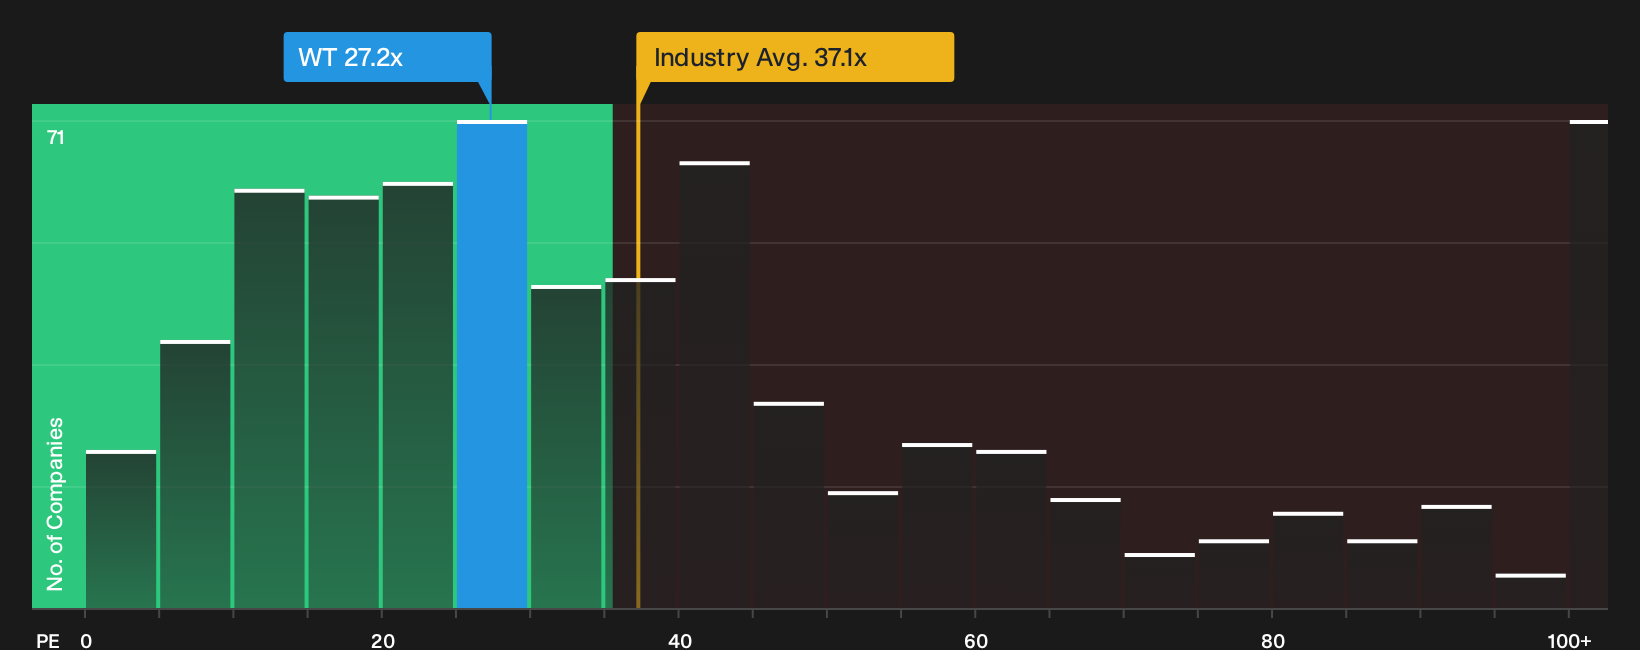
On the flip side of the bullish narrative, the market is currently paying a P/E of 27.2x for WisdomTree, while the fair ratio sits nearer 19.2x and peer averages cluster around 15.4x. That premium points to valuation risk if expectations cool even slightly. How comfortable are you paying above both peers and the fair ratio?
For a clearer sense of what the current price implies compared with peers and the fair ratio, take a look at our valuation breakdown via See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Curious whether WisdomTree’s mixed signals lean more bullish or cautious right now? Act while the data is fresh and weigh both sides for yourself with 4 key rewards and 2 important warning signs
Looking for more investment ideas beyond WisdomTree?
You have fresh context on WisdomTree. Do not stop there when other potential opportunities are only a few filters away on the Simply Wall Street Screener.
- Target companies with robust balance sheets and steady fundamentals by scanning the list of solid balance sheet and fundamentals (24 results) to filter out weaker profiles.
- Zero in on quality at a discount by running the 34 high quality undervalued stocks to see which businesses trade below their assessed worth.
- Prioritize resilience and capital protection by reviewing the 29 resilient stocks with low risk scores to highlight businesses with lower overall risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com