


EN
CRISPR Therapeutics (CRSP) Following Earnings Is The Gene Editing Story A Buying Opportunity
Earnings snapshot and what changed for CRISPR Therapeutics stock
CRISPR Therapeutics (CRSP) just released third quarter numbers that showed revenue of US$12.67 million and a net loss of US$111.44 million. This puts fresh detail behind this gene editing story for investors.
CRISPR Therapeutics shares closed at US$49.99 after the earnings release, with the 1-day share price return declining 2.78% and adding to a 30-day share price return that is down 9.81%. The 1-year total shareholder return is down 19.33%, signalling fading momentum despite earlier optimism around earnings expectations and leadership changes in recent weeks.
Compare how CRISPR Therapeutics stacks up against other high conviction biotech ideas by scanning our curated list of 34 high quality undervalued stocks with resilient cash flows and stronger balance sheets.
Bulls focus on CRISPR Therapeutics’ gene editing pipeline and analyst optimism, while bears point to ongoing losses and a falling share price. Which side does the valuation math lean toward next?
Most Popular Narrative: 43% Undervalued
CRISPR Therapeutics last closed at $49.99, while the most followed narrative anchors fair value near $87.56. This frames recent share weakness against a much higher long run earnings story.
Analysts expect CRISPR Therapeutics to build on CASGEVY revenue and move toward a multi-asset, multi-modality business as CTX310, CTX611, and zugo-cel advance through late-stage development.
The main requirement for success is effective late-stage clinical execution for CTX310, CTX611, and zugo-cel, alongside managing competition and funding increased trial spending from the current cash base and new financing tools.
See why 13 investors see CRISPR Therapeutics as 43% undervalued.
Result: Fair Value of $87.56 (UNDERVALUED)
Still, the story around CRISPR Therapeutics can unravel quickly if high cash burn persists without a clear revenue ramp, or if dilution from convertible notes accelerates.
Find out about the key risks to this CRISPR Therapeutics narrative.
Another View: What CRISPR Therapeutics’ P/B Ratio Signals
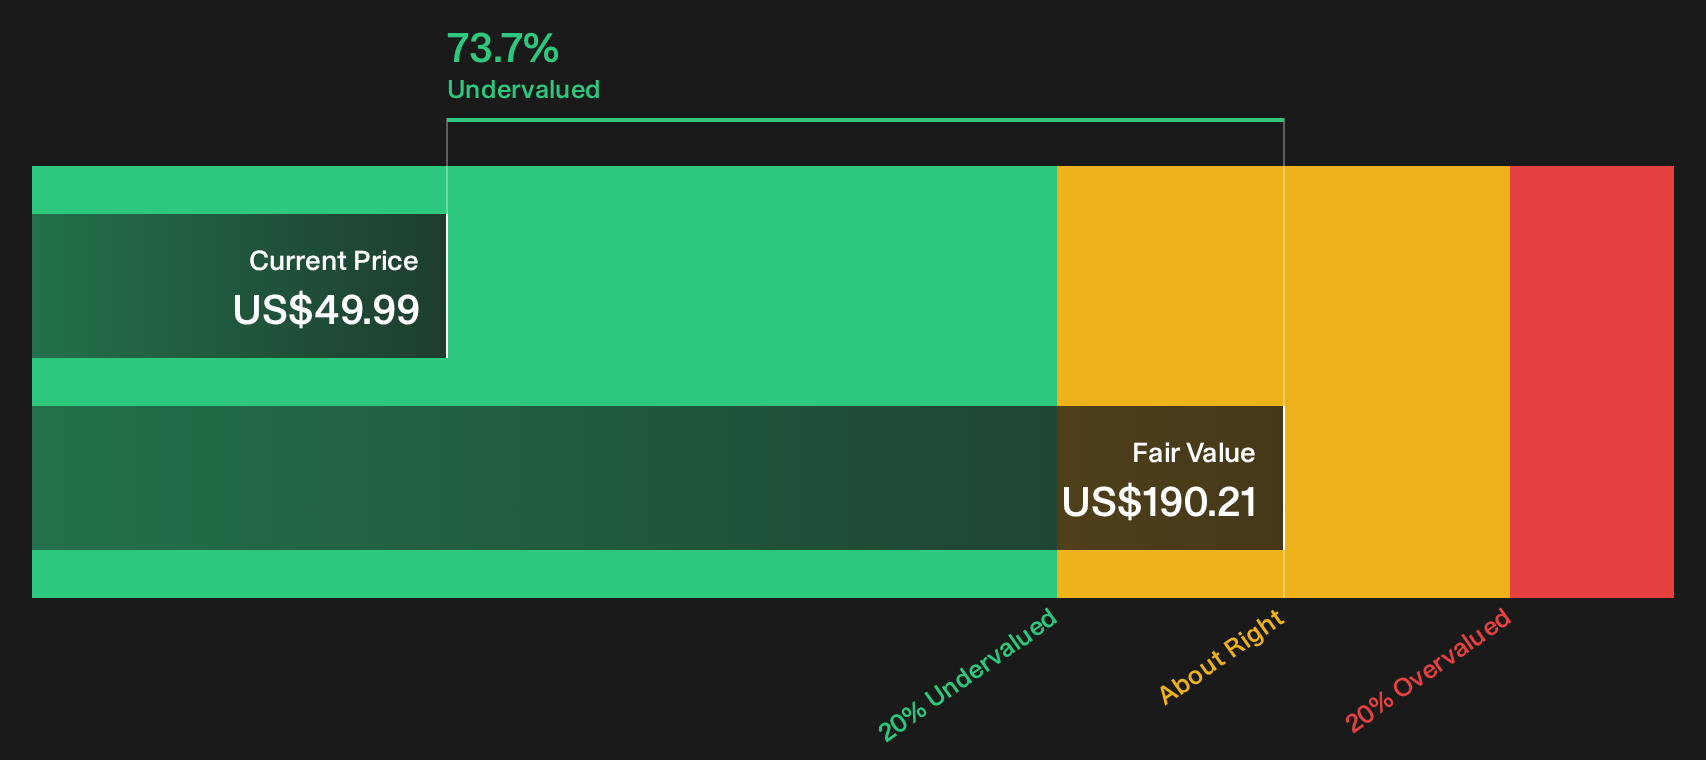
The SWS DCF model flags CRISPR Therapeutics as trading well below estimated future cash flow value, yet the simple P/B ratio tells a tighter story. At 2.8x book value versus 1.8x for the wider US biotech group, the stock carries a richer tag than the sector average. Peer comparisons look more forgiving though, since the same 2.8x sits far under the 10.5x peer average. That mix of cheap on some screens and pricey on others raises a practical question for you as an investor: Which signal feels more important, balance sheet based multiples or long run cash flow potential?
Before leaning too hard on any single number, it can help to see how that valuation was built step by step with the Look into how the SWS DCF model arrives at its fair value..
Next Steps
If the mix of pessimism and optimism around CRISPR Therapeutics feels hard to reconcile, use that as a cue to dig into the underlying numbers yourself, pressure test the bullish talking points, and then weigh those against the 2 key rewards.
Want more ideas beyond CRISPR Therapeutics?
Do not stop with a single ticker. Broader idea hunting often reveals opportunities that fit your goals better than the headline stock in front of you today.
- Hunt for potential bargains that pair quality with attractive entry points by scanning a focused list of 34 high quality undervalued stocks before prices move away.
- Anchor your portfolio around income and resilience by reviewing a targeted group of 4 dividend fortresses that aim to balance yield with staying power.
- Strengthen your watchlist with businesses built on sturdy finances by filtering through a list of solid balance sheet and fundamentals (24 results) while the market is still overlooking them.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com