


EN
Brookfield Infrastructure Partners (BIP) AI Power Narrative Keeps Fair Value In Focus
Recent return profile for Brookfield Infrastructure Partners
Brookfield Infrastructure Partners (NYSE:BIP) has drawn fresh attention after recent price moves, with the partnership showing a 2.1% gain over the past day and 3.7% over the past week, while the past 3 months reflect a 4.5% decline.
Recent trading has tilted positive for Brookfield Infrastructure Partners, with the share price moving up to US$38.12 and short term momentum improving. The 1 year total shareholder return of 16.65% and 3 year total shareholder return of 64.63% point to a stronger longer run record.
Scan similar infrastructure opportunities by reviewing the hand picked 43 power grid technology and infrastructure stocks that could benefit from capital flowing toward essential energy and transport assets alongside Brookfield Infrastructure Partners.
Brookfield Infrastructure Partners has a long record of owning essential assets, yet the recent push to around US$38 puts a different issue front and center. Is that resilience already fully reflected in the current price, or not?
Most Popular Narrative: 19% Undervalued
Brookfield Infrastructure Partners is trading at $38.12 against a widely followed fair value estimate of $47.10, which frames the recent rebound as only a partial catch up to that narrative. The key question for you is whether the current price already reflects the AI focused data and power projects that underpin this valuation, or whether that story still has room to play out.
Expansion of Brookfield Infrastructure Partners’ behind the meter power platform, including the increase in its Bloom Energy framework from US$5b to US$25b of planned capex and more than 230 MW of secured projects, points to a growing pipeline of AI focused power solutions that can support future revenue and margin contribution.
See why 36 investors see Brookfield Infrastructure Partners as 19% undervalued.
Result: Fair Value of $47.10 (UNDERVALUED)
Still, the Brookfield Infrastructure Partners story can be knocked off course if AI power and data projects face tighter permitting, or if expected contract margins fall short.
Find out about the key risks to this Brookfield Infrastructure Partners narrative.
Another View: Multiples Paint A Richer Picture For Brookfield Infrastructure Partners
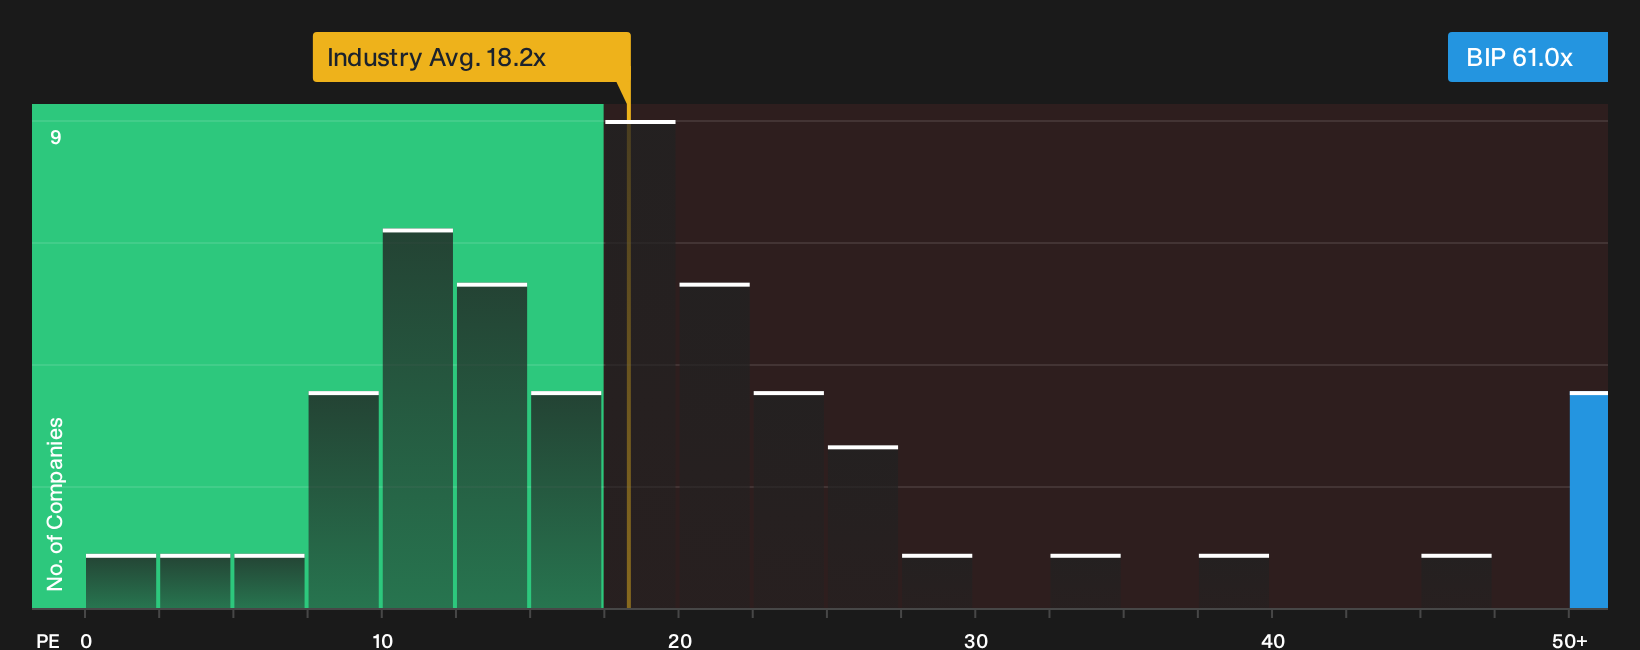
On one hand, Brookfield Infrastructure Partners screens as undervalued against a US$47.10 fair value narrative. On the other, the current P/E of 61x is far higher than the global Integrated Utilities average of 18.2x and well above the 23.7x peer group figure, which points to a much fuller price tag than the fair value story alone suggests.
That gap between cash flow based upside and a steep earnings multiple leaves a simple question for you: Is the stock priced for too much AI promise, or is the high P/E just the cost of owning a long lived infrastructure platform tied to these projects?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If this mix of optimism and concern around Brookfield Infrastructure Partners feels familiar, treat it as a prompt to inspect the underlying numbers yourself, weigh both sides of the story, and ground your view in the 3 key rewards and 3 important warning signs.
Looking for more Brookfield Infrastructure Partners style investment ideas?
You have weighed Brookfield Infrastructure Partners carefully. Do not stop there. Broaden your watchlist now so you are not relying on a single story, and give yourself more options when conditions change.
- Target resilient value by scanning a curated 34 high quality undervalued stocks that highlights companies combining stronger fundamentals with prices that sit below their assessed worth.
- Build a steadier income stream by reviewing a focused 4 dividend fortresses that filters for higher yielding payouts backed by robust financial profiles.
- Protect your downside by assessing a refined 29 resilient stocks with low risk scores that concentrates on businesses with sturdier balance sheets and lower overall risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com