


EN
AeroVironment (AVAV) Could Be 18% Overvalued After Space Force Contract Setback
AeroVironment (AVAV) is back in focus after the U.S. Space Force halted a planned US$1.7b contract tied to its BlueHalo acquisition and reopened the bidding to rival suppliers.
Recent trading tells a story of fading momentum for AeroVironment. The share price is down 12.6% over the past month and 27.2% over 90 days, contributing to a year to date share price decline of 52% and a 1 year total shareholder return that has fallen 66.5%.
Spot fresh defense and robotics opportunities by scanning the hand picked 95 robotics and automation stocks that could benefit as investors reassess contract risk and growth potential beyond AeroVironment.The contract shock and share price slide raise a simple tension. Are investors finally adjusting AeroVironment to its contract risk, or has sentiment moved further than the underlying business justifies, as the valuation now suggests?
Most Popular Narrative: 18% Overvalued
AeroVironment last closed at $123.08, while the most followed narrative on Simply Wall St pegs fair value at $103.94 per share. This suggests the stock trades above that anchor level but still inside a broader debate about contract risk and future execution.
The prior call used inflection-point language as anticipatory framing: things are approaching an inflection point. The current one uses it retrospectively, to describe something that has already arrived. Nawabi deploys the phrase in relation to LOCUST specifically at least five times across prepared remarks and Q&A: “We are at an inflection point.” “This is an inflection point.” “I think we are at a similar inflection point.” The density of the phrase is notable because inflection points, by definition, are singular. When a company declares one, the narrative utility of the declaration diminishes with each repetition. By the fifth instance, it functions more as tonal reinforcement than analytical signal.
See why 11 investors see AeroVironment as 18% overvalued.
According to LunaRodas, who built this narrative around AeroVironment’s Q1 fiscal 2027 call, the valuation gap is less about a single contract and more about how management language has shifted from “competing” to “defining moment” across programs like EHEL, LOCUST and Titan. The quote above is picked out as a key tell because it highlights how repeated use of the phrase “inflection point” can signal confidence while also raising questions about how much optimism is already assumed in today’s share price.
That same narrative also weighs the firm’s guided path to free cash flow, where leadership reiterates that fiscal 2027 is expected to be a negative free cash flow year as capex for capacity expansion ramps. For an investor looking at the current loss of $202.8m against revenue of $2.0b, the combination of large funded backlog, new contracts and a planned period of cash burn becomes central to judging whether the current premium to the $103.94 fair value estimate is justified.
On top of that, the Simply Wall St model backing this fair value uses projected cash flows and discounting assumptions that lead to AeroVironment scoring 4 out of 6 on valuation checks. The narrative flags that this is not a clean “cheap or expensive” story. On one side sits a stock that has fallen 66.5% over 12 months. On the other side is a business that is still unprofitable, has seen losses increase over the past 5 years at 35.2% per year, and yet is expected by analysts to move into profitability over the next 3 years.
The same narrative also sets today’s valuation against management’s compensation and governance record. Wahid Nawabi’s total compensation of $14.13m is above the $8.41m average for similar sized US companies, while the group remains loss making with a negative return on equity of 4.61%. At the same time, the board is described as both experienced and largely independent, which can matter for investors trying to judge whether oversight is strong enough when capital spending and contract concentration risks are front and center.
Finally, LunaRodas frames the current share price as sitting between two valuation anchors. One is the $103.94 narrative fair value that implies AeroVironment is about 18% overvalued. The other is Simply Wall St’s DCF output in the statements data that points to a future cash flow value of $368.50 per share, which would indicate the market price is well below that longer term cash flow estimate. For readers, the gap between those two lenses is the real signal because it underlines just how sensitive any verdict is to assumptions about contract durability, margin improvement and how quickly losses can narrow.
Result: Fair Value of $103.94 (OVERVALUED)
Still, the AeroVironment narrative could reset quickly if the reopened US$1.7b Space Force opportunity leans toward competitors, or if goodwill and control issues resurface publicly.
Find out about the key risks to this AeroVironment narrative.
Another View: DCF Signals A Very Different AeroVironment Story
The Simply Wall St DCF model tells a very different story for AeroVironment. On that framework, the current price of $123.08 trades well below an estimated future cash flow value of $368.50, which frames the stock as deeply undervalued rather than 18% overvalued. Which set of assumptions do you trust more?
Look into how the SWS DCF model arrives at its fair value.
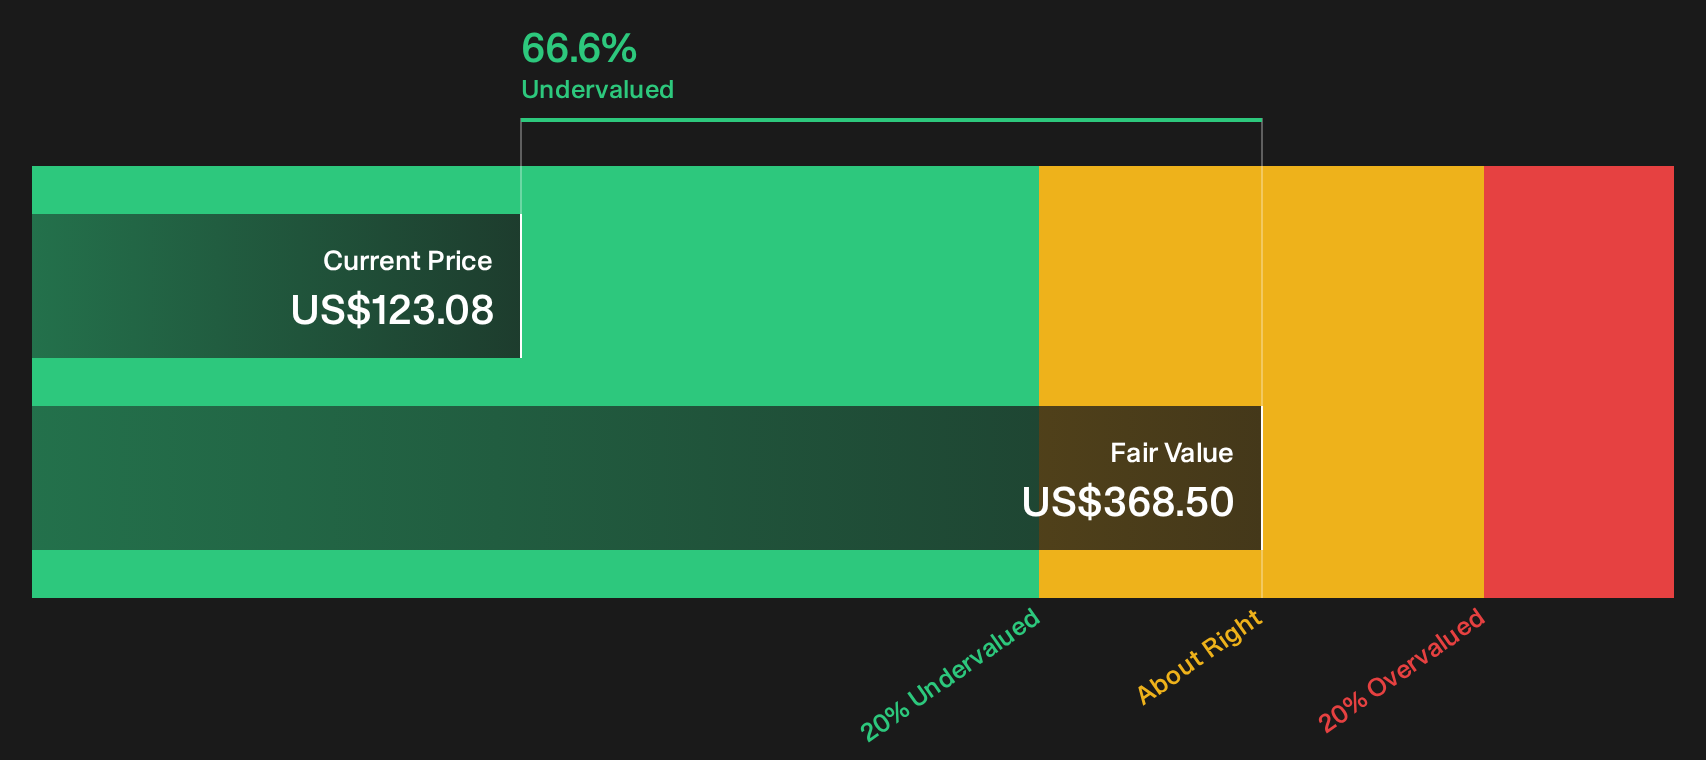
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out AeroVironment for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 34 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
If the AeroVironment story so far feels mixed, that is the point. It is exactly why acting quickly to test the numbers yourself matters. To see what optimistic investors are focusing on right now, review the 2 key rewards.
Looking for more AeroVironment investment ideas?
If AeroVironment has sharpened your focus on contract risk, cash flow and valuation gaps, broaden your watchlist with a few targeted screeners that surface different types of opportunities.
- Start building a watchlist of resilient candidates by scanning a 29 resilient stocks with low risk scores that already filters for lower risk scores and sturdier profiles.
- Hunt for potential mispricings by using a 34 high quality undervalued stocks that blends balance sheet strength with quality cash flows to spotlight possible bargains.
- Aim for staying power and income together by reviewing a 4 dividend fortresses where higher yields and durability sit side by side.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com