


EN
Clearway Energy (CWEN) Heads Into Q3 Earnings With An Undervalued Narrative In Play
Clearway Energy (CWEN) is back in focus as Wall Street prepares for its Q3 2026 report, with expectations pointing to lower earnings even as projected revenue is anticipated to be higher than in the prior year.
Recent trading has turned more upbeat for Clearway Energy, with a 1 month share price return of 15.54% and a 1 week gain of 7.93%, culminating in a 1 day move of 5.84% to US$33.90, even though the year to date share price return is slightly negative. That near term momentum sits alongside a 1 year total shareholder return of 9.77% and a very large 3 year total shareholder return of 79.69%, which hints that investors have been re-rating the business over time as earnings expectations and perceived risks shift around each quarterly update.
Scan the renewables space for other grid-focused operators that could echo Clearway Energy's recent momentum by checking the hand-picked 43 power grid technology and infrastructure stocks alongside this Q3 earnings setup.
Bulls see Clearway Energy’s recent jump and expanding clean power footprint as a rerating in motion. Bears point to softer earnings expectations. Which story do the current valuation markers lean toward?
Most Popular Narrative: 16% Undervalued
At a last close of $33.90 against a narrative fair value of about $40.43, Clearway Energy is framed as undervalued. That gap is anchored in long-term contracted projects and data center linked demand rather than short term earnings noise.
Rising long-term power demand from data centers and large technology customers, including multi decade PPAs with hyperscalers and Google, supports a larger contracted asset base that can increase revenue visibility and support future earnings growth.
Expansion of late stage wind, solar and storage projects, with 100% of 2026 and 2027 vintages already commercialized and a 2028 to 2029 pipeline larger than what is needed for internal CAFD targets, gives the company multiple ways to add contracted capacity that can lift CAFD and support dividend coverage.
See why 10 investors see Clearway Energy as 16% undervalued.
Result: Fair Value of $40.43 (UNDERVALUED)
Still, the narrative can break if data center power demand underwhelms expectations, or if policy shifts slow project completions and weigh on future contracted cash flows.
Find out about the key risks to this Clearway Energy narrative.
Another View: Clearway Energy Looks Expensive On Earnings
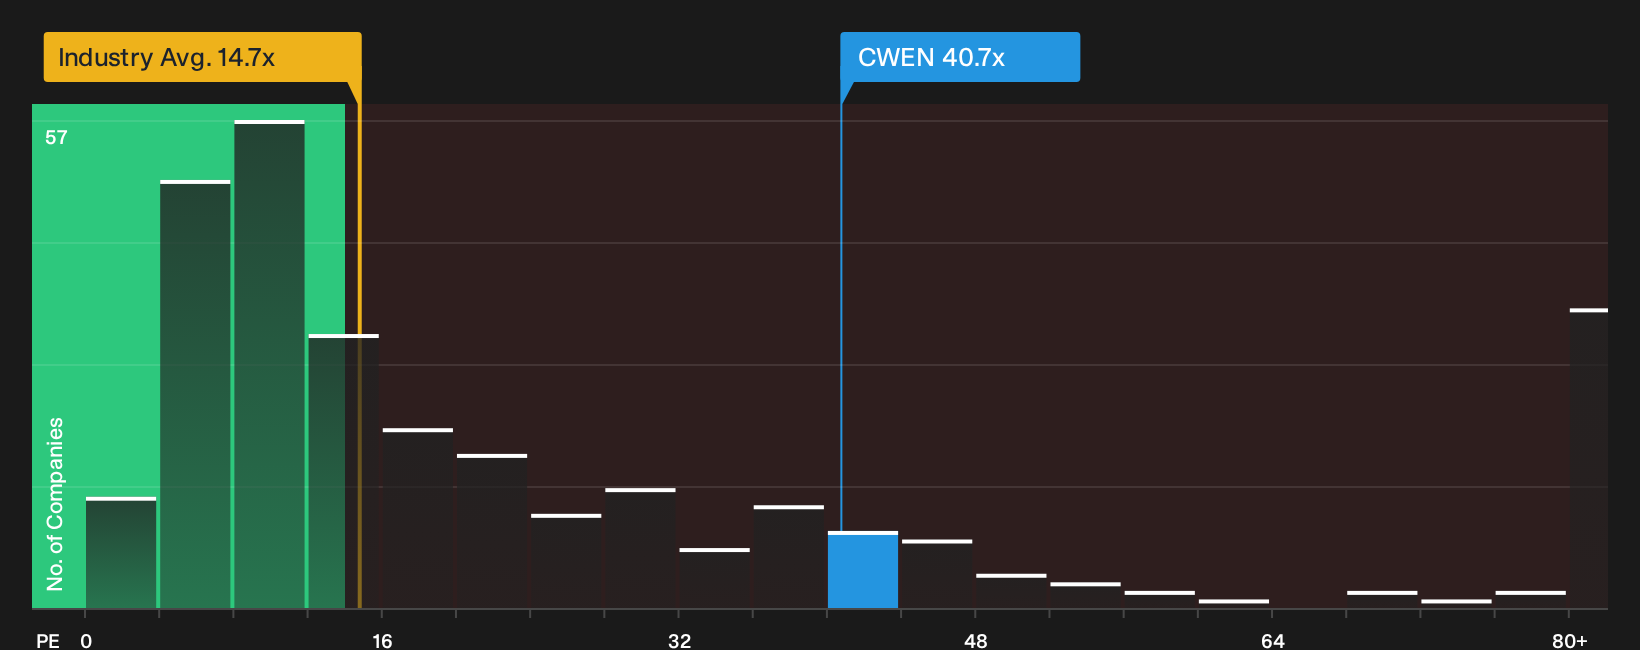
The narrative fair value paints Clearway Energy as undervalued, yet the current P/E of about 40.7x tells a different story. That level sits well above the global renewable energy group at 14.7x and above peers near 31x, and it also exceeds a fair ratio of 26.5x. If the market drifts closer to that fair ratio, investors would be paying a high price today for less earnings support. Which signal do you trust more: the growth story or the multiple you are being asked to pay?
For a closer look at how this earnings multiple stacks up against industry norms and where the fair ratio sits, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages on Clearway Energy can feel messy, yet this is exactly when acting quickly and reviewing the numbers yourself matters most. To weigh both the upside story and the concerns flagged by other investors, start with the 2 key rewards and 3 important warning signs.
Looking for more Clearway Energy style investment ideas?
If Clearway Energy has sharpened your focus, do not stop here. Broaden your watchlist now and give yourself more options before the next round of earnings moves.
- Target potential mispricings by scanning the 34 high quality undervalued stocks that pair strong fundamentals with what could be discounted market expectations.
- Lock in income focused opportunities by reviewing the 4 dividend fortresses that combine higher yields with resilient payout profiles.
- Reduce portfolio stress and smooth returns by filtering for the 29 resilient stocks with low risk scores that show stronger balance sheets and fewer red flags.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com