


EN
Piper Sandler (PIPR) Stock May Be Overvalued Following New $200 Million Buyback
Piper Sandler Companies has delivered a near 3 year share price gain that is hard to ignore, even after a weaker run this year. The obvious question now is whether the current valuation can be explained by its earnings power. Recent corporate updates and capital return plans give investors more information to work with, but they also sharpen the focus on what the market is really paying for.
- Piper Sandler Companies has returned about 98.4% over the past 3 years, which puts real pressure on today’s price to be matched by the company’s underlying profit trajectory.
- The new US$200m share repurchase program, combined with ongoing dividends, can concentrate earnings per share over time and signals that management is comfortable committing cash to shareholders rather than reserving it for other uses.
- There is a second opinion on Piper Sandler Companies worth weighing. See what analysts think Piper Sandler Companies's shares could be worth.
The issue now is whether the earnings behind Piper Sandler Companies are strong and reliable enough to justify the current share price that reflects this history of returns and capital actions.
If you are weighing Piper Sandler Companies against other ways to play this theme of earnings power and capital returns, it can help to compare it with companies in the 34 high quality undervalued stocks.
Has Piper Sandler Companies Run Too Far on Earnings?
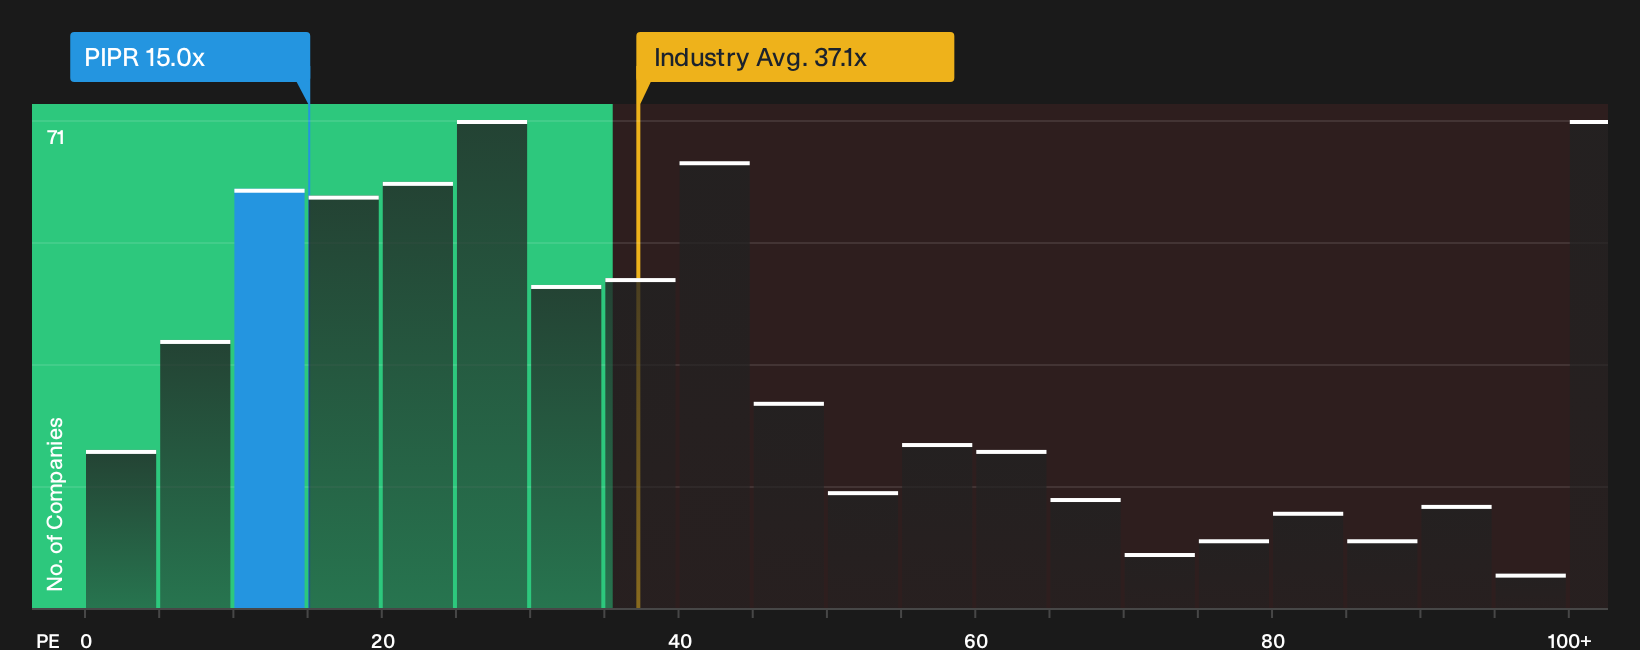
P/E fits Piper Sandler Companies because earnings remain a key yardstick for capital markets firms where profit swings can quickly reshape investor expectations. The stock trades on a P/E of about 15.0x, which sits below both the Capital Markets sector average of roughly 37.1x and a peer group closer to 20.6x. That gap shows that the market is not assigning Piper Sandler the same earnings multiple as many listed competitors.
The internal fair multiple model, which blends the company’s profitability record, risk profile and sector context, points to a lower P/E than where the shares change hands today. On this lens the stock screens as overvalued. Because the latest Q3 2026 update reported strong results alongside a sizeable new US$200m buyback, the current P/E appears more like a full price supported by recent momentum rather than a clear discount versus its tailored benchmark. Explore the numbers behind Piper Sandler Companies's P/E valuation.
The Piper Sandler Companies Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where this valuation puzzle for Piper Sandler Companies' P/E leaves off, by spelling out which paths for future growth, margins and earnings would need to play out for the stock to end up worth materially more or less than it is today on the market. Rather than relying on a single multiple or model line, each Narrative lays out the assumptions behind its estimate of fair value so you can track those inputs against actual results as they arrive.
One of the top community narratives on Piper Sandler Companies: 15% undervalued
"Recent research on Piper Sandler Companies points to a more mixed setup for the stock..."
Discover why this Narrative puts Piper Sandler Companies at 15% undervalued.
An unanswered piece of the Piper Sandler Companies puzzle
Today's snapshot of Piper Sandler Companies only shows what the market pays for current earnings, while professional analysts publish their own multi year view that may support or challenge that picture. Explore where analysts expect Piper Sandler Companies to be in a few years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com