


EN
Power Solutions International (PSIX) Puts Valuation In Focus After Power Boost 2030 Launch
Power Solutions International (PSIX) has refreshed its corporate logo and rolled out its Power Boost 2030 vision. This signals a PSI 2.0 push toward technology-focused power solutions for data centers and mission-critical infrastructure.
Set against that Power Boost 2030 rollout, Power Solutions International’s 90 day share price return of 32.85% points to building momentum, even though the year to date share price return is down 24.74% and the 1 year total shareholder return has declined 48.01% from an exceptionally strong multi year base.
Scan how Power Solutions International’s Power Boost 2030 pivot compares with other potential beneficiaries of data center demand by reviewing the hand picked 53 AI infrastructure stocks in one place.
Power Solutions International now trades at a sizeable discount to both analyst targets and one estimate of intrinsic value after that sharp 90 day rebound. The key question is whether this gap represents a valuation opportunity or a sign that the market still places greater weight on its own caution.
Most Popular Narrative: 4.7% Overvalued
The most widely followed narrative pegs Power Solutions International’s fair value at $44.24, a touch below the last close at $46.31. This frames the current rebound as slightly ahead of that intrinsic estimate while the market reassesses the Power Boost 2030 story.
The most recent financial reports, ending in the second quarter of 2026, show that structural frictions stifling the cash conversion cycle have been largely eliminated. The company has aggressively reduced its debt ratio, reduced its heavy reliance on working capital loans, and is approaching a net cash-neutral position.
See why 13 investors see Power Solutions International as 5% overvalued.
Result: Fair Value of $44.24 (OVERVALUED)
Still, the whole thesis around Power Solutions International leans heavily on data center capital spending and smooth Wisconsin ramp execution, and either could easily disappoint.
Find out about the key risks to this Power Solutions International narrative.
Another Look At Power Solutions International’s Valuation
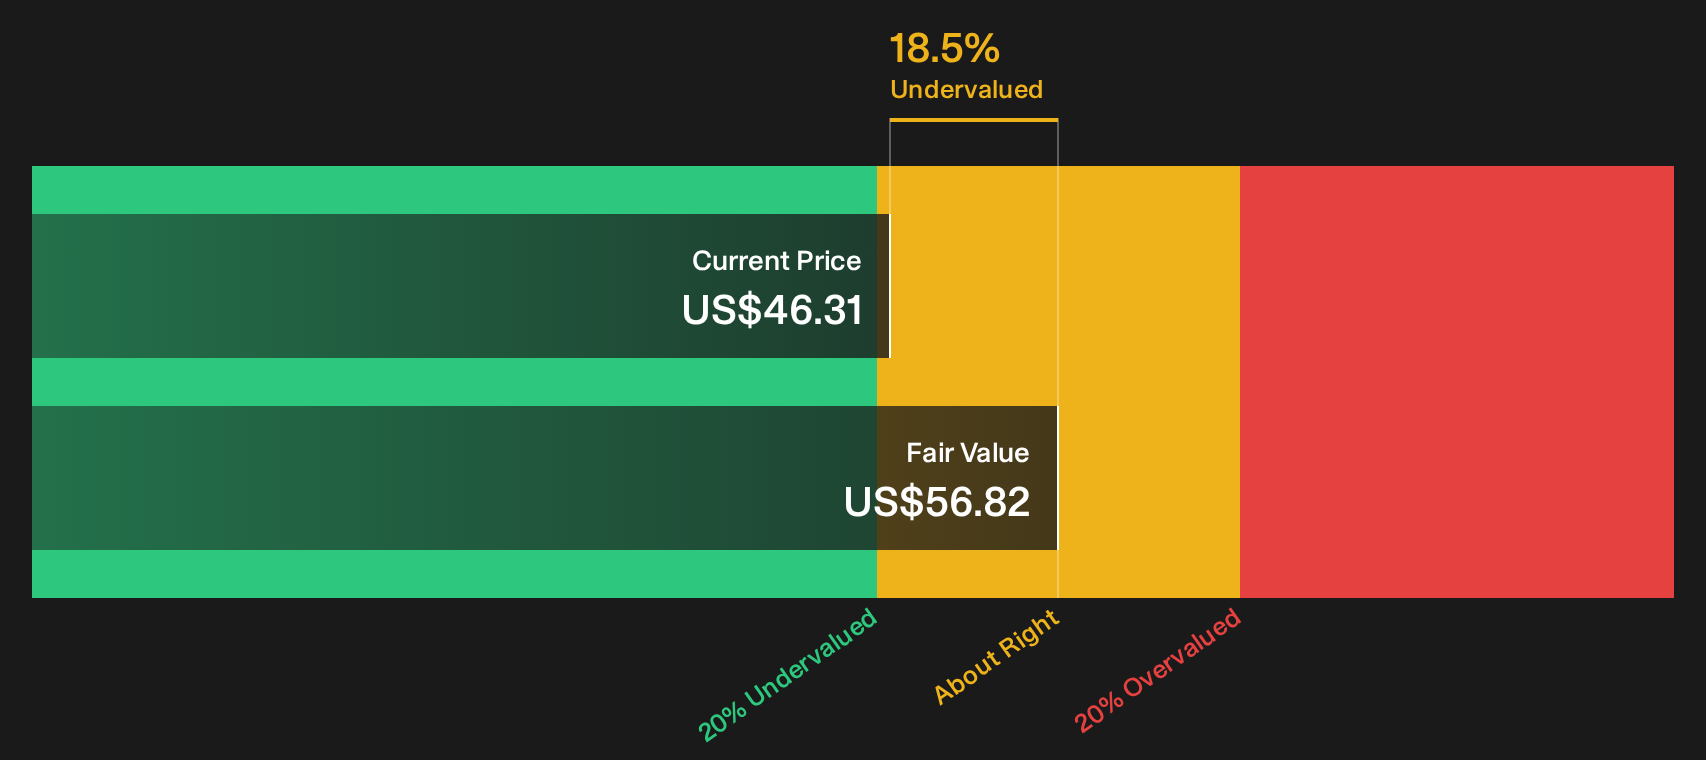
The narrative-led fair value for Power Solutions International paints the stock as 4.7% overvalued at $44.24, just under the current $46.31. Our DCF model tells a different story and puts future cash flows at $56.82 per share, which screens as undervalued instead. Which signal do you trust more: sentiment or cash flow math?
Look into how the SWS DCF model arrives at its fair value.
Next Steps
Mixed signals on Power Solutions International so far, right, with both risks and potential upsides on the table. Move quickly, review the data, and then weigh the 4 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Power Solutions International?
If Power Solutions International has sharpened your focus on opportunities, do not stop here. Broaden your watchlist with targeted screeners that surface very different types of potential setups.
- Target steadier opportunities by reviewing the 29 resilient stocks with low risk scores. These can help keep volatility in check while still offering room for a thesis to play out.
- Hunt for stronger value by scanning the 34 high quality undervalued stocks. These combine quality fundamentals with prices that may not fully reflect underlying potential yet.
- Build an income tilt by focusing on the 4 dividend fortresses. These could help anchor your returns when market sentiment swings hard.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com