


EN
Earnings Strength Might Change The Case For Investing In PACCAR Stock
- PACCAR reported third quarter 2026 sales of US$7,377.6 million and net income of US$847.5 million, with basic and diluted EPS from continuing operations of US$1.61, alongside nine month sales of US$20,608.9 million and net income of US$2,204.8 million.
- The combination of higher third quarter and nine month sales with greater net income and earnings per share indicates that PACCAR converted recent operating conditions into improved profitability across its truck, parts and financial services activities.
- The next step is to consider how PACCAR's stronger third quarter profitability may reshape the existing investment narrative around margins and resilience.
PACCAR Investment Narrative Recap
To own PACCAR, you generally need to believe that its truck, parts and financial services operations can keep translating industry demand and regulatory change into resilient earnings. The latest quarter, with higher sales, net income and EPS versus a year ago, supports the view that current operating conditions are being converted into stronger profitability.
The key near term swing factor remains how PACCAR handles the run up to the 2027 emissions rules, where pre buy behavior could move volumes around. The biggest operational risk is that any softness in parts demand or slower progress on new powertrain programs, highlighted by trimmed 2026 guidance earlier this year, tightens margins instead of supporting them.
The most relevant data point here is the third quarter 2026 earnings release itself. PACCAR reported US$7,377.6 million in quarterly sales and US$847.5 million in net income, with basic and diluted EPS from continuing operations of US$1.61. For investors watching margins, that jump in profitability relative to last year’s third quarter is an important reference point.
Those same results show nine month sales of US$20,608.9 million and net income of US$2,204.8 million, with EPS of US$4.18 from continuing operations. That run rate matters when evaluating catalysts such as emissions driven truck replacement and the expanding PACCAR Parts and Financial Services contributions, and it also highlights the risk that earnings growth underperforms what is already implied in expectations.
PACCAR's narrative projects US$36.3b revenue and US$5.0b earnings by 2029. This implies 7.7% yearly revenue growth and an earnings increase of about US$2.2b from US$2.8b today.
Discover how PACCAR's fair value points to a 25% potential upside to its current price before the market closes that gap.
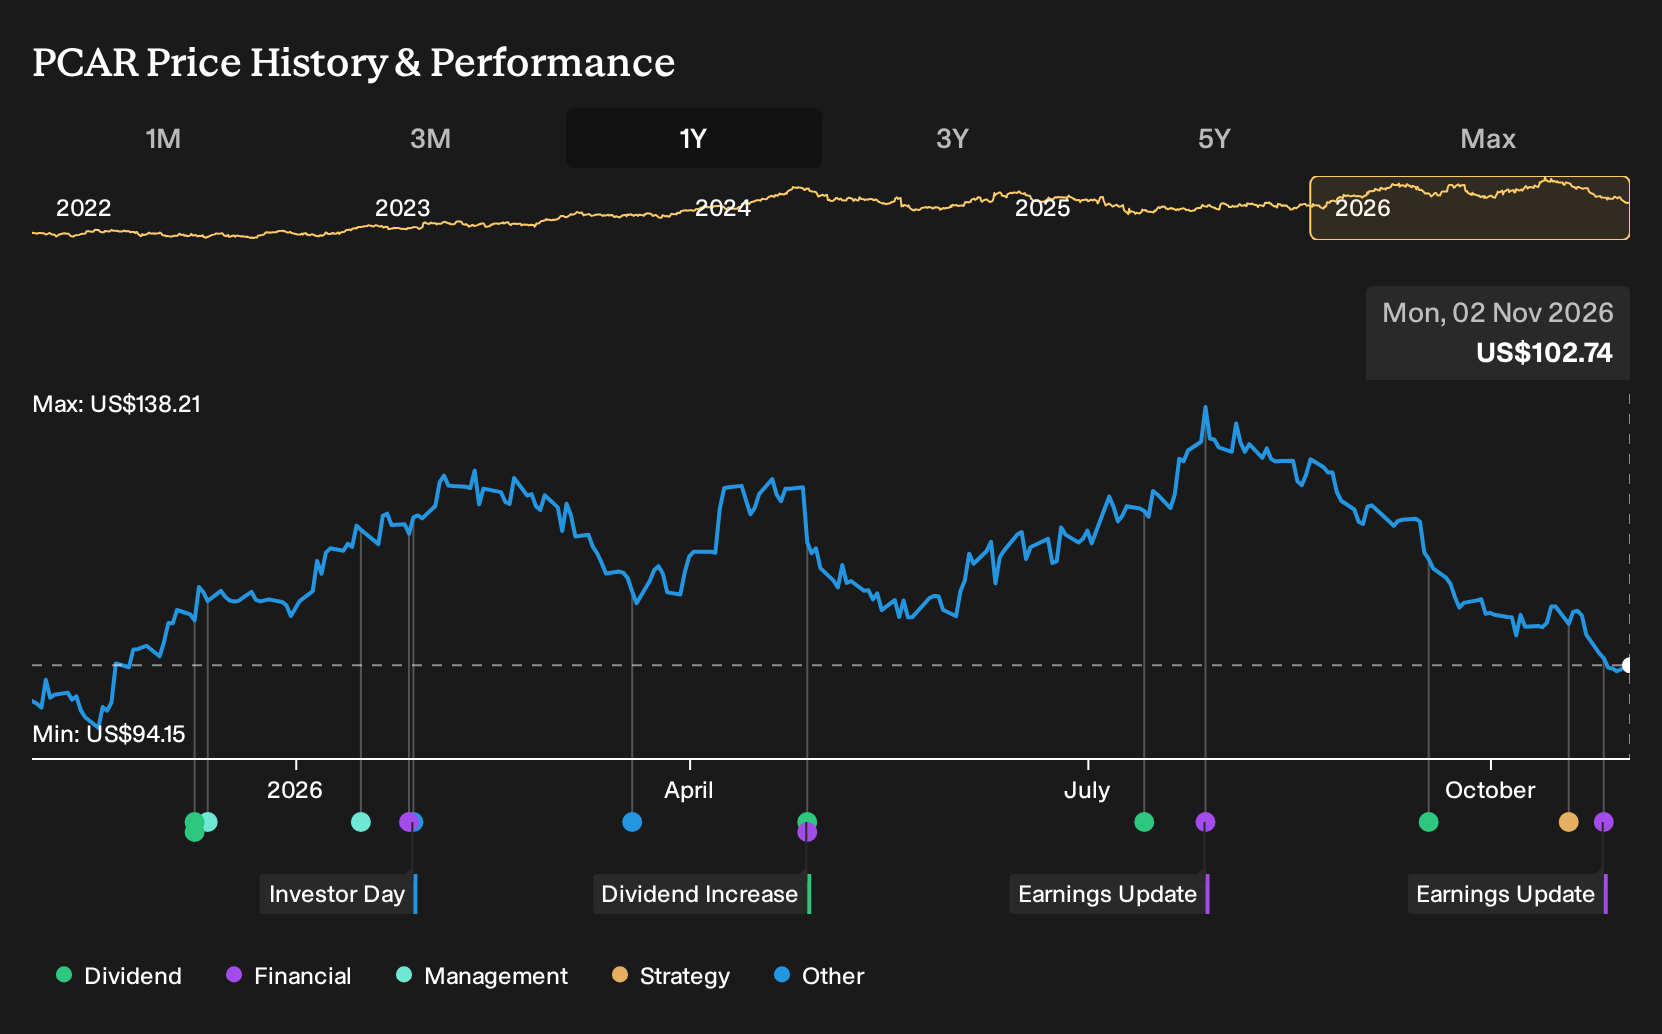
Exploring Other Perspectives
One alternate angle focuses on technology risk. Some of the lowest PACCAR analysts were assuming only 1.7% annual revenue growth and earnings of about US$3.7b by 2029, reflecting concern that electric and autonomous trucks could outpace PACCAR’s product mix. Those forecasts came before this earnings release, so you may see those narratives shift.
Explore 3 other PACCAR fair value estimates, including one that suggests it could be worth just $104.00.
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your PACCAR research is our analysis highlighting 5 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for PACCAR. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate PACCAR's overall financial health at a glance.
Looking for More Investment Ideas Beyond PACCAR?
Once you have a view on PACCAR, it can help to compare it with other businesses that share similar financial strengths or different risk profiles. The Simply Wall St Screener is a practical way to line up alternatives side by side and pressure test your thesis against what the broader market is offering.
- For investors who prefer quality at a discount, start with companies that screen well on earnings strength and valuation using the 34 high quality undervalued stocks.
- If income is your priority, focus on businesses with robust cash flows supporting higher yields by filtering through the 4 dividend fortresses.
- For a focus on resilience, compare PACCAR to peers with strong balance sheets and consistent fundamentals by scanning the 29 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com