


EN
AAON (AAON) Nears A Q3 Earnings Test, Is The Pullback Leaving It Cheap?
AAON earnings expectations spark fresh investor focus
AAON (AAON) is back in the spotlight as analysts highlight expectations for a strong third quarter earnings beat, citing a projected 54.1% year over year increase and a solid surprise track record.
Investor enthusiasm around AAON’s earnings setup is landing against a weaker tape, with the share price down 18.35% over the past 30 days and 28.84% over 90 days. However, the 3 year total shareholder return of 19.35% and 5 year total shareholder return of 39.83% point to a longer record of value creation.
Spot opportunities beyond AAON by scanning a curated 34 high quality undervalued stocks that combines earnings momentum with balance sheet strength.AAON appears to be a quality HVAC manufacturer with rising earnings expectations, yet the share price has slid sharply in recent months. The key question for investors is whether that pullback leaves the business attractively valued or still demanding a premium.
Most Popular Narrative: 47% Undervalued
On the most followed view, AAON is treated as worth about $128.50 a share, almost double the last close at $67.99, which puts a lot of weight on future execution rather than recent price weakness.
The main thing that has to go right is that AAON turns rapid BASX data center growth, AAON brand share gains, and heavy capex into sustained margin expansion and stronger free cash flow, despite recent gross margin pressure and historical negative free cash flow.
The numbers imply the market is pricing AAON as if current margin compression, high reinvestment, and the recent 17.4% share price decline are bigger risks than the potential upside from BASX capacity of more than US$2b and the doubled company-wide backlog.
See why 7 investors see AAON as 47% undervalued.
Result: Fair Value of $128.50 (UNDERVALUED)
Still, the AAON story can break if margin pressure from Memphis and BASX persists or if heavy capex keeps free cash flow under strain for a longer period.
Find out about the key risks to this AAON narrative.
Another View: AAON on earnings multiples
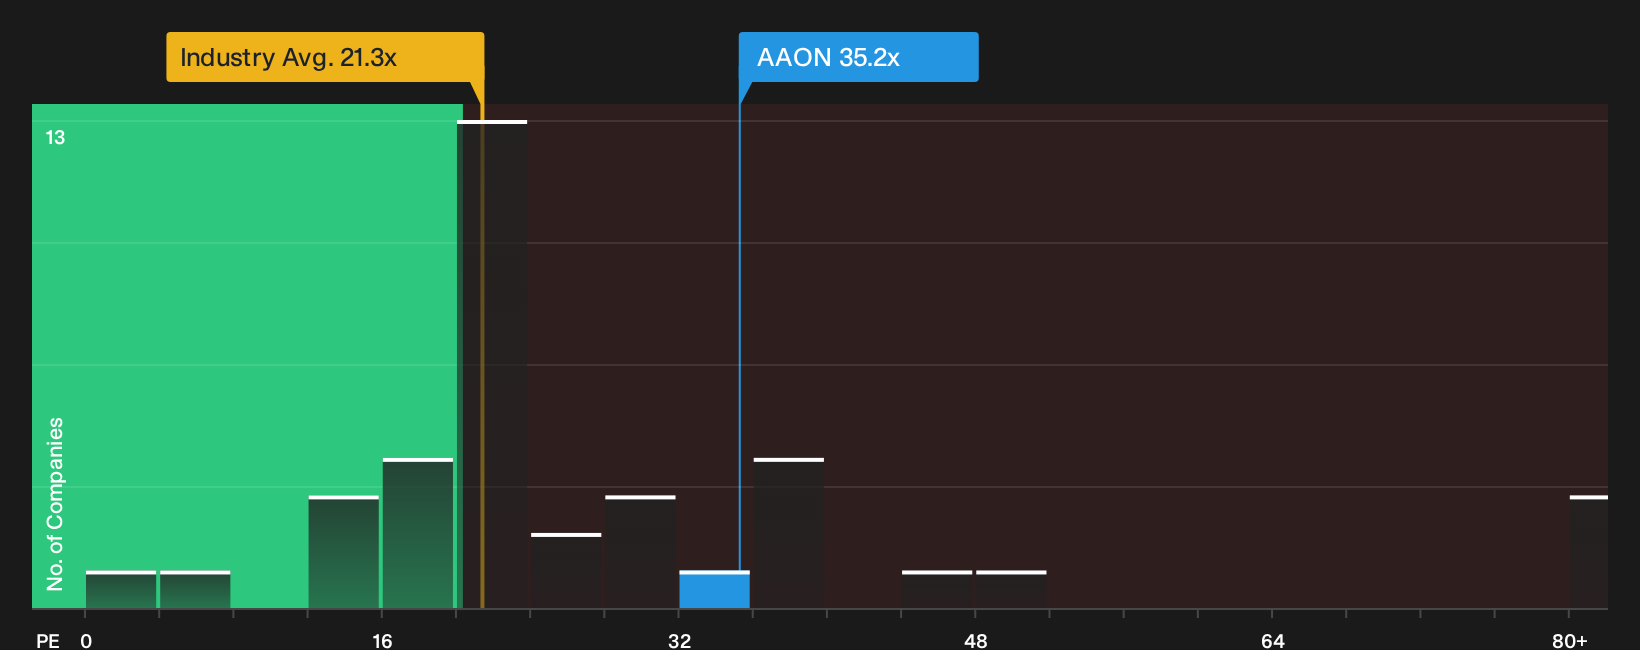
The first narrative treats AAON as deeply undervalued. However, the current P/E of 35.2x already sits above the US Building industry at 21.3x and even the peer average at 33.4x. The fair ratio of 42.9x implies further upside, so the real question is whether that richer multiple is realistic or just extra risk.
See what the numbers say about this price with See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Given the mix of optimism and concern around AAON, it helps to look past the headlines and evaluate the trade off independently using the 4 key rewards and 2 important warning signs.
Looking for more investment ideas beyond AAON?
If AAON has sharpened your focus on quality and valuation, do not stop here. Broader opportunity often shows up first in the companies you have not checked yet.
- Target potential mispricing by scanning a curated list of 34 high quality undervalued stocks that combine stronger fundamentals with attractive entry points.
- Strengthen capital preservation by reviewing a 29 resilient stocks with low risk scores that aims to reduce portfolio volatility when individual stories do not play out as expected.
- Spot tomorrow's potential leaders early by filtering a 19 high quality undiscovered gems where solid quality metrics have not yet drawn wide investor attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com