


EN
Learn Why The Bull Case For Enterprise Financial Services (EFSC) Could Change Following Higher Credit Losses
- Enterprise Financial Services Corp reported third quarter 2026 results with higher net interest income year over year, lower net income, meaningfully higher net charge offs of US$11,036,000, and board approval of both a US$0.36 common dividend and a US$12.50 per Series A preferred share dividend, all payable in December 2026.
- The combination of rising credit losses alongside continued cash returns through common and preferred dividends highlights Enterprise Financial Services Corp balancing asset quality pressures with an ongoing capital return framework. Investors will likely compare this with its historical credit performance and payout decisions.
- The focus now turns to how Enterprise Financial Services Corp's higher net charge offs might reshape the existing investment narrative around credit normalization.
Enterprise Financial Services Investment Narrative Recap
To own Enterprise Financial Services, you need to be comfortable with a bank that leans on a strong net interest income engine while working through credit clean up. The big swing factor is whether elevated nonperforming assets and higher recent net charge offs ease over time, which could take pressure off provision expense and margins.
The near term risk is that the jump in quarterly net charge offs and softer net income persists, especially if problem credits take longer to resolve or fee income remains uneven. The latest results do not radically change that story, but they keep credit quality firmly in the spotlight for now.
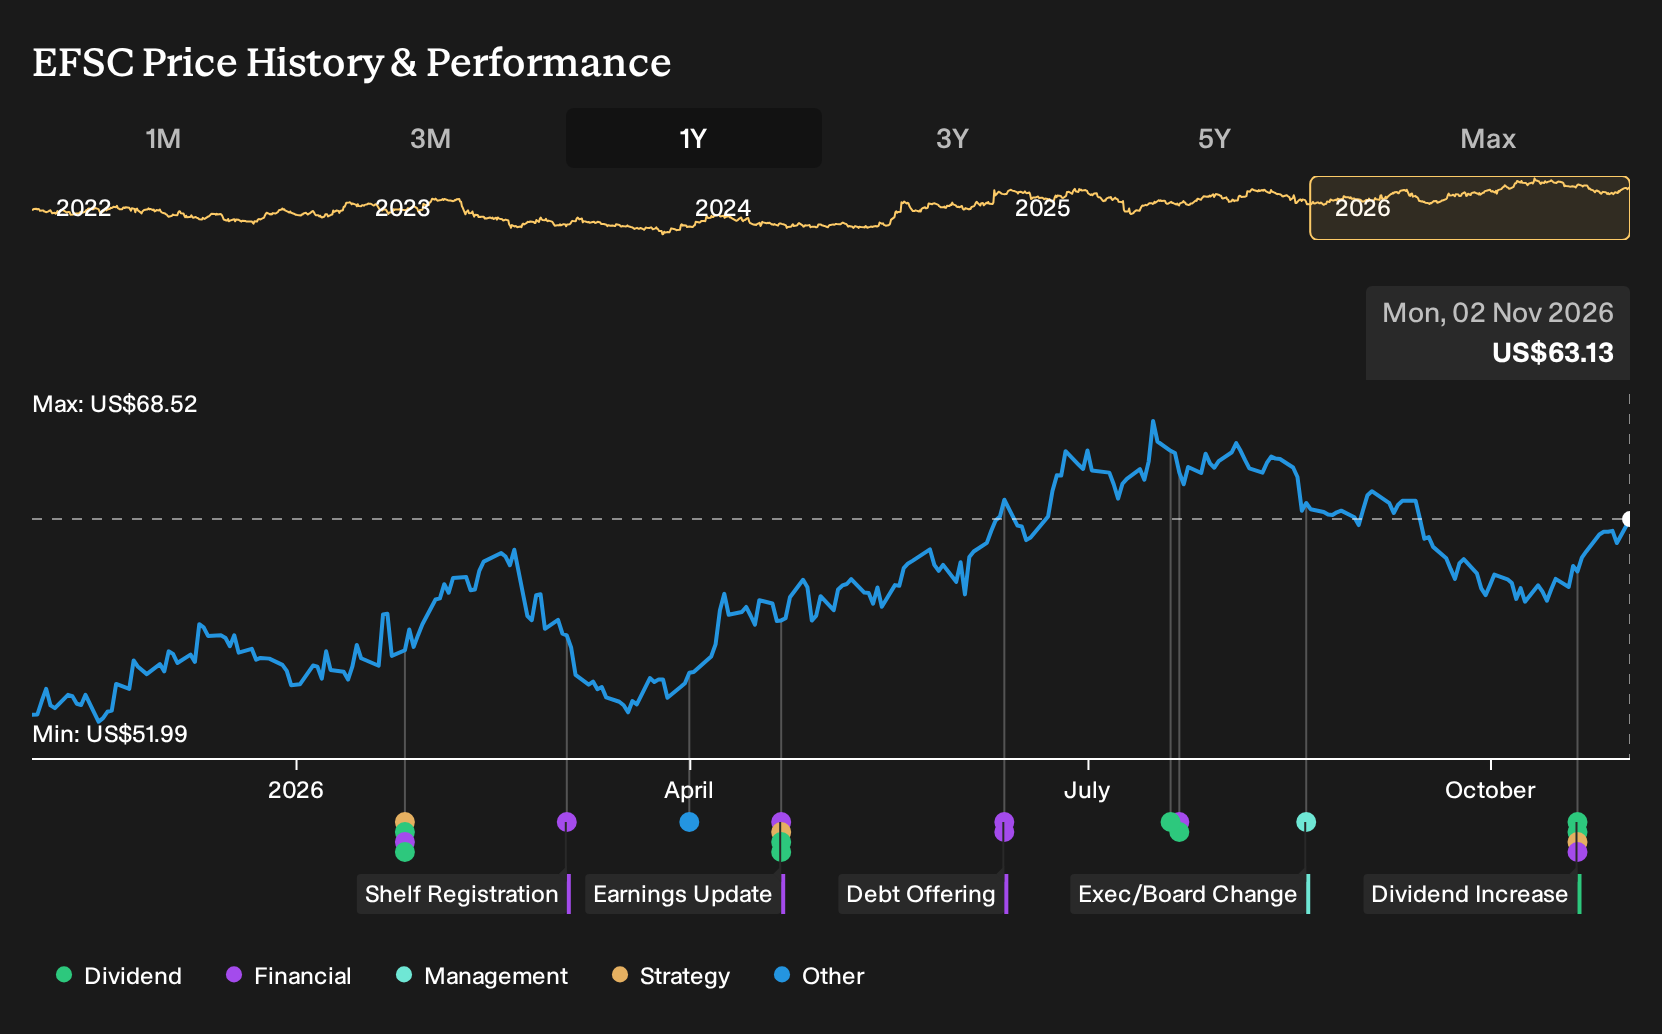
The common dividend of US$0.36 per share, approved for payment on December 31, 2026, is the announcement that most clearly links to the current setup. Management is choosing to keep cash returns flowing while earnings per share from continuing operations for the quarter are slightly lower than a year ago.
For you as a shareholder, that payout decision is part of the catalyst and risk mix. It signals confidence in Enterprise Financial Services' capital position and funding model. At the same time, it means investors need to watch whether rising net charge offs and ongoing credit normalization leave enough room to keep supporting both balance sheet repair and these distributions.
Enterprise Financial Services' narrative projects US$935.0 million revenue and US$227.9 million earnings by 2029. This is based on an assumed revenue growth of 10.4% per year and an earnings increase of about US$41.3 million from the current US$186.6 million level.
Discover why Enterprise Financial Services' fair value indicates a 12% potential upside to its current price that may not last much longer.
Exploring Other Perspectives
Two fair value estimates from the Simply Wall St Community sit wide apart, from about US$71 to roughly US$107 per share, which shows how differently people are pricing Enterprise Financial Services today. Those opinions pre date the higher net charge offs and the fresh preferred dividend, so treat them as starting points and explore several contrasting views before deciding how this story fits your portfolio.
Explore another Enterprise Financial Services fair value estimate, including one that suggests as much as 70% upside from the current price!
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider forming your own view.
- A great starting point for your Enterprise Financial Services research is our analysis highlighting 3 key rewards that could impact your investment decision.
- See our latest analysis for Enterprise Financial Services. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, which makes it easy to evaluate Enterprise Financial Services' overall financial health at a glance.
Looking for more investment ideas beyond Enterprise Financial Services?
If the Enterprise Financial Services story has you thinking about how credit risk, dividends, and capital strength all fit together, it can help to scan a wider field of potential holdings using the Simply Wall St Screener.
- For investors who want income with resilience, review companies screened for robust payouts backed by solid fundamentals via the 4 dividend fortresses.
- If capital preservation and stability matter most to you, filter for businesses with stronger financial footing using the list of solid balance sheet and fundamentals (24 results).
- Readers searching for underappreciated opportunities can cast the net wider with a 19 high quality undiscovered gems that combines quality markers with less familiar tickers.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com