


EN
Is CNA Financial (CNA) A Bargain As Q3 Earnings Miss Raises Underwriting Questions?
Q3 earnings miss and dividend decision put CNA Financial in focus
CNA Financial (CNA) landed in the spotlight after third quarter 2026 results came in below analyst expectations, with softer underwriting performance and reserve updates, while the board maintained a quarterly dividend of $0.48 per share.
CNA Financial shares closed at US$47.92, with the stock down 1.6% on the day and weaker over the past quarter. However, a 1-year total shareholder return of 18.0% and a 3-year total shareholder return above 50% point to longer term momentum that has held up better than the recent 90 day share price decline of 9.5% might suggest.
Spot fresh insurance plays reacting to similar underwriting and pricing pressures as CNA Financial by scanning our hand picked 29 resilient stocks with low risk scores list.After the earnings miss and recent pullback, the question is whether CNA Financial already reflects those setbacks or if patience could still offer you a cleaner entry. It is time to see what the valuation is actually implying.
Price-to-earnings of 10.5x for CNA Financial: Is it justified?
CNA Financial is being valued at a P/E of 10.5x against a last close of $47.92, which points to a cheaper tag than many peers despite the recent earnings wobble. That gap raises the question of whether the market is pricing in too much concern around underwriting volatility or assigning a discount that lines up with more modest earnings forecasts.
The P/E ratio compares what you pay today to the company’s current earnings, so for insurers like CNA Financial it becomes a shorthand for what the market thinks those profits are worth. A lower P/E can suggest investors are cautious about future profitability or business risks, while a higher one usually implies stronger confidence in the durability of earnings.
For CNA Financial, the current P/E of 10.5x screens as good value compared with its own estimated fair P/E of 11.7x from the fair ratio model. The market could move towards that level if sentiment and earnings quality stay aligned. That 10.5x multiple also looks meaningfully lower than the 11.5x average for the broader US insurance group and well below the 16.7x peer average, which signals the market is assigning a clear discount even though recent earnings growth and margin improvement are already visible in the numbers.
Explore the SWS fair ratio for CNA Financial.
Result: Price-to-earnings of 10.5x (UNDERVALUED)
Still, the recent earnings miss and softer underwriting, together with reserve adjustments, could weigh on sentiment if similar issues persist in coming quarters.
Find out about the key risks to this CNA Financial narrative.
Another view on CNA Financial using our DCF model
The income based view looks cheap, yet the SWS DCF model goes further. It estimates CNA Financial's future cash flow value at $85.21 per share against the current $47.92 price, which screens as undervalued. That is a big gap. Is it a margin of safety, or a signal you should treat with caution?
Look into how the SWS DCF model arrives at its fair value.
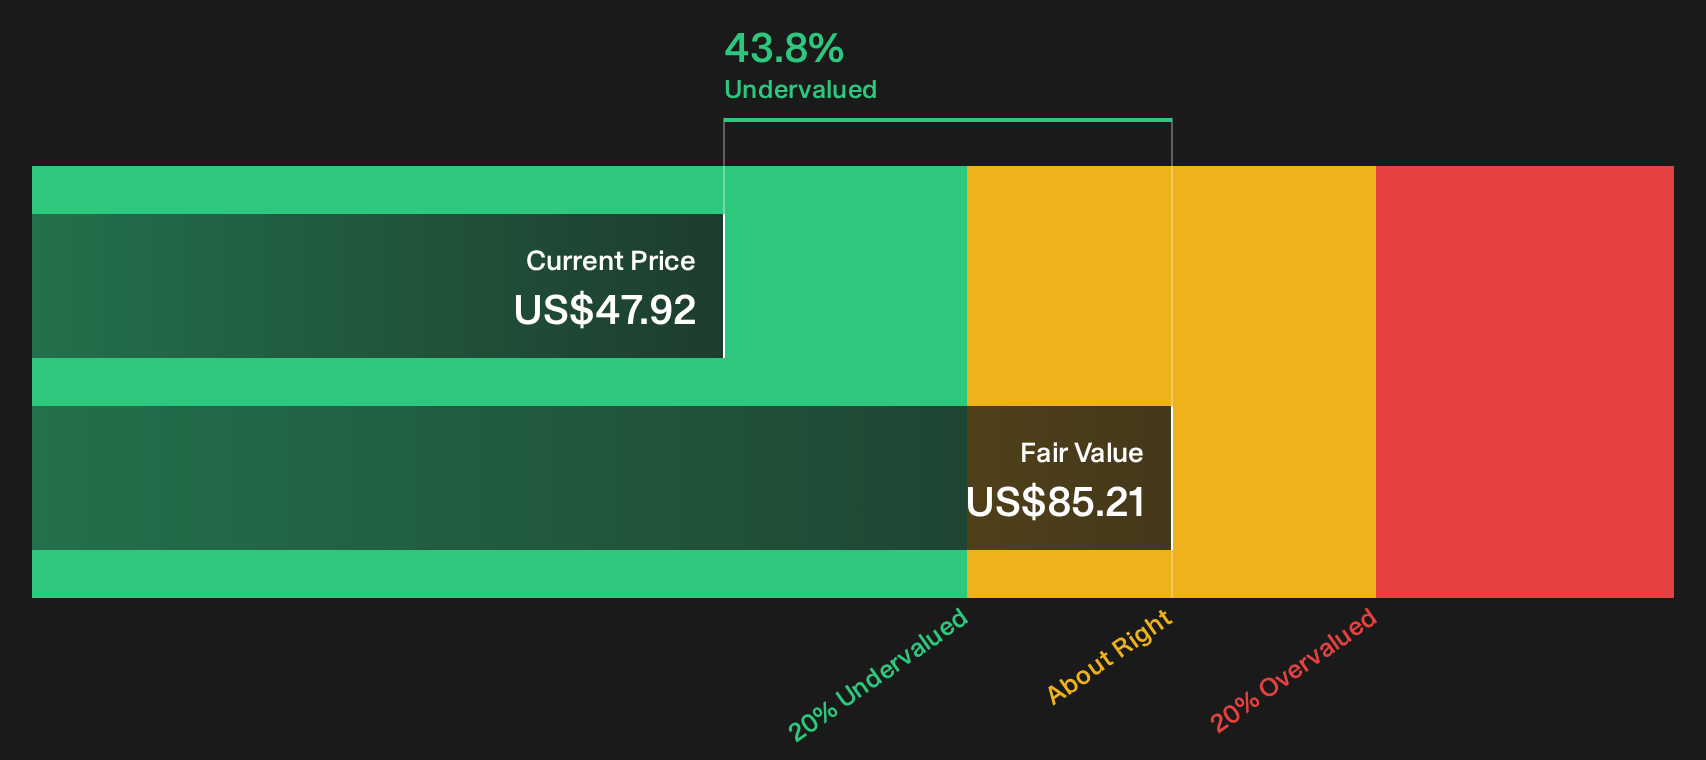
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out CNA Financial for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 34 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed feelings on CNA Financial after this valuation workup. If you want to move fast and build your own conviction, start with the 3 key rewards and 2 important warning signs.
Ready for more investment ideas beyond CNA Financial?
If CNA Financial has sharpened your thinking on valuation and risk, do not stop there. Broader idea hunting can help you build a stronger watchlist.
- Target resilient balance sheets by reviewing the list of solid balance sheet and fundamentals (24 results) to keep financial cushions front and center when markets turn choppy.
- Hunt for mispriced opportunities by scanning the 34 high quality undervalued stocks where quality fundamentals and discounted valuations sit side by side.
- Build an income focused shortlist by checking the 4 dividend fortresses to help you spot robust cash returns with supportable payout profiles.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com