


EN
Precigen (PGEN) Faces New RRP Rival As Fair Value Debate Comes Into Focus
Event puts Precigen’s core franchise under the spotlight
The FDA’s accelerated approval of Inovio’s Voceryq for recurrent respiratory papillomatosis directly targets the same rare disease as Precigen (PGEN) therapy Papzimeos, sharpening investor focus ahead of this week’s earnings update.
Precigen’s share price has fallen 25.9% over the past day and is down 39.8% over the past month, which may hint at fading short term momentum as investors reassess Papzimeos in light of Inovio’s approval. However, the 3 year total shareholder return of more than 3x still reflects a strong longer term payoff for those who held through earlier volatility.
Scan 19 high quality undiscovered gems in biotech to see how other under-the-radar therapies compare to Precigen, as Papzimeos faces its first approved rival.
After a three year return of more than 3x and a sharp pullback in recent weeks, is most of Precigen’s re rating already behind it, or does the current price still leave clear upside on the table as Papzimeos and the pipeline get priced in?
Most Popular Narrative: 62% Undervalued
Precigen last closed at $5.14, while the most followed narrative framework anchors fair value at $13.65, which points to a wide gap that current volatility around Papzimeos is not closing on its own.
The analysts have a consensus price target of $13.65 for Precigen based on their expectations of its future earnings growth, profit margins and other risk factors.
However, there is a degree of disagreement amongst analysts, with the most bullish reporting a price target of $17.95, and the most bearish reporting a price target of just $11.0.
See why 13 investors see Precigen as 62% undervalued.
Result: Fair Value of $13.65 (UNDERVALUED)
Still, the current story around Precigen hinges heavily on Papzimeo’s execution, so any slower than expected uptake or tougher pricing could quickly challenge that undervalued narrative.
Find out about the key risks to this Precigen narrative.
Another View: What Multiples Say About Precigen
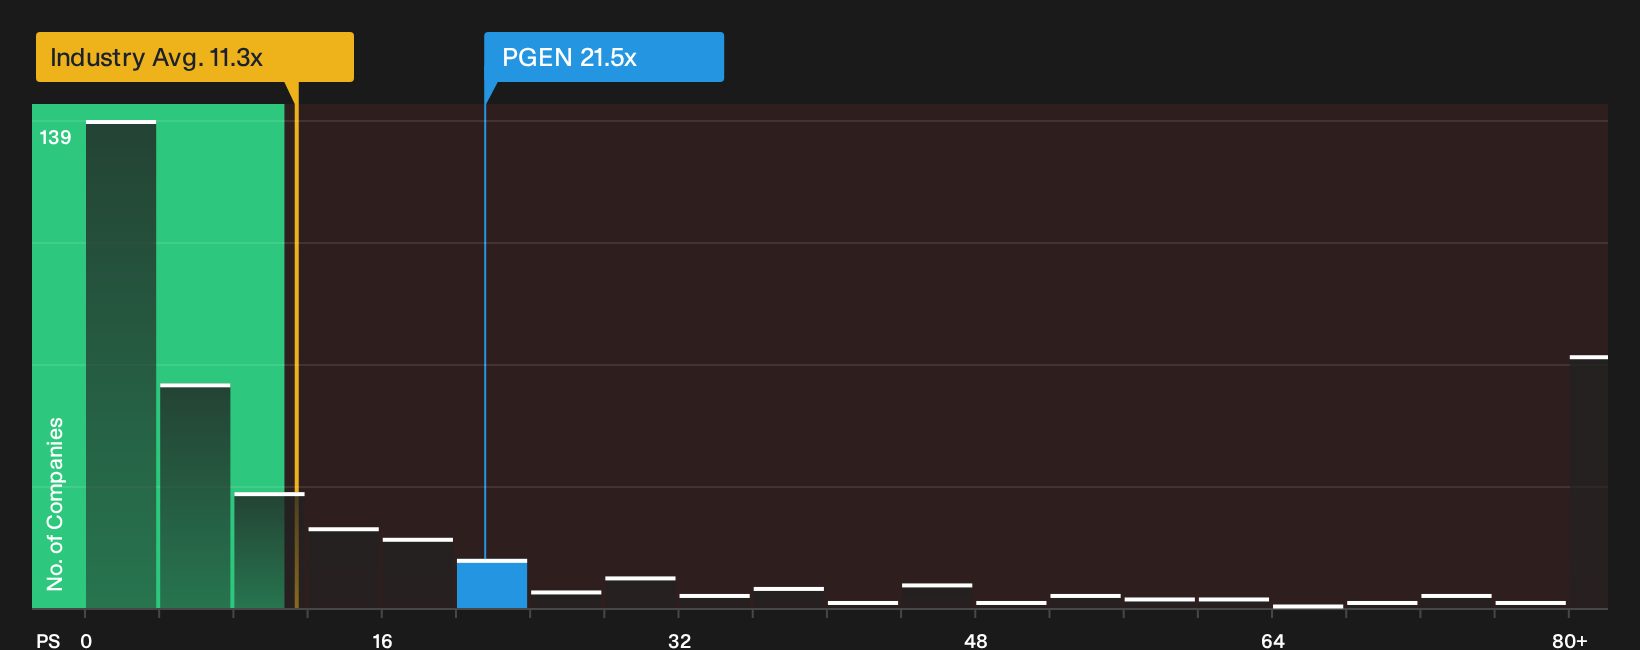
Analyst models and the SWS fair value both point to Precigen being undervalued, yet the current P/S ratio of 21.5x tells a more cautious story. That multiple is almost double the US Biotechs average of 11.3x and well above the 8.9x fair ratio SWS estimates the market could move toward over time.
If sentiment were to drift closer to that fair ratio or even the peer average, the gap between today’s P/S and those reference points would matter a lot more than any single price target on a spreadsheet. The question for you is whether Papzimeos and the broader platform really justify paying this much more per dollar of sales.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment around Precigen is split, and the clock is already ticking on how Papzimeos and the rest of the pipeline actually perform in the real world. Before momentum swings again, weigh the 2 key rewards and 4 important warning signs.
Looking for more Precigen-sized opportunities?
Do not stop your research at Precigen. Broaden your watchlist now, because the next move that really changes your returns rarely comes from the obvious place.
- Target stronger upside potential by scanning a curated 19 high quality undiscovered gems that many investors have not started analysing yet.
- Prioritise resilience by filtering for a list of solid balance sheet and fundamentals (24 results) that can better handle setbacks without constant refinancing risk.
- Secure more dependable income streams by focusing on 4 dividend fortresses that aim to combine higher yields with sturdier fundamentals.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com