


EN
CONMED Stock Earnings Update After Profit Jump And Full Year Sales Guidance
- CONMED reported third quarter 2026 sales of US$335.56 million and net income of US$19.8 million, with basic earnings per share from continuing operations of US$0.66, and slightly adjusted full year 2026 net sales guidance to a range of US$1.36b to US$1.366b.
- The mix of essentially flat quarterly sales against higher earnings points to cost and efficiency effects playing a bigger role in CONMED's financial profile than pure top line expansion. This matters for how you think about the durability of its margin structure.
- We will now look at how CONMED's investment narrative could be affected by stronger earnings per share alongside only modest sales guidance.
Compare CONMED's margin focused story with other healthcare stocks by scanning our hand picked 33 healthcare AI stocks, which blend medical exposure with AI driven efficiency themes.
CONMED Investment Narrative Recap
To stay invested in CONMED, you need to believe the key platforms in minimally invasive surgery and smoke evacuation can support steady procedure demand and recurring consumable usage, even if headline sales move in a tight range. The recent quarter fits that picture. Sales were roughly stable while earnings improved, which keeps the focus on execution rather than a growth reset.
The main short term catalyst remains how effectively management can translate this margin work into consistent cash generation while organic growth sits in the mid single digit range implied by the 2026 guidance. The biggest risk is that flat or soft volumes in areas like U.S. orthopedics persist, which would make further margin gains harder without cutting into commercial support.
The most relevant update here is the slightly refined 2026 net sales guidance to US$1.36b to US$1.366b. That range keeps expectations tight and puts the spotlight on mix, pricing and cost control rather than a big volume ramp. For you as an investor, it frames 2026 as a year of blocking and tackling rather than a reset.
When that guidance sits beside third quarter earnings of US$19.8 million on US$335.56 million of sales, the story becomes very operational. CONMED is signalling confidence in holding a specific revenue corridor while profits do more of the heavy lifting. The risk is that any pressure on procedures or capital spending now flows more quickly into margins because the top line cushion is limited.
What The Current CONMED Forecasts Assume
CONMED's narrative projects revenues of US$1.6b and earnings of US$179.7 million by 2029. That profile sits on analyst assumptions of 4.2% yearly revenue growth and an earnings increase of about US$123 million from US$56.5 million today.
Uncover why CONMED's fair value is in line with its current price.
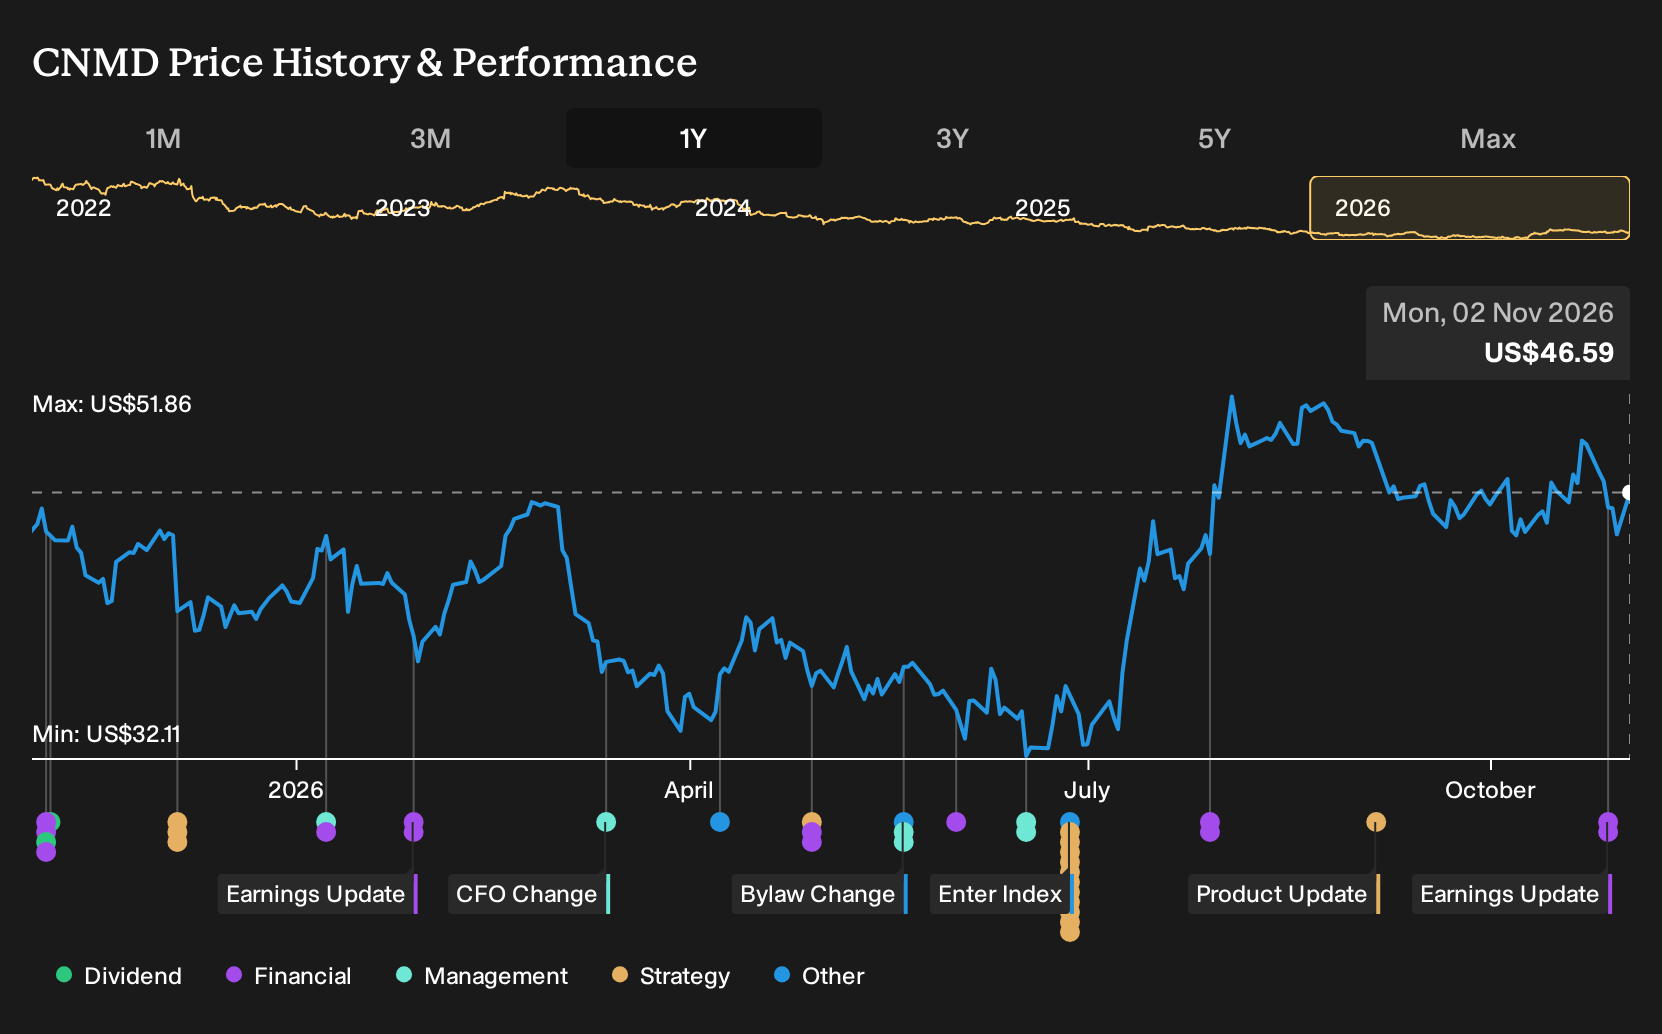
Exploring Other Perspectives
Some of the most optimistic analysts focus on a different catalyst. They lean heavily on CONMED’s share repurchase plans and expected earnings of about US$171.8 million by 2029, compared with roughly US$56.5 million before this earnings release. Their view has not yet absorbed the latest quarter; as a result, you may see those projections shift as new information lands.
Explore 3 other CONMED fair value estimates, including one that suggests potential upside of up to 128% from the current price.
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your CONMED research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for CONMED. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, which makes it easy to evaluate CONMED's overall financial health at a glance.
Looking For More Investment Ideas Beyond CONMED?
If CONMED's margin focused story has you thinking about portfolio balance, it can help to compare it with very different business profiles that still meet your quality bar.
- For investors who want potential upside with tighter capital discipline, review a curated 8 elite penny stocks with strong financials that filters for stronger balance sheets and cleaner fundamentals in the lower price ranges.
- If you prefer companies where price and quality line up more clearly, scan a hand picked group of 34 high quality undervalued stocks that combine solid cash generation with disciplined financial profiles.
- For a more defensive tilt with an emphasis on resilience, focus on businesses in the 29 resilient stocks with low risk scores that score well on stability, earnings consistency and financial strength.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com