


EN
Learn Why The Bull Case For HSBC Holdings Could Change Following Strong Third Quarter Results
- HSBC Holdings reported third quarter 2026 results with net income of US$7,552 million and net interest income of US$9,307 million, confirmed full year 2026 banking NII guidance of at least US$46 billion, and proposed a third quarter ordinary dividend of US$0.10 per share.
- The group coupled earnings and dividend news with fresh balance sheet moves, including make whole redemption of 7.39% senior notes due 2028 and new fixed to floating senior unsecured issuance totaling US$4.25 billion that reshapes its funding mix and interest cost profile.
- We will now see how HSBC Holdings' stronger third quarter earnings and reaffirmed net interest income guidance interact with its broader investment narrative.
HSBC Holdings Investment Narrative Recap
To own HSBC Holdings, you need to be comfortable with a global bank that leans heavily on banking net interest income, Asian wealth, and transaction banking. At the same time, competition for deposits and ongoing market exits keep pressure on returns. The key short term swing factor is whether deposit pricing and mix let HSBC turn its confirmed 2026 banking NII guidance of at least US$46b into resilient earnings.
The make whole redemption of the 7.39% senior notes and new fixed to floating issuance adjusts funding costs but does not change that core thesis. The more immediate risk remains deposit competition and execution on replacing roughly US$2.2b of revenue tied to exits between 2026 and 2028.
The most relevant recent datapoint is the third quarter ordinary dividend of US$0.10 per share combined with the confirmed 2026 banking NII guidance. For an investor watching HSBC Holdings, that combination puts the focus on whether the earnings engine and capital position can comfortably fund both cash returns and the ongoing shift toward Asian wealth and transaction banking.
This dividend decision also interacts directly with key risks. An unstable dividend track record and revenue attrition from exits mean the payout still depends on tight cost control, steady credit quality given a relatively low bad loan allowance, and delivery on digital and transaction banking projects that aim to deepen fee income and reduce reliance on interest spreads.
Analysts’ narrative for HSBC Holdings points to revenues of US$88.9b and earnings of US$32.9b by 2029, based on a projected 9.6% yearly revenue growth rate and an increase in earnings of about US$8.7b from US$24.2b today to the 2029 consensus level.
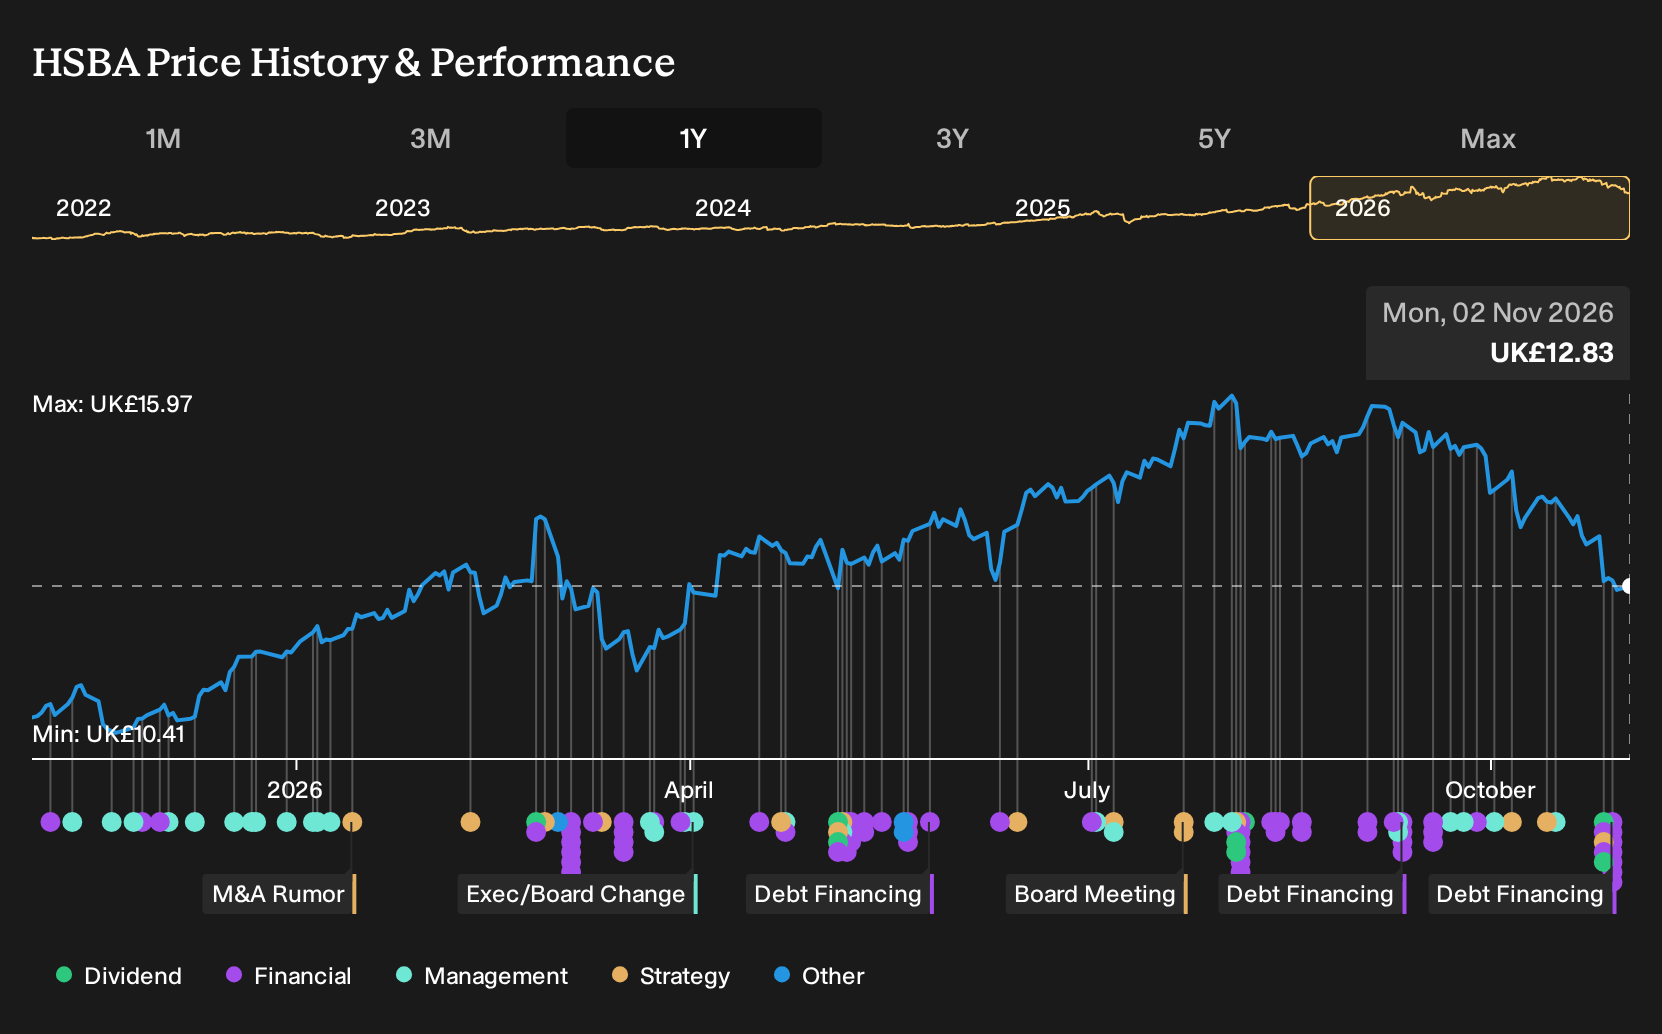
Uncover why HSBC Holdings' fair value indicates an 18% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
One alternative view focuses on the risk that HSBC Holdings leans even harder on net interest income just as deposit margins could tighten. The most bearish analysts were working off revenue of about US$86.3b and earnings of roughly US$31.1b by 2029, far below the more optimistic peers. Those forecasts, set before this funding reshuffle and dividend news, show how sharply opinions can split. Use that spread as a prompt to compare several narratives and decide which assumptions you find most realistic.
Explore 11 other HSBC Holdings fair value estimates, including one that suggests it could be worth just £12.39.
Decide For Yourself
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your HSBC Holdings research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for HSBC Holdings. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate HSBC Holdings' overall financial health at a glance.
Looking For More Investment Ideas Beyond HSBC Holdings?
Once you have formed a view on HSBC Holdings, it can help to compare that stance with other opportunities that share similar qualities or offer a very different return profile. The Simply Wall St Screener lets you filter by balance sheet strength, income focus, or risk profile so you can build a watchlist that actually fits your goals.
- If you want potential income combined with resilience, check out a curated set of higher yielding companies that our screener highlights as 5 dividend fortresses.
- For investors who care most about capital preservation and steadier profiles, the screener can point you toward 5 resilient stocks with low risk scores that may better match a cautious approach.
- If your priority is financial robustness and fundamentals, start with a list of solid balance sheet and fundamentals (10 results) to compare against HSBC Holdings' own position.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com