


EN
What Oil States International Doubters Got Wrong
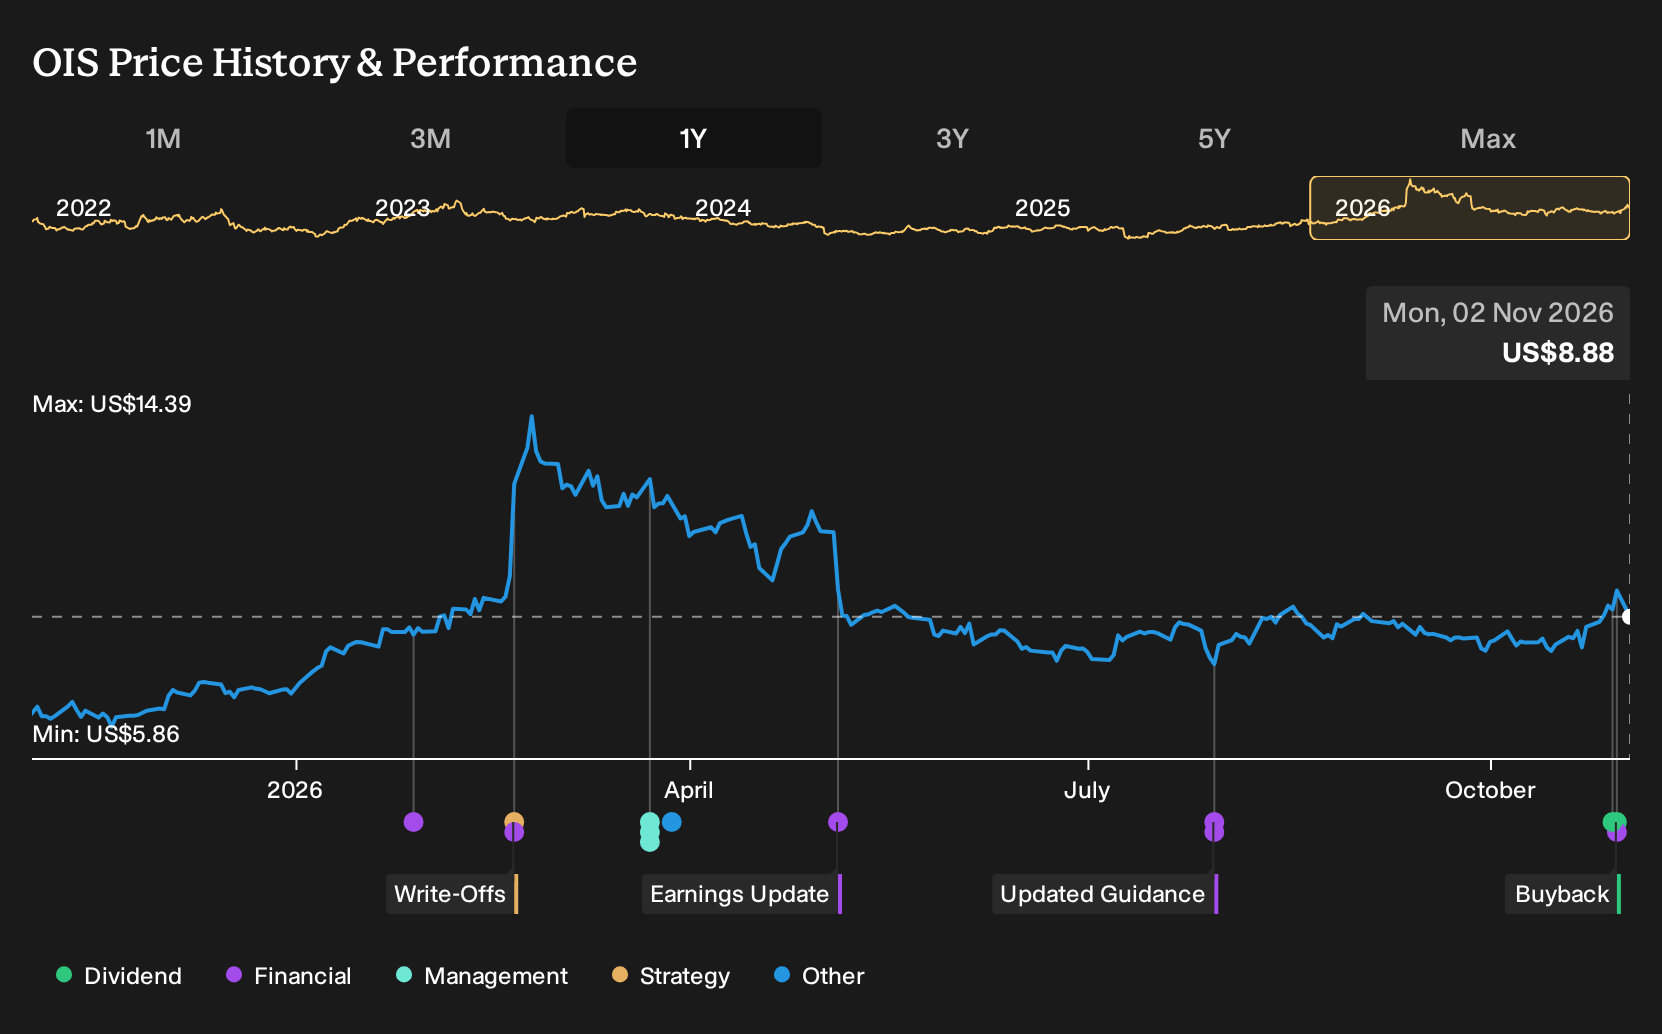
Oil States International did not move headlines with a blockbuster contract this year, but the board quietly signed off on a fresh US$50 million share repurchase plan running through 2028, which may indicate how management views excess cash. For Oil States International shareholders, the return over the past year was 38.5%, including dividends. If you were weighing a buy on 2 November 2025, what would need to be true about offshore demand and margin progress to make that later outcome plausible?
The useful thing about a Narrative is that the reasoning is checkable: the assumptions sit beside the argument, and together they imply an estimated Fair Value you can disagree with.
Oil States International has already moved. See which of 34 high quality undervalued stocks still trade below our estimates.
The Two Narratives Investors Had To Weigh On Oil States International
The shares cost US$5.97 at the start of the period, and the live debate around Oil States International was whether offshore strength could outweigh energy transition headwinds.
The bullish story pointed to a Fair Value of US$6.88, hinging on offshore and international orders converting a decade high backlog into higher margins, supported by exits from lower margin U.S. land operations.
The bearish view anchored on a Fair Value of US$5.5 and focused on ESG policy pressure and potential oversupply reducing oilfield demand, with future earnings assuming 4.6% annual revenue growth and a 5.3% profit margin.
What The Results Changed For Oil States International
The new US$50 million buyback running through 2028 gave the offshore bullish case fresh support because it signalled confidence in Oil States International's cash generation. Reported numbers pointed the same way. Revenue reached US$169.764 million in Q3 2026 compared with US$165.18 million a year earlier, and net margin moved from 1.1% to 1.8%. The evidence cut both ways but leaned toward the optimistic thesis on profitability.
The key lesson is simple. When a story hangs on margin progress and offshore demand, it can be useful to keep checking reported net margin and any capital return plans against the original assumptions, rather than just watching the share price.
What Oil States International's Run Now Asks You To Believe
Oil States International now trades at US$8.88, and the selected Narrative argues its Fair Value still sits above that level based on offshore and international exposure. The focus has shifted from a broad cycle story to what the reported backlog, margins and cash position already show.
In practical terms, buying here means deciding whether the current price fully reflects the long-cycle offshore backlog, portfolio high grading and net cash balance, or whether those elements still underestimate what sustained execution could mean for future earnings power.
"The Offshore Manufactured Products backlog now sits at about US$451 million with book to bill at 1.2x in 2Q26 and over 70% of recent revenue tied to offshore and international work. This points to further revenue visibility that could support higher earnings than models assuming a flatter backlog profile."
The price and this Narrative do not agree. → Uncover what this Narrative says Oil States International is actually worth
Before The Next Story Makes Headlines
The story behind this run has already been told. The next one could be taking shape somewhere else. Where could you start looking before it becomes the headline?
- Company 1 - 37% below our estimate - converts subsea project pipelines into higher margin equipment sales and service contracts.
- Company 2 - 38% below our estimate - operates complex gold assets balancing long reserve lives against political and financing risks.
- Company 3 - 30% below our estimate - connects AI computing demand and software subscriptions into shared cloud and colocation facilities.
Those are three of them. See all 24 companies with the balance sheet to back it up →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com