


EN
How Investors Are Reacting To ExxonMobil (XOM) Bigger Buyback Plan
- ExxonMobil Holdings reported strong Q3 2026 results, with revenue of US$113.2b, net income of US$15.4b, and basic EPS of US$3.72 from continuing operations, alongside a higher quarterly dividend of US$1.07 per share declared in late October.
- Management paired these earnings with a US$20b expansion of the share repurchase authorization to US$110b and an extension of the buyback plan through 2027, indicating management’s confidence in the durability of ExxonMobil's cash generation from refining, LNG projects, and core upstream assets.
- We will look at how ExxonMobil's investment narrative is shaped by these strong third quarter earnings and the larger repurchase authorization.
Scan how ExxonMobil’s Q3 strength and capital returns compare with other large energy players by reviewing a curated list of 43 power grid technology and infrastructure stocks.
ExxonMobil Holdings Investment Narrative Recap
To own ExxonMobil Holdings, you need to be comfortable with a business still anchored in long life oil and gas projects in Guyana, the Permian and now a bigger LNG footprint. The Q3 2026 numbers, with net income of US$15.4b and basic EPS of US$3.72, reinforce that the near term story is about execution on those barrels and molecules, not a pivot away from hydrocarbons.
The key short term swing factor is operational and pricing strength across refining and LNG, which currently helps offset any production hiccups or softer crude benchmarks. The biggest risk is that policy pressure and faster decarbonization start to erode long run demand before low carbon initiatives scale, although this quarter’s performance itself does not materially change that risk balance.
The expanded US$110b repurchase authorization and extension of buybacks through 2027 is the announcement that matters most for this earnings story. It sits on top of nine month net income of US$34.1b and EPS of US$8.18, signaling that management sees room to keep returning a large share of cash while funding projects like Mozambique LNG and refinery upgrades.
For you as a shareholder, this plan links directly into the main catalysts, which are sustained cash generation from Guyana, the Permian and high utilization downstream assets. Execution risk is that future conditions do not support the assumed cash flows behind such a large program, or that heavier repurchases limit flexibility if decarbonization policies tighten faster than expected.
ExxonMobil Holdings' narrative uses analyst projections that point to US$379.8b in revenue and US$44.3b in earnings by 2029, based on assumed yearly top line growth of 1.7% and an earnings increase of about US$11.5b from the current US$32.8b base.
Uncover why ExxonMobil Holdings' fair value indicates that ExxonMobil Holdings is roughly in line with its current price.
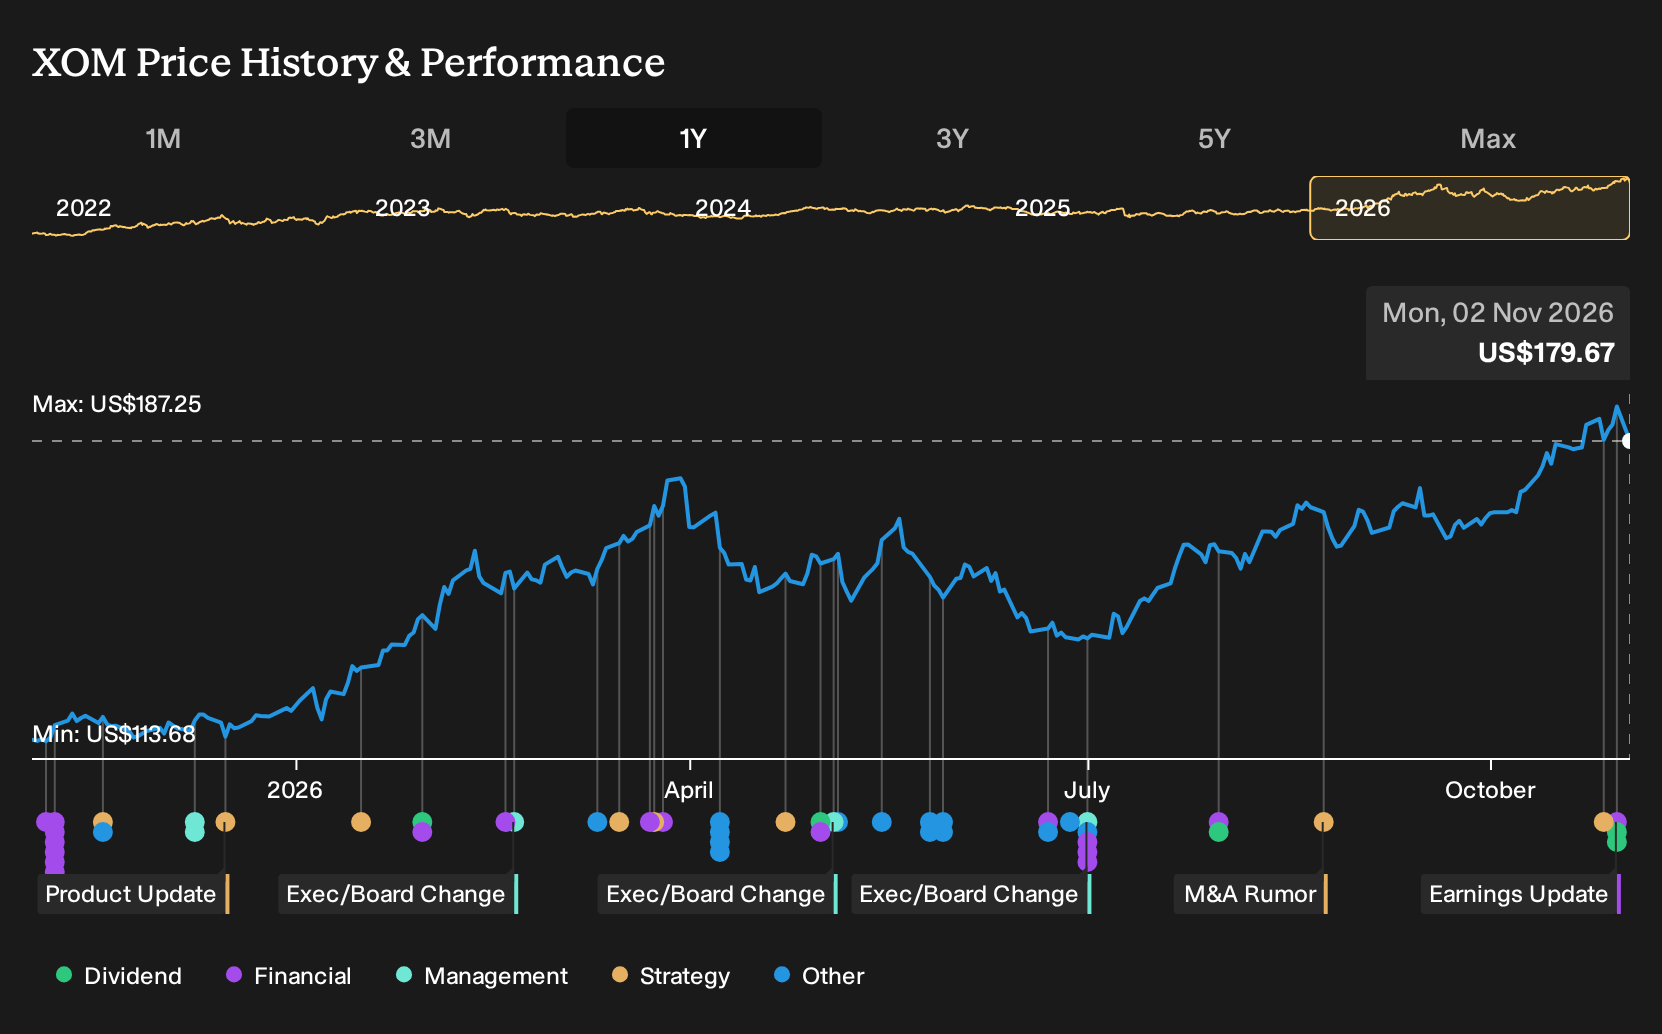
Exploring Other Perspectives
One alternate angle treats ExxonMobil’s lower carbon push as the real swing factor. The most optimistic analysts were already penciling in US$507.5b of revenue and US$55.6b of earnings by 2029, before this Q3 beat and the larger buyback plan. You now have a reason to compare those upbeat assumptions with your own, and to explore how views might shift.
Explore 6 other ExxonMobil Holdings fair value estimates, including one that suggests as much as 29% upside from the current price.
The Verdict Is Yours
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your ExxonMobil Holdings research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for ExxonMobil Holdings. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate ExxonMobil Holdings' overall financial health at a glance.
Looking for more investment ideas beyond ExxonMobil Holdings?
If this earnings story has sharpened your view on ExxonMobil Holdings, use that same lens to scan for other opportunities that fit your risk profile, income goals, and time horizon using the Simply Wall St Screener.
- For investors who want growth potential without completely sacrificing quality, consider a filtered set of higher risk opportunities that still carry stronger balance sheets and fundamentals through 8 elite penny stocks with strong financials.
- If your priority is finding shares that combine resilient cash flows with room for a rerating, focus on companies that screen as both financially sound and priced below internal estimates of worth using 34 high quality undervalued stocks.
- Income seekers who care about durability as much as yield can narrow in on businesses with healthier leverage profiles and consistent fundamentals by reviewing a curated list of solid balance sheet and fundamentals (24 results).
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com