


EN
Does Bigger Private Credit Backing Change The Bull Case For Man Group Stock?
- Man Group announced an expanded partnership with Meiji Yasuda Life Insurance, as Meiji Yasuda plans to commit JPY 200 billion over three years, focused on private credit and new products for Japanese clients.
- The deeper tie up gives Man Group greater access to Japanese insurance capital and structured knowledge sharing via the Oxford Man Institute on technology and investment expertise.
- We will now examine how Man Group's investment narrative could be influenced by Meiji Yasuda's larger private credit capital commitment and collaboration.
Man Group Investment Narrative Recap
To own Man Group, you need to believe it can keep turning its broad product range and technology heavy operating model into sustained fee income from a larger asset base. The expanded Meiji Yasuda commitment leans into that story by supporting the private credit platform, although the immediate impact on near term earnings drivers looks incremental rather than transformative.
The near term swing factor still sits in net flows and performance fee crystallisations on the $69.2b of eligible assets, not just one insurance relationship. The biggest live risk remains legal and flow related, including the PIFSS litigation and any downturn in AUM that could pull reported revenue and margins away from current frameworks.
The new Meiji Yasuda agreement links directly to one of the clearest existing catalysts for Man Group. This is the build out of its credit and private credit franchise that already runs $17.6b of private credit and holds $4.9b of uncalled commitments. Extra Japanese insurance capital offers more scale for those strategies and a more diversified client pool.
For investors watching catalysts, this announcement lines up with the earlier focus on deepening partnerships with large institutions that can support more stable AUM and fee streams. Execution still needs to show that these mandates are deployed efficiently, that performance justifies further allocations, and that any future equity tie up or product launches are managed without distracting from core profitability goals.
Man Group Consensus Assumptions in Context
Man Group's narrative projects $2.3b revenue and $713.0m earnings by 2029. This rests on analysts pencilling in 10.4% yearly revenue growth and an earnings increase of about 2.2x from $325.0m today.
Analysts are effectively arguing that if Man Group keeps growing its fee pool and improves profitability, the business could move from $325.0m of earnings today to $713.0m by 2029 on $2.3b of forecast turnover. That would mean profit almost doubles in dollar terms, while the P/E multiple they use in the model steps down from 14.3x today to 10.3x on those projected earnings.
For you as an investor, the important link is simple. The Meiji Yasuda partnership feeds into the same engine that analysts already model: higher revenue from a broader product mix and improved margins as the technology heavy platform scales. The numbers in the consensus case assume that this combination of extra capital, fee diversification and operating leverage does enough work to lift margins from 19.2% to 31.3% over roughly three years.
The forecast also bakes in only very modest share count growth of 0.12% per year over the next three years, so most of the step up in earnings power is coming from the income statement rather than from financial engineering. That puts more focus on whether Man Group can keep attracting large institutional mandates similar to Meiji Yasuda's, deploy them effectively into credit and private credit, and still hold to its 30% to 40% core profit before tax margin framework.
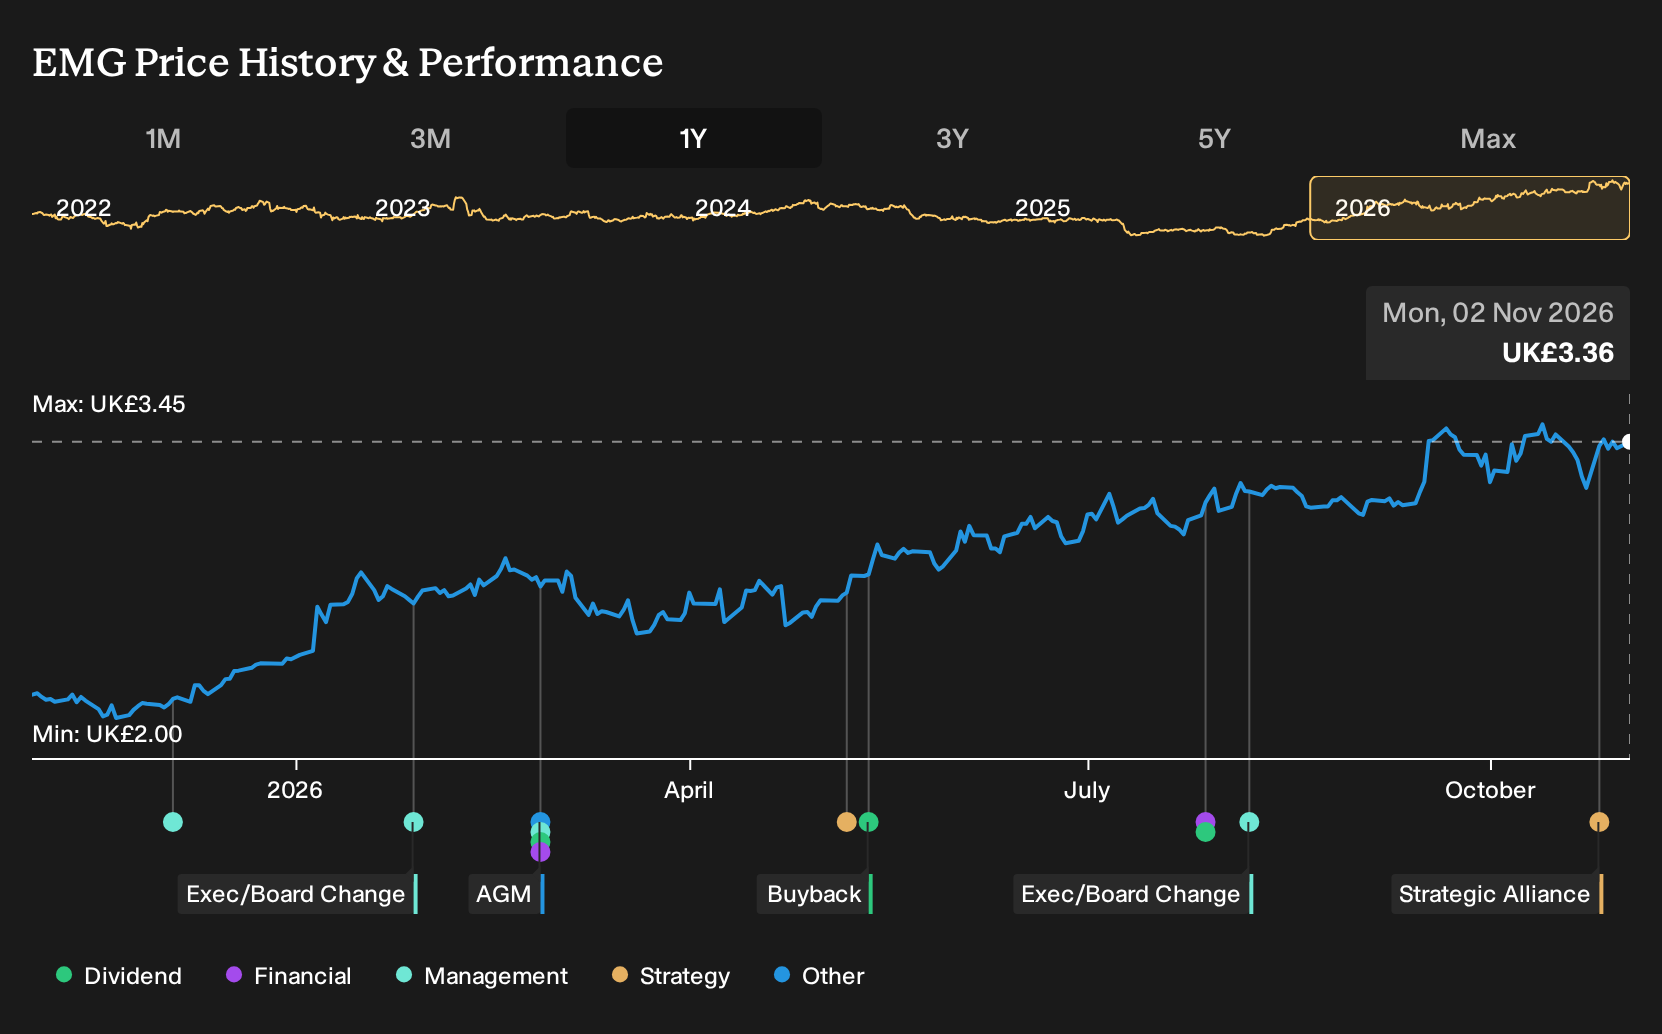
The analyst price target of £3.83, which sits 18.1% above the current £3.14 share price as of late 2026, simply reflects those revenue and earnings estimates discounted back using an 8.4% rate and a 10.3x earnings multiple in 2029. If you think the Meiji Yasuda deal improves the odds of Man Group reaching or revising those $2.3b revenue and $713.0m earnings figures, then this partnership matters as one more datapoint in an already numbers heavy narrative rather than a completely new story.
Uncover why Man Group's fair value indicates a 14% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
You might focus on Man Group's private credit push as a catalyst. The most optimistic analysts were already pencilling in about $2.3b of revenue and $703.6m of earnings by 2029 before this news. Those forecasts show how far opinions can stretch. Use this new Meiji Yasuda deal as a prompt to compare several viewpoints, not adopt just one.
Explore 4 other Man Group fair value estimates, including one that suggests up to 173% potential upside from the current price!
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider your own analysis and judgment.
- A great starting point for your Man Group research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Man Group. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Man Group's overall financial health at a glance.
Looking for more Man Group style investment ideas?
If you want to stress test your view on Man Group against alternatives, widen the search to companies with different balance sheets, income profiles and risk setups using the Simply Wall St Screener.
- For investors who care about resilient finances first, scan a list of solid balance sheet and fundamentals (10 results) that can serve as potential anchors alongside higher risk positions.
- If you are hunting for mispriced quality, weigh your thesis on Man Group against 13 high quality undervalued stocks that pair strong fundamentals with more modest expectations built into the price.
- Income focused readers can compare Man Group's profile with 5 dividend fortresses that combine higher yields with an emphasis on sustainability.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com