


EN
Gildan Activewear (TSX:GIL) Stock Looks Discounted As Shares Fell 34%
Gildan Activewear has seen its share price fall sharply this year, which naturally raises the question of whether the current valuation still lines up with the earnings the business is generating. With fresh news on portfolio changes and capital allocation, the market is reassessing what investors are really paying for each dollar of profit.
- The stock is down 33.7% year to date, putting fresh focus on whether the recent drop leaves the earnings multiple in a different place relative to where it has been in calmer periods.
- The completed sale of HanesBrands Australia for about A$700 million, and the plan to use the proceeds to repay debt, can influence how investors think about future interest costs, balance sheet flexibility and the value supported by ongoing earnings.
- There is a second opinion on Gildan Activewear worth weighing. See what analysts think Gildan Activewear's shares could be worth.
The issue now is whether the current share price of Gildan Activewear is appropriately supported by its earnings when judged against the Fair Ratio benchmark.
If you are weighing whether Gildan Activewear’s earnings still justify its current P/E after a 33.7% year to date fall, it can help to compare that question against 5 high quality undervalued stocks.
Is Gildan Activewear a Bargain on Earnings?
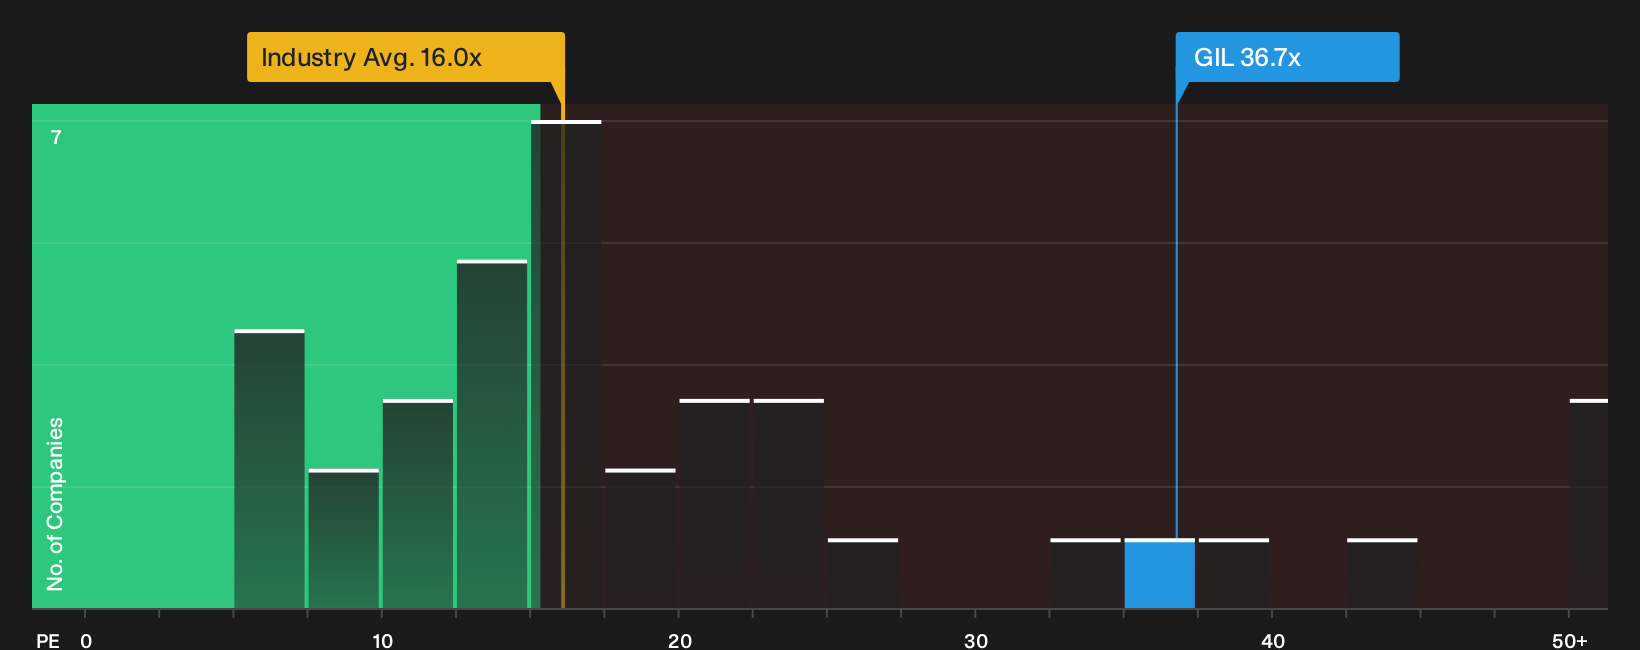
The P/E ratio suits Gildan Activewear because earnings remain the main anchor for how investors are sizing up the business. In this lens, the stock trades on about 36.7x earnings, which is higher than the Luxury industry average of roughly 14.6x and also above the peer group on about 31.9x. That points to investors paying a richer price per dollar of profit than is typical across the sector.
A Fair Ratio model that blends the company’s growth profile, margins, risk and size suggests Gildan Activewear trades below the multiple you might normally expect for that mix of fundamentals, so the current P/E sits in undervalued territory on this framework. Because the HanesBrands Australia sale proceeds are earmarked for debt repayment rather than chasing rapid expansion, the earnings focus behind this P/E lens becomes even sharper, since it puts more weight on what the existing operations can earn per share. Explore the numbers behind Gildan Activewear's P/E valuation.
The Gildan Activewear Narrative: What Would Justify Today's Price?
Simply Wall St Narratives for Gildan Activewear pick up where this valuation puzzle leaves off by spelling out which paths for future growth, profitability and earnings would need to play out for the stock to be worth meaningfully more or less than today’s price on the Community page. Rather than a single P/E or model output, each narrative lays out the key assumptions behind its view of fair value so you can compare those expectations with the results as they arrive.
One of the top community narratives on Gildan Activewear: 34% undervalued
"Rising labor costs, supply chain volatility, and weak pricing power threaten margins and profitability in Gildan's core commoditized apparel business..."
Discover why this Narrative puts Gildan Activewear at 34% undervalued.
One more piece of the Gildan Activewear puzzle to check
Before leaning too hard on today’s P/E and market narrative for Gildan Activewear, it helps to see where professional analysts currently expect profits and cash generation to land a few years from now. Explore where analysts expect Gildan Activewear to be in a few years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com