


EN
Dutch Bros (BROS) Stock Climbed, What Is Driving Attention Now?
Why Dutch Bros Stock Is Back On Traders’ Radar
Analyst projections for Dutch Bros (BROS) calling for higher quarterly earnings, stronger company-operated shop revenue, and increased net new store openings have pulled fresh attention to the stock’s recent performance.
Forecasts of $0.24 in earnings per share and an estimated 31% rise in company-operated shop revenue, along with 52 net new locations versus 38 a year earlier, frame the latest expectations.
Dutch Bros shares have picked up short term momentum, with a 1 month share price return of 13.45% and a 7 day gain of 4.40%, even though the 90 day move is still down 31.57% and the 1 year total shareholder return is lower by 19.49%.
Recent enthusiasm around the upcoming earnings release and the latest holiday menu launch appears to be shifting sentiment, as traders weigh the stronger near term share price performance against a longer track record that includes a 64.92% total shareholder return over three years, but a decline of 35.30% over five years.
Scan other high growth consumer stocks that show similar earnings and expansion setups using the hand picked 19 high quality undiscovered gems that might complement a position in Dutch Bros.
Bulls point to Dutch Bros’ expansion and earnings forecasts, while bears focus on the uneven share price record. Which story does the current valuation actually support, as the next section weighs the numbers?
Most Popular Narrative: 33% Undervalued
Against the last close at $43.87, the most followed Dutch Bros narrative pegs fair value at $65.92. This frames the current debate around whether the expansion story is being fully recognised in the share price.
Dutch Bros continues to target aggressive national expansion toward 2,029 shops by 2029, supported by a dense real estate pipeline that management reports is already about 90% secured and at least 185 planned system openings in 2026, which could increase total revenue and aggregate earnings power as new units mature.
See why 85 investors see Dutch Bros as 33% undervalued.
Result: Fair Value of $65.92 (UNDERVALUED)
Still, rising labor and input costs, along with softer same shop sales than guided for 2026, could quickly challenge the current Dutch Bros undervaluation story.
Find out about the key risks to this Dutch Bros narrative.
Another View: Dutch Bros On Rich Earnings Multiples
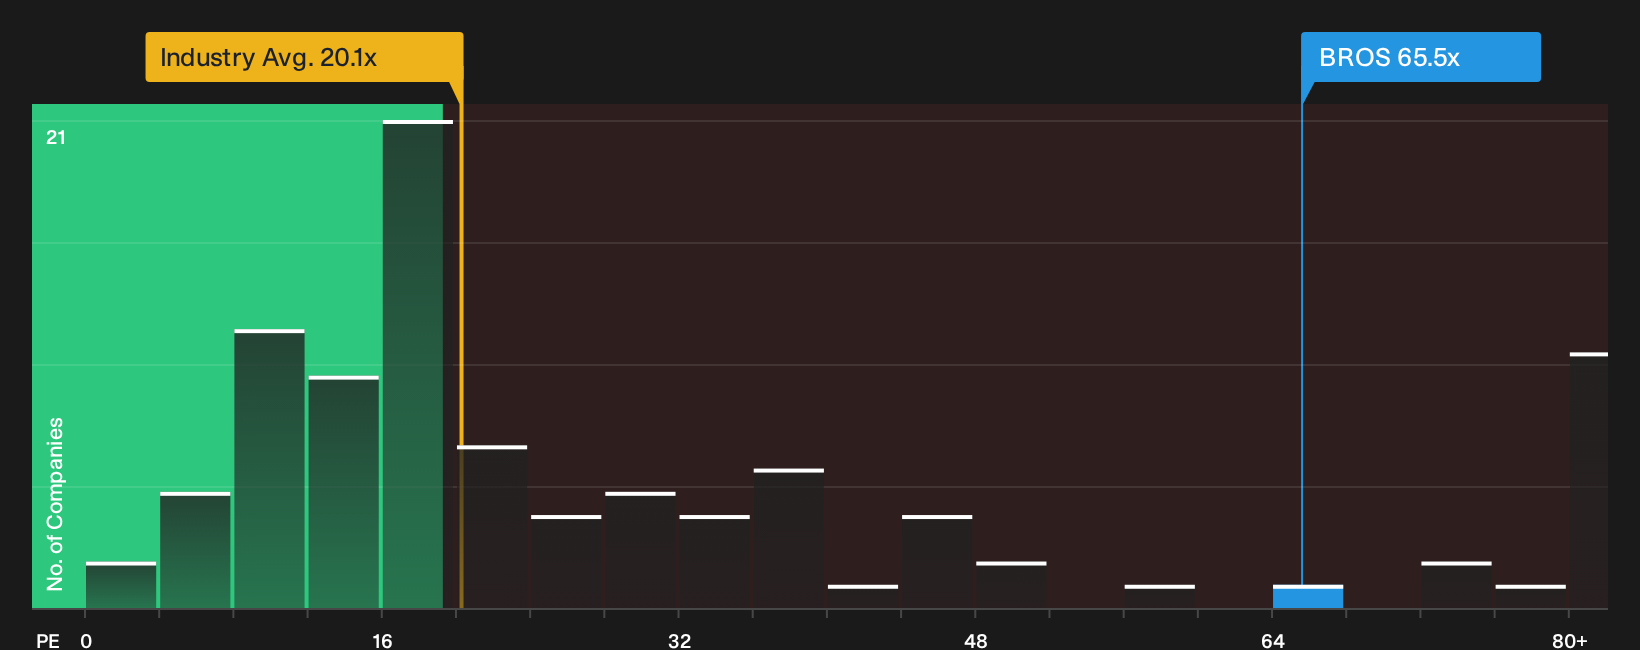
The fair value narrative paints Dutch Bros as 33.4% undervalued, yet the earnings multiple tells a different story. The stock trades on a P/E of 65.5x, compared with a fair ratio of 28.2x, the US Hospitality average of 20.1x, and a peer average of 63.6x. That kind of gap can leave less room for error if growth or margins slip. The key question is how much valuation risk you are willing to carry for this expansion story.
For a clearer sense of how these earnings multiples stack up against what the fair ratio suggests the market could move toward over time, take a look at the See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Sentiment on Dutch Bros is clearly split, so treat this as your cue to move fast, review the numbers yourself, and weigh both sides of the story using the 3 key rewards and 1 important warning sign.
Looking For More Investment Ideas Beyond Dutch Bros?
If Dutch Bros has your attention, do not stop here. Broaden your watchlist with other focused ideas that could sharpen how you allocate your next dollar.
- Target resilient balance sheets and steady fundamentals by scanning the list of solid balance sheet and fundamentals (24 results) for potential anchors in a more volatile portfolio.
- Hunt for mispriced quality by using the 34 high quality undervalued stocks to spot companies where fundamentals and current pricing appear out of sync.
- Tilt toward stability and income potential by reviewing the 4 dividend fortresses for businesses offering higher yields with a focus on durability.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com